alternative-underwriting
(3)
OneBlinc Bet on Payroll Loans. Then the Money Got Expensive.
The Miami fintech built a data engine around public-sector payroll loans, raised a $100 million credit facility, and then watched higher rates squeeze the model. Its answer was a fast pivot to a smaller, subscription-priced payday bridge - and a revealing lesson in knowing when your first product has become your baggage.
Pave Spent $1.7 Million Trying to Sell Shares in People - Then Learned Everyone Preferred a Loan
The New York fintech began with a provocative bargain: fund a young person now and share in their future income. Its retreat into ordinary loans is a compact lesson in why financial products must be understandable before they can be clever.
TomoCredit
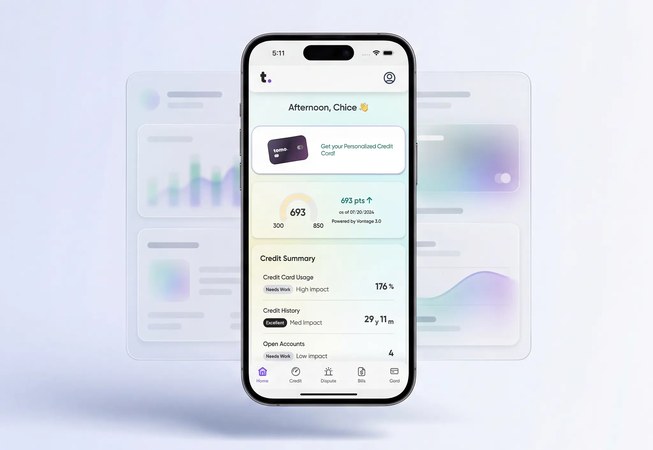
TomoCredit is a San Francisco fintech that issues a credit card to people the traditional system can't see - immigrants, students, and first-time borrowers with no FICO score. Instead of a credit check, its proprietary 'Tomo Score' underwrites applicants on cash-flow and bank data, with no deposit, no APR, and no fees, earning revenue purely from merchant interchange. Founded in 2018 by Kristy Kim after she was denied a car loan as a Korean immigrant with no credit history, the company has processed millions of applications and is now building TomoIQ, an AI financial assistant that turns professional-grade money guidance into something anyone can use.