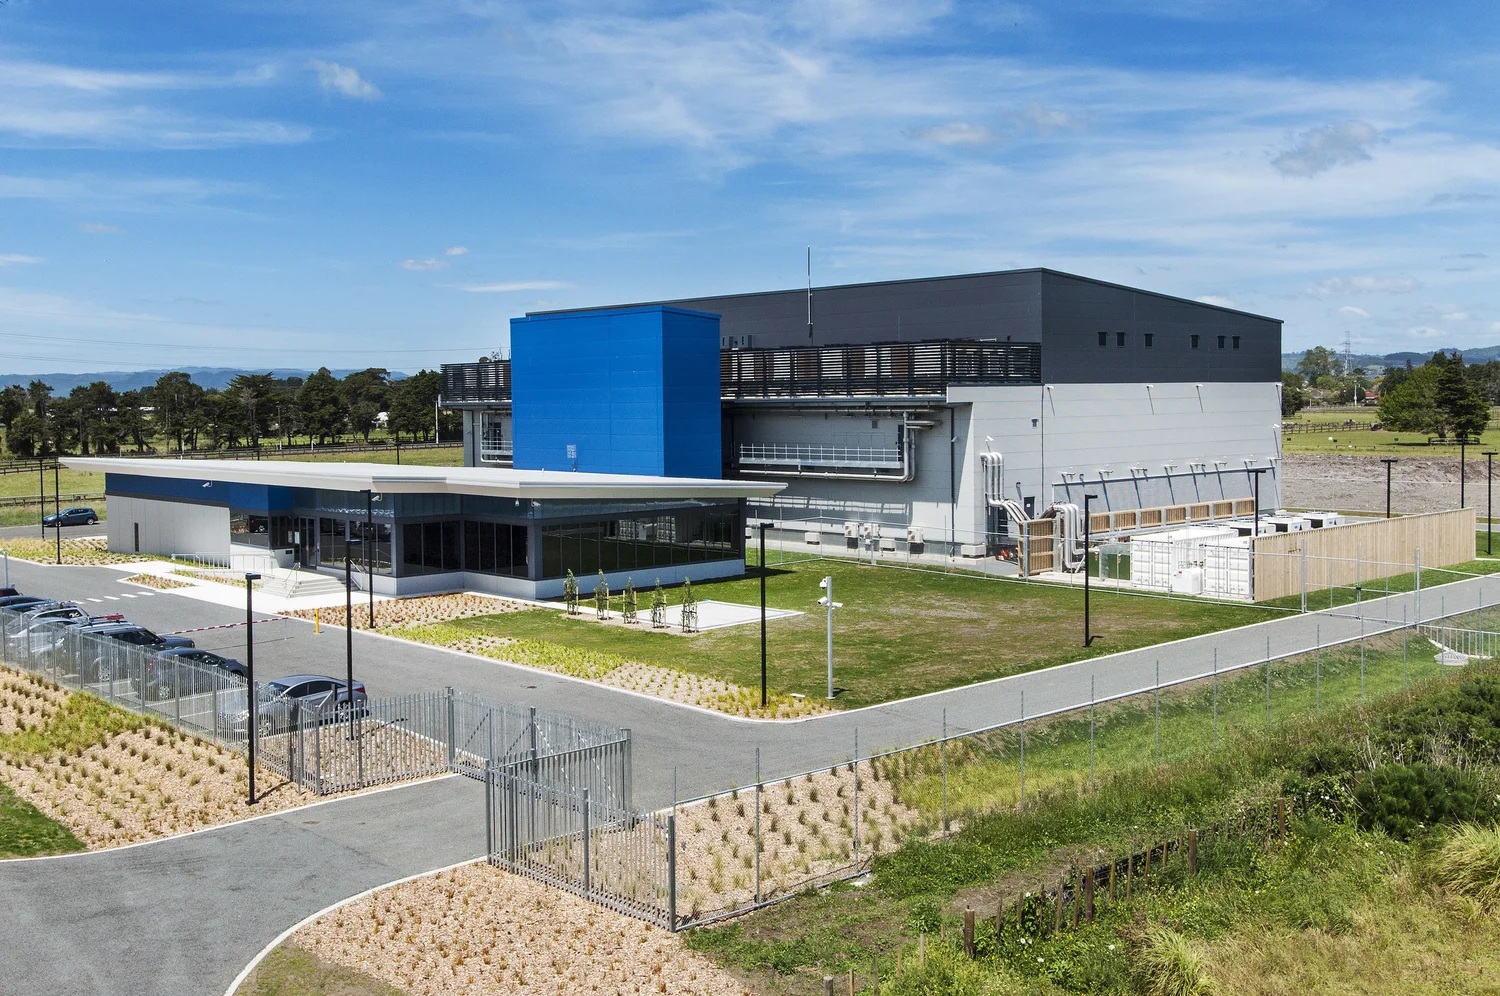
The cloud looks surprisingly earthbound in Spark’s data-centre photograph: a broad industrial building, a blue wall, perimeter fencing and a car park. Nothing floats. Everything needs capital. In January 2026, New Zealand’s former Telecom completed a deal that put a different owner in charge of most of that business. For a company that once stretched from phone lines into sports streaming, the transaction poses a useful question: how much does Spark need to own to be useful?
Its answer is getting narrower. Spark supplies mobile service, broadband and the technology that keeps organisations connected. It also sells cloud, IT and security services. But the company’s SPK-30 strategy puts connectivity first, after years of broader digital ambitions. The distinction matters to customers as much as shareholders: every venture competing for investment also competes with the network, the bill and the person answering a support request.
The customer stays. The ownership changes.
The data-centre transaction left Spark with 25% of the business and Pacific Equity Partners with 75%. The operation became TenPeaks Data Centres. Spark received NZ$453 million in initial cash proceeds, with up to approximately NZ$98 million more contingent on performance objectives. The headline enterprise value of up to NZ$705 million included an earn-out; it was not the cheque Spark received.
Spark also remained a customer. That makes the deal more interesting than a simple retreat. It exchanged control for cash and a partner able to support expansion, while keeping exposure to the outcome. The announced development pipeline exceeded 130MW, compared with more than 23MW operating at completion. Those figures describe a plan and an existing estate, respectively. A pipeline still has to be built.
There is a practical lesson here for a business considering a partner: write down which relationship you are trying to preserve. Spark could continue buying data-centre services without financing every future expansion itself. That arrangement depends on service quality, contractual access and aligned incentives. Minority ownership offers participation; it does not offer the same control as owning the whole operation.
Before the cloud came the Post Office
Spark’s origin is unusually unromantic. No garage, no pair of founders sketching a logo. Telecom began operating in 1987 when the New Zealand Post Office was divided into separate telecommunications, postal and banking businesses. It was privatised in 1990 for NZ$4.2 billion. The company’s official history also records the launch of New Zealand’s first mobile network in 1987. The state supplied the starting point; competition changed the job.
A decisive separation followed in 2011. Chorus became the wholesale fixed-network company, while Telecom retained retail services and its mobile network. This remains essential to understanding the market: a Spark fibre subscription does not mean Spark owns the fibre running past the house. Retail service and underlying infrastructure can belong to different businesses. The customer experiences one connection, assembled from several responsibilities.
The Spark name arrived on 8 August 2014. Contemporary shareholder communications said customer research showed that Telecom was losing resonance, especially among younger people. The company had moved beyond the home telephone into broadband, entertainment and cloud computing. A new name made that ambition visible. It could not settle the harder question of which new businesses would earn their place.
The cricket bill outlived the stream
Spark Sport is the clearest caution. Launched in 2019, it entered a market where the product depends on buying permission to show somebody else’s contest. When Spark announced its exit in December 2022, it pointed to rising content-rights costs, disappointing scale and disruption from Covid. There was also a technology deadline: its licensed iStreamPlanet platform would no longer be available for third-party use in the second half of 2023.
Continuing would have required a replacement platform and a customer migration, as well as the continuing cost of rights. Most content moved to TVNZ from July 2023. Spark announced a NZ$52 million one-off provision covering obligations that included rights agreements extending to FY28. That number describes the exit provision, not the venture’s entire lifetime cost. The stream could stop before the commitments did.
In Spark’s account, audience growth fell short before the exit decision; the platform replacement decision then sharpened the choice. That sequence is worth copying into any subscription-business review. Check whether customers are arriving fast enough to support commitments already made. Then price the next unavoidable investment separately. Money spent yesterday supplies context, but the decision to continue has to survive tomorrow’s bill.
What a customer actually buys
For a household, Spark is primarily a way to get online and stay reachable: mobile plans, phones, broadband and associated services. Its main mobile-network alternatives are One New Zealand and 2degrees. For an organisation, the purchase can include managed networks, collaboration, cloud infrastructure and security. Spark sits between global technology suppliers and New Zealand customers who need those technologies to work together.
The smaller-business version is refreshingly concrete. Spark IT connects customers through local business hubs to partner firms providing services such as IT support, infrastructure, cloud and security. Charges can appear on the Spark bill. Consolidated billing will not make a failing laptop behave, but it can remove a layer of supplier administration. The selling point is coordination and local support, not a claim that Spark invented every component.
Cloud work follows a similar logic. In June 2024, Microsoft named Spark-group company CCL its first at-scale launch partner for the New Zealand cloud region. Scales Corporation was identified as an early migration customer. This is where local expertise can earn a fee: deciding what moves, helping it move and keeping applications usable afterward. A direct cloud account gives a business infrastructure; a capable services partner helps it operate that infrastructure.
The business model combines recurring connectivity and managed-service payments with prepaid usage, devices and project work. Its competitive case is the combination of network capability, domestic relationships and support. Buyers should still compare an actual address, workload and service requirement. A national brand cannot tell a family how reception behaves in its kitchen, or tell a business whether a particular support contract meets its needs.
A cheaper connection, a more local internet
Spark’s purpose, to help all of New Zealand win big in a digital world, is broad enough to fit on almost anything. Skinny Jump gives it a price tag. The published prepaid offer provides 35GB for NZ$5, valid for 30 days, with up to six renewals per month, a free modem and no credit check. Sign-up runs through community partners for eligible households.
Affordability has physical limits. Jump’s address checker can reject a home because it sits outside coverage or because the relevant tower sector has reached its modem limit. A lower price does not create radio capacity. For someone who qualifies and can connect, however, avoiding a long contract and a credit check removes obstacles that a faster premium plan would leave untouched.
Then there is Kupu, the free app launched in 2018 with Google and Te Aka Māori Dictionary. Photograph an object and it offers Māori words for what it recognises. The pleasure is in making an ordinary object a prompt to learn. Spark and Te Aka won the 2018 Supreme Māori Language Award for the project. Here, relevance comes from language expertise and collaboration, with technology giving that knowledge another route into everyday life.
The organisation is still under reconstruction
Spark tried changing how it worked as well as what it sold. Its 2018 move to company-wide agile working replaced much of the old hierarchy with smaller, cross-functional teams. In a later ICAgile case study, Spark described coaches and training as necessary to sustain the change. One telling detail: a coach said Scrum did not suit the reactive work of a cybersecurity team. Even an organisation-wide change needed room for exceptions.
The newer operating model relies more on outside technology partners. Microsoft’s 2025 agreement covered Azure, Copilot and staff learning. HPE described a staged infrastructure overhaul using GreenLake and Morpheus to bring cloud management together. These are different jobs: one changes access to software and cloud services; another changes how infrastructure is managed. Neither is a licence to stop checking whether customers benefit.
There is a cost to restructuring before there is a saving. Spark’s FY25 report identified NZ$53 million of transformation costs associated with its SPK-26 Operate Programme. FY26 reporting put employee headcount at 3,416. Announcements about efficiency can sound frictionless; reorganising work and changing suppliers are not. A credible account has to keep the spending and the people in view alongside the promised productivity.
“Connectivity is our core business, and our absolute focus in the years ahead.”
Jolie Hodson, September 2025
Read the recovery in two columns
The August 2026 results showed progress without an all-clear. FY26 free cash flow rose 18.5% to NZ$308 million and mobile service revenue returned to growth at 1.1%. Adjusted EBITDAI, Spark’s operating earnings measure before financing, tax, depreciation, amortisation and net investment income, declined 2.4% to NZ$1.035 billion. The reported profit also benefited from the data-centre sale. Selling an asset and improving ongoing trading are different contributions to a result.
The portfolio remains unsettled. Spark’s FY26 presentation disclosed a strategic review of Digital Services, with no certainty of a transaction. It also reported total broadband connections down 4.8%. Those details make the reset harder to dismiss as branding, and harder to declare finished. A narrower company still has to win and retain customers in competitive markets.
The useful rule to borrow from Spark is to examine ownership, commitments and customer value separately. Share the assets whose expansion needs another investor. Reconsider services whose next bill outruns their prospects. Keep expertise where it makes someone’s working day easier. That reasoning depends on having credible partners and customers willing to stay. Spark’s next verdict will come from people deciding whether to renew, switch or call for help.
Keep exploring Spark
Watch / Kupu in action