At ROTH Capital Partners, the calendar is part of the machinery. Company presentations, investor meetings, roadshows and conferences create repeated opportunities for executives to explain why their businesses deserve money. The setting can be a California resort. The underlying question is less relaxing: who will buy the shares, and at what price?
The investment bank has made a business of connecting growth companies with investors willing to study them. Its territory includes small public companies, a corner of the market where winning attention can be almost as demanding as winning customers. ROTH arranges financings and acquisitions, publishes research and executes trades. The conference invitation is one entrance to a much larger operation.
That operation now stretches from Newport Beach to a global trading floor in Stamford, Connecticut. ROTH describes itself as employee-owned. Its appeal rests on a specific proposition: a company can find sector knowledge, investor introductions and transaction execution within the same firm. Whether those introductions become durable investment depends on what happens after the presentation.
A room full of possible shareholders
ROTH’s corporate-access department reports relationships with more than 1,000 institutional clients and over 350 deal and non-deal events annually. The distinction matters. A deal roadshow seeks buyers for a transaction; a non-deal roadshow lets management meet investors without an offering attached. The latter keeps conversations going between financing deadlines.
Its flagship conference combines individual meetings, presentations and analyst-led discussions. The 39th annual gathering, scheduled for March 7-9, 2027, in Dana Point, anticipates approximately 500 public and private companies. Attendance is by invitation and registration requires approval. This is a curated commercial audience, with entertainment and athletic charity events woven around the appointments.
For executives, the practical benefit is concentrated access to potential shareholders. For fund managers, it is a way to compare businesses and question management teams without arranging a separate trip for each one. Neither side is buying certainty. Both are trying to make better use of scarce attention.
A map of services, not a promise that one step produces the next.
Before the name on the door was Roth
The firm’s lineage begins with Walter Cruttenden, whose Capital Data Bank matched private businesses with investors by computer. Cruttenden & Co. was founded in 1984. Byron Roth arrived in 1992 and eventually took control; the Roth Capital Partners name followed in 2000. The matching problem survived the change of stationery.
The succession had friction. The Orange County Business Journal later described an acrimonious period before Cruttenden left, followed by a restored friendship and investments by Roth in Cruttenden-founded companies. In its 2018 account, Roth said: “We’ve had a few bumps along the way.” It is an unusually plainspoken footnote to a company that puts relationships at the center of its identity.
The operating LLC has a more recent legal birthday: February 2, 2001, according to its financial-condition filing. Separating that date from the business’s 1984 founding avoids turning an entity conversion into an origin story.
The price of getting a deal done
ROTH’s investment-banking menu includes IPOs, follow-on offerings, registered direct offerings and private placements. Its M&A work includes company sales, acquisitions, divestitures, special-committee advice and fairness opinions. A business can therefore approach the firm to raise money, assess a strategic transaction or sell, with a senior banker assigned from inception through closing.
One transaction makes the economics tangible. In April 2026, Lifezone Metals offered 5.7 million ordinary shares at $4.40 each, generating $25.08 million in gross proceeds. Its prospectus supplement named ROTH exclusive placement agent and specified a 6% cash fee: $1,504,800. Proceeds after that fee, before other expenses, were $23,575,200.
Lifezone Metals gross proceeds
Rounded display. One transaction’s terms, not a firm-wide rate card.
The same filing says the agent had no obligation to purchase the securities or arrange a particular dollar amount of sales. That qualification explains the service: arranging a placement does not automatically put the bank’s own balance sheet behind it. For an issuer, financing costs also extend beyond the agent’s fee to other offering expenses and the ownership dilution associated with issuing shares.
ROTH’s business has several revenue routes: transaction and advisory compensation, brokerage activity and paid research products. These depend on different kinds of customer demand. An investor buying a custom study is commissioning information; an issuer hiring a placement agent is seeking a completed financing.
The analysts behind the introductions
Research gives those conversations something to work with. ROTH’s research page describes 30 analysts covering more than 500 companies. Their work includes industry contacts, channel checks and financial analysis across areas such as healthcare, technology, consumer businesses, energy and sustainability. A biotech discussion and a semiconductor discussion require different expertise, even when both end with a valuation.
There is also a less visible product: the Quantitative Survey Group. It designs custom studies for investors, including private-equity and venture-capital clients. The group advertises subscription and individual-project options, with surveys addressing particular consumers, companies or markets. An investor can commission evidence about a thesis instead of relying entirely on management’s account.
The survey group lists global panel relationships, including WebMD, and reports more than 400 custom due-diligence and strategic-research projects for private-equity and venture-capital clients, including portfolio companies. Its usefulness depends on asking an answerable question of the right respondents. A carefully designed survey can test demand; it cannot eliminate uncertainty about a business.
On the execution side, ROTH offers equity, options, portfolio, index and credit trading. Its trading desk describes pre-trade estimates and post-trade analysis for portfolio orders. That matters when an investor needs to move a position while managing market impact. Research may explain the opportunity; execution determines what it costs to enter or leave.
Why Stamford entered the picture
The February 2023 acquisition of MKM Partners expanded the operation. MKM brought institutional research, sales and trading capabilities, including derivatives and event-driven work. ROTH announced that the combined business would operate as ROTH MKM, with more than 235 employees and over 500 stocks under coverage at closing.
The leadership arrangement was consequential: MKM’s Sagar Sheth became CEO, Byron Roth became executive chairman and Aaron Gurewitz became president. The acquired firm supplied the chief executive as well as additional services. That made the combination a reorganization of leadership, not simply an enlarged analyst list.
The stated commercial rationale was broader institutional brokerage capability. The acquisition announcement described MKM’s global equity and U.S. options execution alongside macroeconomic and technical analysis. The strategic reading is straightforward: ROTH could serve more of an institutional investor’s working day, including the days when no company was raising capital.
“We’ve had a few bumps along the way.”Byron Roth, discussing his history with Walter Cruttenden, 2018
When the numbers stopped persuading
The history also contains a harder lesson about the limits of distribution. A 2011 Reuters investigation examined Chinese companies reaching U.S. markets. It reported that China Biotics, a ROTH client, delisted from Nasdaq in June, 19 months after ROTH helped it raise more than $79 million. Its auditor had resigned amid accusations involving forged documents and a fake website overstating cash holdings. Reuters reported that Byron Roth declined to comment.
In November 2012, The Wall Street Journal reported ROTH’s retreat in China as investor confidence in reverse-takeover deals deteriorated following accounting scandals. The observable change was a smaller operation in that market. It would be a stretch to assign a private change of heart to management.
What failed in this episode was confidence in the underlying financial information. A distribution network can introduce a business to investors; it cannot make unreliable accounts dependable. For readers studying ROTH’s model, that is a substantive condition on its success: access works only when the company merits the scrutiny that access brings.
Some meetings require a bicycle
ROTH’s relationship-building extends beyond meeting rooms. The firm says it has raised more than $2 million for the Challenged Athletes Foundation since 2012, including through its conference cycling events. Its connection to the charity came through Duane Roth, Byron’s older brother, who died in 2013 after injuries sustained in a cycling accident during a CAF event.
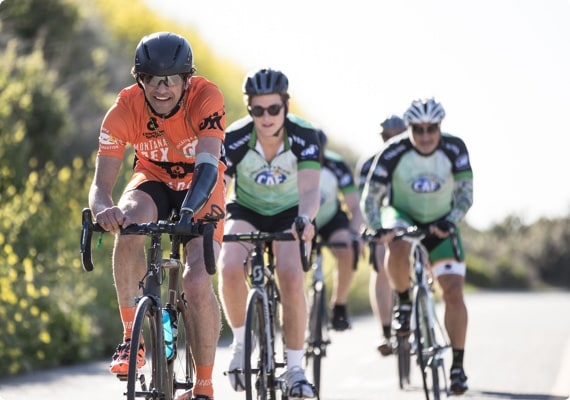
The firm also supports organizations including the Boys & Girls Clubs, Elephant Cooperation and Orangewood Foundation. These commitments help explain the social texture around the conferences. The company’s own culture statement emphasizes individual strengths and long-serving staff, some with more than two decades at the firm. That is its account of the workplace, rather than an independent employee survey.
A small-cap specialty with a wider reach
Recent transactions show the breadth of the franchise. ROTH’s August 2026 news listings identify it as lead manager on WhiteFiber’s $310 million convertible senior notes, co-manager on AST SpaceMobile’s $1.15 billion convertible senior notes and sole book-running manager on Evolution Petroleum’s $13.8 million follow-on. Those figures describe total transactions, not money supplied by ROTH or revenue earned by the bank.
Competitors such as Piper Sandler and William Blair also combine capital raising, advisory work and research. ROTH’s distinction is the particular mix of a longstanding small-cap franchise, a recurring conference circuit and institutional capabilities expanded through MKM. Service overlap makes sector fit and the actual team more useful comparison points than the length of a capabilities brochure.
The part other businesses can copy is the cadence: maintain useful contact before a transaction becomes urgent, develop expertise that gives people a reason to listen and make introductions specific. A company evaluating ROTH can apply the same discipline. Identify the capital need, the likely investor audience and the evidence those investors will require. A room full of possible shareholders is valuable. A business prepared to answer their questions is what gives the meeting a chance.