The interesting part of a mortgage payment is what happens after it leaves your bank account. Someone records it, forwards the money, handles the escrow and answers the phone when something goes wrong. These chores generate fees. In 2013, a newly public company called New Residential built its investment case around the rights to a portion of that income.
Today, that company is Rithm Capital. Its businesses originate mortgages, finance developers, manage investment funds and operate office buildings. The connecting idea is practical: owning the people and processes behind an asset may reveal things that a financial model misses.
- Start with a fee. Mortgage servicing rights supplied the original opportunity.
- Buy the operator. Newrez and Genesis brought lending and servicing inside the group.
- Manage more capital. Sculptor and Crestline added investment teams and fund clients.
The fee hiding in the payment
A mortgage servicing right, or MSR, is a right to fees for administering a loan. The distinction matters. Servicing a $300,000 mortgage does not mean owning a $300,000 asset. It means performing work around that mortgage and collecting compensation under the servicing arrangement.
Rithm moved closer to that work when it bought Shellpoint in 2018, adding the business now known as Newrez. Acquiring Caliber Home Loans in 2021 expanded its origination and servicing capabilities. That year also brought Genesis Capital, which finances professional developers building, renovating and repositioning residential properties.
The attraction is a feedback loop. Origination provides access to new assets. Servicing supplies continuing information about payment behavior. Financing and securitization turn pools of loans into investments. Rithm describes these connected capabilities as its owner-operator advantage. The claim is credible as an operating design; superior investment results still have to be earned.
Payment and operating information feeds the next underwriting decision.
When the funding stopped
March 2020 exposed a weakness that an operating diagram cannot solve. Mortgage-market liquidity evaporated. Falling asset prices triggered demands for collateral from lenders financing New Residential’s holdings. A long-lived investment could suddenly require cash today.
Its annual report describes selling approximately $6.1 billion face value of non-agency mortgage securities in April and raising $600 million through a private senior secured loan. In May, management reported about $27.9 billion of asset sales across its response. These are different measures and time windows, but both show the scale of the retreat.
Management then stated a preference for term-financed or low-leverage investments and a primary focus on operating businesses. Shellpoint already existed inside the group; the crisis sharpened an established direction. The useful lesson is about funding: an asset’s eventual cash flows offer little comfort when your lender can demand collateral before they arrive.
Independence came with an invoice
In 2022, New Residential internalized management from a Fortress affiliate and adopted the Rithm name. The termination agreement cost $400 million. At announcement, the company projected annual savings of $60 million to $65 million. Those were forecasts, alongside the immediate obligation to pay.
The next major step was Sculptor Capital Management. Rithm’s original offer of $11.15 per Class A share rose to $12.70. The amended agreement secured support from founder Daniel Och and other former executives, who agreed to dismiss pending litigation. The November 2023 closing announcement valued the transaction at approximately $719.8 million.
Here was a different economic engine: managing other investors’ money. Sculptor brought corporate credit, real estate and multi-strategy expertise. Crestline, acquired in December 2025 for approximately $324.7 million in cash consideration, added private credit and fund liquidity capabilities.
“We operate inside it, originating loans, managing buildings, servicing mortgages.”
Michael Nierenberg · on Rithm’s operating model
A fund manager walks into an office building
Also in December 2025, Rithm completed its Paramount acquisition. The annual report records approximately $1.8 billion in consideration, including capitalized transaction costs. The office platform became Elecor Properties in April 2026. Rithm and key joint venture partners planned roughly $250 million in improvements across its portfolio.
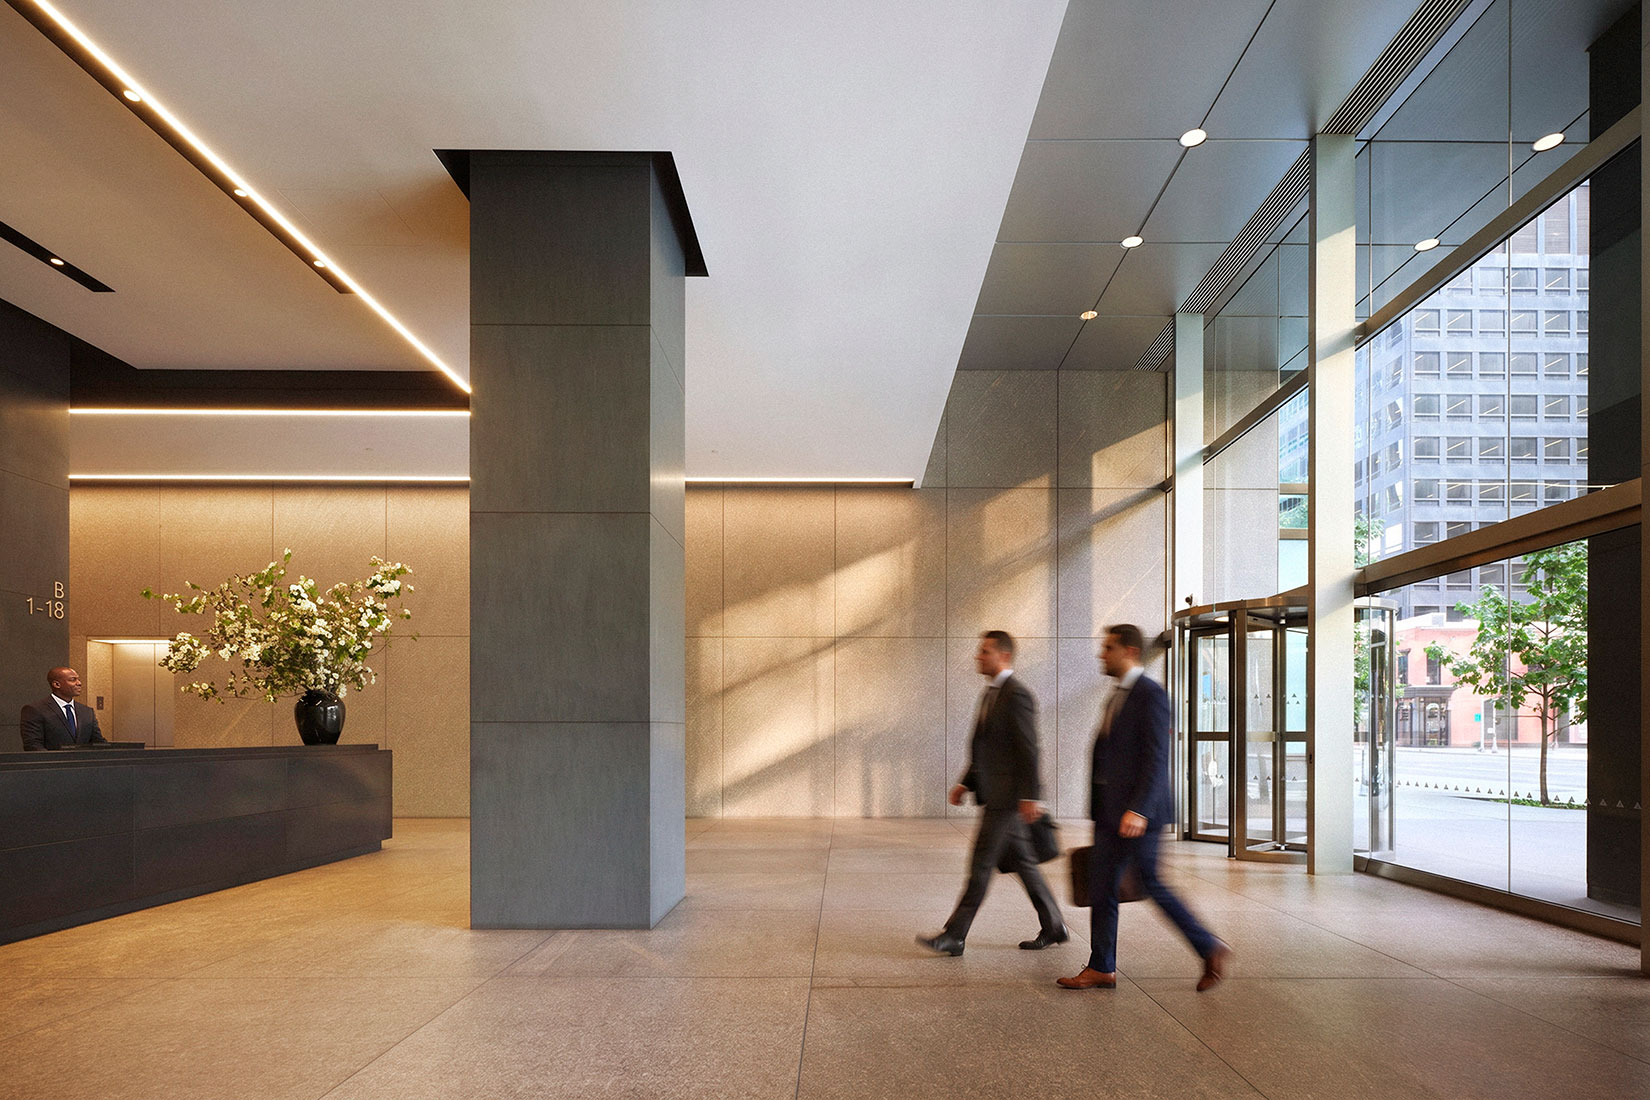
Office buildings make the thesis wonderfully literal. Their performance depends on leases, tenants, maintenance and spaces people want to occupy. Buying a property supplies exposure; operating it creates a daily list of decisions. Whether improvements earn their cost depends on tenant demand and execution.
In October 2026, Rithm brought a DRA Advisors-managed fund into a joint venture at 1301 Avenue of the Americas. Rithm retained majority ownership and the operating role. Bringing in outside capital while continuing to run the building neatly expresses its broader ambition.
Who gets to use the machinery?
The customer enters through different doors. A homeowner can borrow or refinance through Newrez. A professional developer can seek construction financing from Genesis. Institutional and wealth investors encounter investment strategies through affiliated managers. Office tenants deal with Elecor. Rithm stockholders own an interest in the parent company.
This also explains the competitive map. Mortgage businesses overlap with Rocket and PennyMac; fund management overlaps with firms such as Ares, Apollo and Blackstone. Rithm’s particular combination spans both operating fees and investment management, alongside returns on its own capital. It is a more complicated proposition to evaluate than a single lending business.
Estimated asset management AUM
Newrez servicing unpaid principal balance
Managed investments and administered loan balances measure different activities. These figures should not be added together.
The operator still has to deliver
The next test includes software. In February 2026, Rithm announced expanded minority ownership in Valon and plans to deploy ValonOS across Newrez servicing, targeting 2027. The announcement covered more than four million homeowners. A planned rollout is a promise about execution, rather than evidence of savings already achieved.
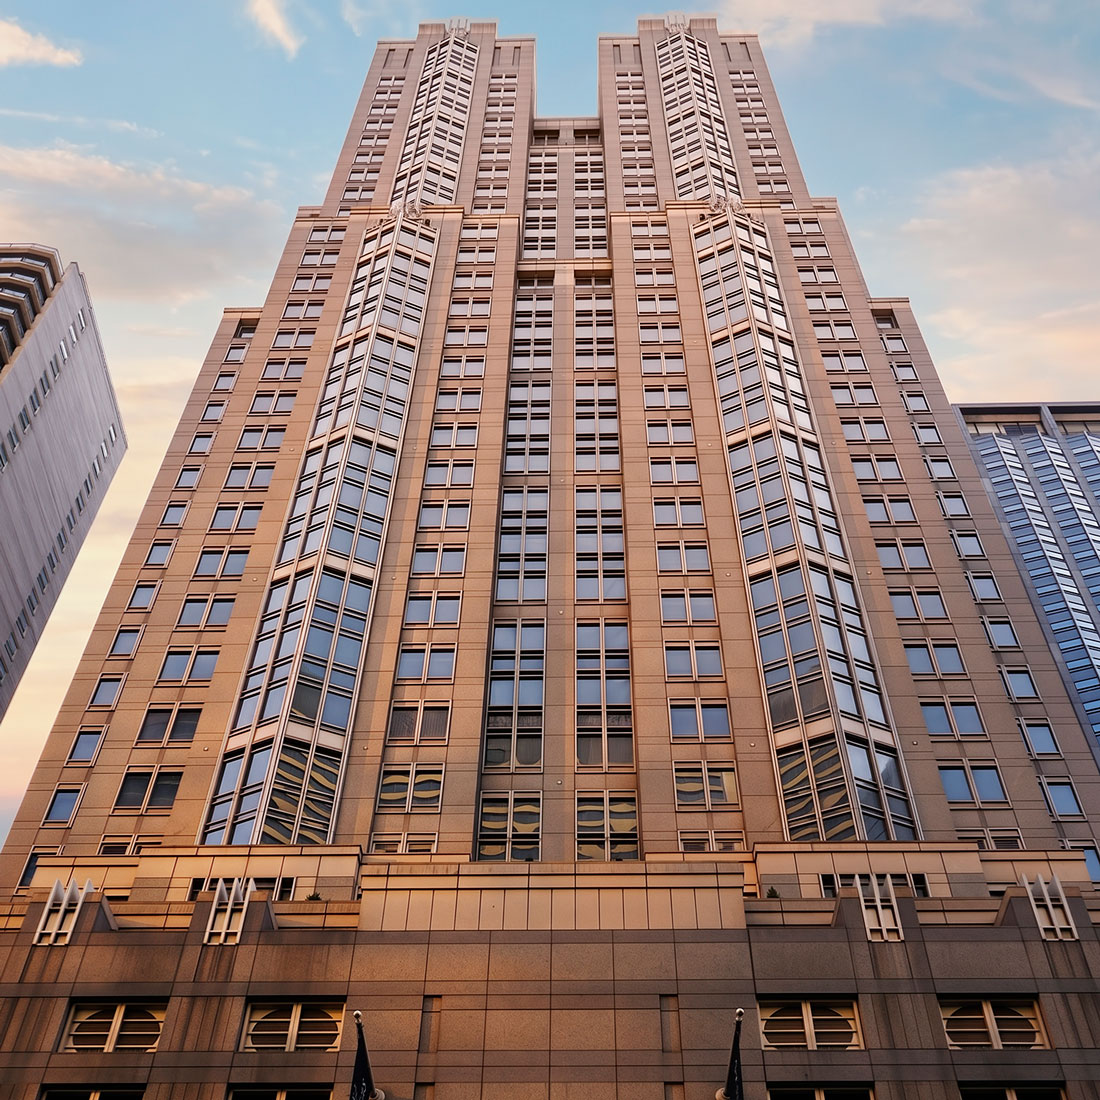
There is something readers can borrow here: follow an asset back to whoever makes it, and forward to whoever maintains it. Get closer to the decisions that determine its value. Then examine the funding, because operating knowledge cannot prevent refinancing pressure, credit losses or weak leasing.
Rithm has assembled more ways to earn, and more businesses to run. The question is whether the information and control gained from owning the machinery justify the money and attention required to keep it working.