Rhomaios Ram has a useful way of explaining foreign exchange settlement: imagine a prisoner exchange in an old spy film. Two sides approach a bridge. Each watches the other. Nobody wants to release their prisoner before the opposite side does the same. Remove the trench coats and the suspicious glances, and you have a problem that occupies a surprising amount of modern banking.
Ram used that analogy in a 2022 conversation with Peter Renton. It is a good introduction to his working world. A price can be agreed quickly; completing both sides of the bargain is another matter. The awkward interval between agreement and completion is where money gets tied up, checks multiply and institutions worry about the other party keeping its promise.
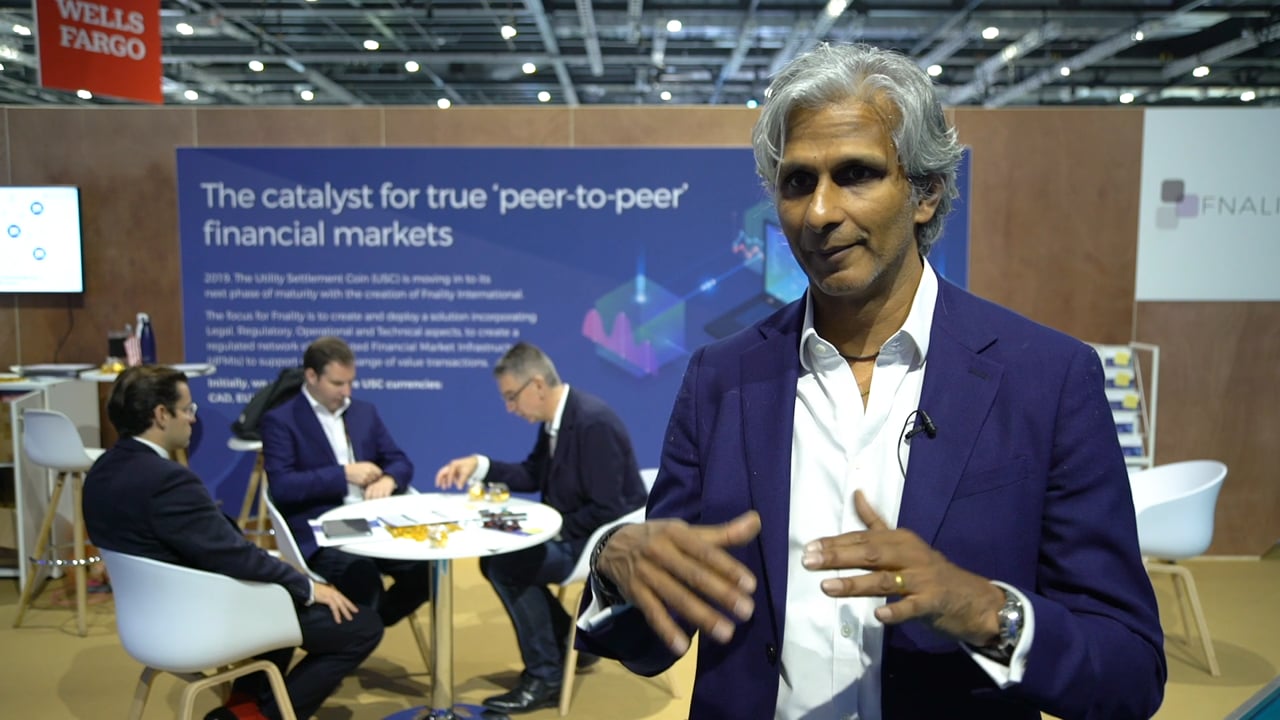
Today Ram is founder and strategic advisor at Fnality International, the company he led from its inception. His career has passed through foreign exchange, electronic trading and transaction banking. The recurring subject is what happens when finance acquires a faster computer but keeps the habits of the slower one.
His recent work takes that question somewhere less obvious. Much of digital finance has been occupied with getting assets onto blockchains and moving them between networks. Ram is asking how much movement is actually necessary. A bond can remain on its own ledger. Cash can remain in its payment system. What matters is that the purchase becomes final on both.
That is a rather particular ambition. An industry fond of motion has produced a founder interested in the virtues of staying put.
Before the blockchain, the workflow
In May 2010, Ram appeared in a video interview as Deutsche Bank’s global head of eCommerce distribution. The subject was integration: connecting voice and electronic services, analytics, execution and the work after a trade. The larger goal was to fit financial products into clients’ own workflows. Even then, his brief extended beyond making the trading screen look busy.
He later held roles including global head of electronic trading and sales for capital markets and global head of product management for transaction banking. Those titles put him on different sides of the same transaction. Trading determines the bargain. Payments, custody and other services help make the bargain happen in the world outside the screen.
The breadth of that experience helps explain the project he eventually chose. Settlement draws together technology, legal rights, liquidity and operations. Improving one part can leave another part working just as hard. A new interface is pleasant; a familiar queue behind it is still a queue.
There is also a useful difference between a client workflow and a technology demonstration. A demonstration can show that a transfer is possible. A workflow has to accommodate the next transfer, the exception, the record, the obligation and the person responsible for putting things right. Ram’s banking career placed those details close to his work.
A coin with a committee behind it
Ram began leading the Utility Settlement Coin consortium in 2017. Fnality was its commercial successor in 2019. The undertaking came out of banks’ interest in using distributed ledgers to simplify the machinery around transactions. A shared transaction record had attractions. Paying through a separate, older system could preserve much of the work the new record was supposed to remove.
In his conversation with Citi’s Ryan Rugg, Ram set out the design requirements. Banks needed a settlement asset with the credit quality of central bank money. A payment needed legal finality. And the system needed to work with a world containing several blockchains. That last requirement was an early judgment about the shape of the market: institutions were unlikely to choose one network for everything.
His explanation begins with banks’ requirements rather than a favourite piece of software. The sequence matters. A network can record that something happened; a financial institution also needs to know what that event means for its obligations. A technical success and a completed payment have to describe the same event.
The practical work involved other companies too. In 2020, EPAM became a strategic partner for software development, helping deliver national payment systems and connections to blockchain networks and existing systems. Building Fnality meant combining a settlement design with the integration work needed for institutions to use it. There were rather more moving parts than the word “coin” suggested.
USC consortium
payments announced
A research project had become an operating payment system.
The account that made the idea usable
An important opening came in April 2021, when the Bank of England published its policy for omnibus accounts. A payment system operator could hold pooled participant funds at the central bank. Those funds could support settlement on the operator’s ledger. The policy supplied an account structure that connected new payment services to an established settlement asset.
Picture banks putting money into a shared account while retaining defined entitlements to it. The operator’s ledger records the balances used within its payment system. A payment updates who is entitled to the funds. The arrangement joins an accounting record, a legal framework and money held at the central bank.
On 14 December 2023, Fnality announced initial live sterling payments involving Lloyds Banking Group, Banco Santander and UBS. The initial phase operated under limits set by the Bank of England. Further scaling depended on meeting the Bank’s operational and supervisory expectations. For a founder who had been working on the consortium since 2017, it was a concrete change: the proposed system was making real payments.
The Bank of England’s 2023/24 RTGS and CHAPS report recorded Fnality as the first omnibus account holder, with the first payments made in December 2023. This was the sort of milestone that fits into an annual report. In financial infrastructure, that is a respectable place for a breakthrough to end up.
The model also has an operational condition. Under the Bank’s omnibus account policy, settlement can continue outside RTGS operating hours if sufficient liquidity has been placed in the account before CHAPS closes. Always available settlement still requires someone to think ahead about funding. Banking has an impressive talent for making even the future depend on a cut-off time.
An account, a record, a payment.
- 01Fund the accountParticipating banks place funds in the central bank omnibus account.
- 02Record the balancesThe payment system’s ledger tracks participants’ entitlements.
- 03Settle the paymentA ledger update changes the balances within the system.
Faster is only half the calculation
A payment system can become faster while its users still need a great deal of money ready to make payments. This is the complication behind the appealing picture of everything happening immediately. Speed, funding and the ability to reuse funds belong in the same calculation.
Ram addressed the tension in his September 2025 paper, The Emerging Architecture of Clearing and Settlement in Digital Finance. He argued that capital efficiency remains central. Netting, which offsets obligations so that a smaller amount needs to be paid, has an economic purpose. Requiring every transaction to be fully funded individually can sacrifice that benefit.
His proposed answer was a layered settlement orchestrator: an architecture for coordinating settlement, liquidity and risk rather than simply demanding that every payment happen faster. It is an instructive turn in his thinking. Someone who helped build real-time settlement was also examining the reasons an institution might want to combine it with other ways of managing obligations.
A second September paper, Deposit Tokens: The Banking Response to Stablecoins, considered how banks could use public blockchains themselves. Ram’s argument was that the platform supplied much of the innovation. Banks could bring deposit products, interest and their existing regulatory responsibilities to it. He also identified integration, compliance and capital treatment as hurdles. The argument gives the old institutions work to do, rather than a comfortable exemption from change.
The founder changes chairs
In December 2024, Fnality announced Michelle Neal as Ram’s successor. Neal came from the Federal Reserve Bank of New York, where she headed the Markets Group. The announcement said Ram would remain an advisor, working on product strategy, customer acquisition and regulatory engagement. The job changed; the subject of his work remained close to the system he had helped establish.
Fnality subsequently announced a $136 million Series C in September 2025. Its lead investors included WisdomTree, Bank of America, Citi, KBC Group, Temasek and Tradeweb. That was a company milestone under Neal’s leadership, with plans to extend the network to other major currencies. Ram’s current title places him alongside that next stage as founder and strategic advisor.
His connection to the Gillmore Centre for Financial Technology as an honorary research fellow gives him another place to pursue the underlying questions. The published papers are unusually concrete for someone discussing the future of finance: how ownership should be recorded, how an operator should be held accountable and how liquidity should be used.
There is a human register to the technical conversation too. At the start of his Citi interview, he tells Rugg, “just call me Rhom.” He has also brought other people’s experience into the company: at a Fnality Olympus Day, he hosted a leadership conversation with Lloyds’ Samantha Emery. The business of changing shared infrastructure includes listening to the institutions expected to use it.
Separate the vault from the record
In April 2026, Ram published A Two-Layer Architecture for Digital Assets. The proposal separates custody of the underlying asset from the ownership record. Regulated infrastructure holds the asset; shared blockchain infrastructure carries the record. A token operator connects the two. The distinction makes it possible to discuss what each layer is responsible for instead of asking whether everything should be “on-chain.”
The companion paper, Designing the Token Operator, follows that responsibility into the details. The operator handles asset control, identity, compliance, lifecycle management and coordination across chains. Ram proposes computing ownership records from public on-chain events so that they can be independently reconstructed. The legal record still has an accountable operator. Verification adds a discipline to that role.
These are architectural proposals, with consequences for governance as well as software. Someone must administer the asset. Someone must establish the holder’s rights. And a record must remain intelligible when institutions change or systems need recovery. A public ledger does useful work here, but it does not relieve an institution of its responsibilities.
By September 2026, his argument about interoperability brought the distinction back to the trade itself. A security changes ownership where its authoritative record lives. The cash payment becomes final in its own system. Coordinating those events can avoid creating another representation that must continually be reconciled with the original.
The vault and the record
The underlying asset remains under an institution’s administration.
Ownership events can be recorded and independently reconstructed.
It is the prisoner exchange again, with fewer journeys across the bridge. Ram’s career has followed the transaction from the trading workflow to the payment system and now to the ownership record. The question has become more precise with each move: what has to change for this bargain to be finished? There is room in finance for another fast screen. His attention keeps returning to the moment when everyone can stop checking.
“The record was the thing that needed to stop being copied”
Rhomaios Ram · September 2026