The first money lesson Ramit Sethi likes to tell begins with a scholarship check. He had done the industrious part already: applied for funding to pay for Stanford, won some, and received money that was supposed to help him study. Then he invested his first check in a stock. It lost half its value. The future personal-finance author had encountered a useful distinction. Being resourceful enough to get money did not mean he understood what to do with it.
That failure sits at the start of a career built around systems, but it is also a clue to why Sethi remains interested in people. His books and courses can tell a reader how to automate an investment. They cannot, by themselves, explain why someone with ample savings feels guilty buying dinner, or why two people sharing a home have opposite definitions of a sensible purchase. The numbers are visible. The rules behind them are usually inherited, private and occasionally absurd.
Sethi grew up in the Sacramento area in a family where money was discussed through real choices. His father, he later recalled, negotiated for five days over a car and walked away when the dealer would not include floor mats. The story is funny because the stakes shrink so suddenly. It is also a small domestic lesson in how a person learns to value leverage, principle and the pleasure of a good deal. Sethi would spend much of his working life asking whether those lessons still serve the people who carry them.
A system for getting in
His parents could not simply write a check for college. Sethi made a process out of the problem, applying for more than 60 scholarships. He has said that he funded his undergraduate and graduate studies that way; Fortune reported the awards totaled more than $200,000. When early applications failed, he videotaped himself practicing interviews and noticed that he was not smiling. He changed the performance. The lesson was not that charm beats substance. It was that even a daunting goal can be broken into parts, observed and improved.
At Stanford, he studied technology and psychology and wrote a comedy column. Those interests have stayed in his work. The technology student likes defaults, workflows and things that happen automatically. The psychology student notices the gulf between what people say they should do and what they will actually do on a Tuesday. The comedy writer, meanwhile, gave a personal-finance site a title no cautious committee would have approved: I Will Teach You to Be Rich.
The site began in 2004. Its brash name promised a result; its method was more deliberate. Sethi wrote about handling routine decisions once, negotiating larger ones, earning more and allowing money for pleasures that mattered to the reader. The original book followed in 2009, and a revised anniversary edition arrived in 2019. One of his most repeated instructions is to “spend extravagantly on the things you love, and cut costs mercilessly on the things you don’t.” It sounds tidy. Its actual demand is severe: a person must first know what they love.
The large question behind the small expense
Personal-finance advice often arrives as a list of minor prohibitions. Sethi is impatient with that habit. As he put it, “We’re obsessed with $3 questions, and we really should be asking $30,000 questions.” A coffee can be a habit; a home, a career move or an expensive fixed cost can determine the shape of a decade. He has also argued that renting deserves an honest comparison with buying, including the costs that do not appear in a mortgage payment. The point of the arithmetic is to give a choice its real size.
He does not present thrift as a personality. In his framework, a rich life is deliberately specific. It might include travel, meals with friends, time away from work or the ability to help family. His own examples include long trips with his wife, Cassandra. In 2026 he described a three-month sabbatical through Barcelona, Paris, Marrakech and Tokyo. A photograph from Tokyo accompanied a discussion of why the couple rents. The image made his argument more clearly than a generic checklist could: a housing choice has to be measured against the life it leaves room for.
“Spend extravagantly on the things you love, and cut costs mercilessly on the things you don’t.”Ramit Sethi
There is a catch in any maxim that begins with “you.” People change. Partners disagree. Someone may discover that a childhood rule about always saving was a useful guardrail at 22 and an unnecessary brake at 42. Sethi’s work grew as those complications became harder to ignore. He had begun by giving individuals a financial system. Over time, the most absorbing question became what happened when one system met another across a kitchen table.
Two people, one spreadsheet
The podcast that began under the I Will Teach You to Be Rich name now runs as Money for Couples. Its premise is unusually plain: people bring their actual numbers and their actual disagreements, and Sethi asks them to describe both. One person may monitor every transaction. Another may not know the household income. A couple can look prosperous on paper and still be unable to decide whether to pay for help, take a trip or reduce an expense that is swallowing their future. The most useful moment often arrives when a number turns into a sentence about fear, fairness or permission.
Sethi’s interviewing style is direct. He asks guests to be specific about income, fixed costs and what they want. Then he presses on vague claims such as “I’m bad with money” or “we’re fine.” This makes for uncomfortable listening at times, which is part of the format’s honesty. A published plan can be edited until it looks orderly. A conversation, especially between two people who have shared years of habits, resists that neatness.
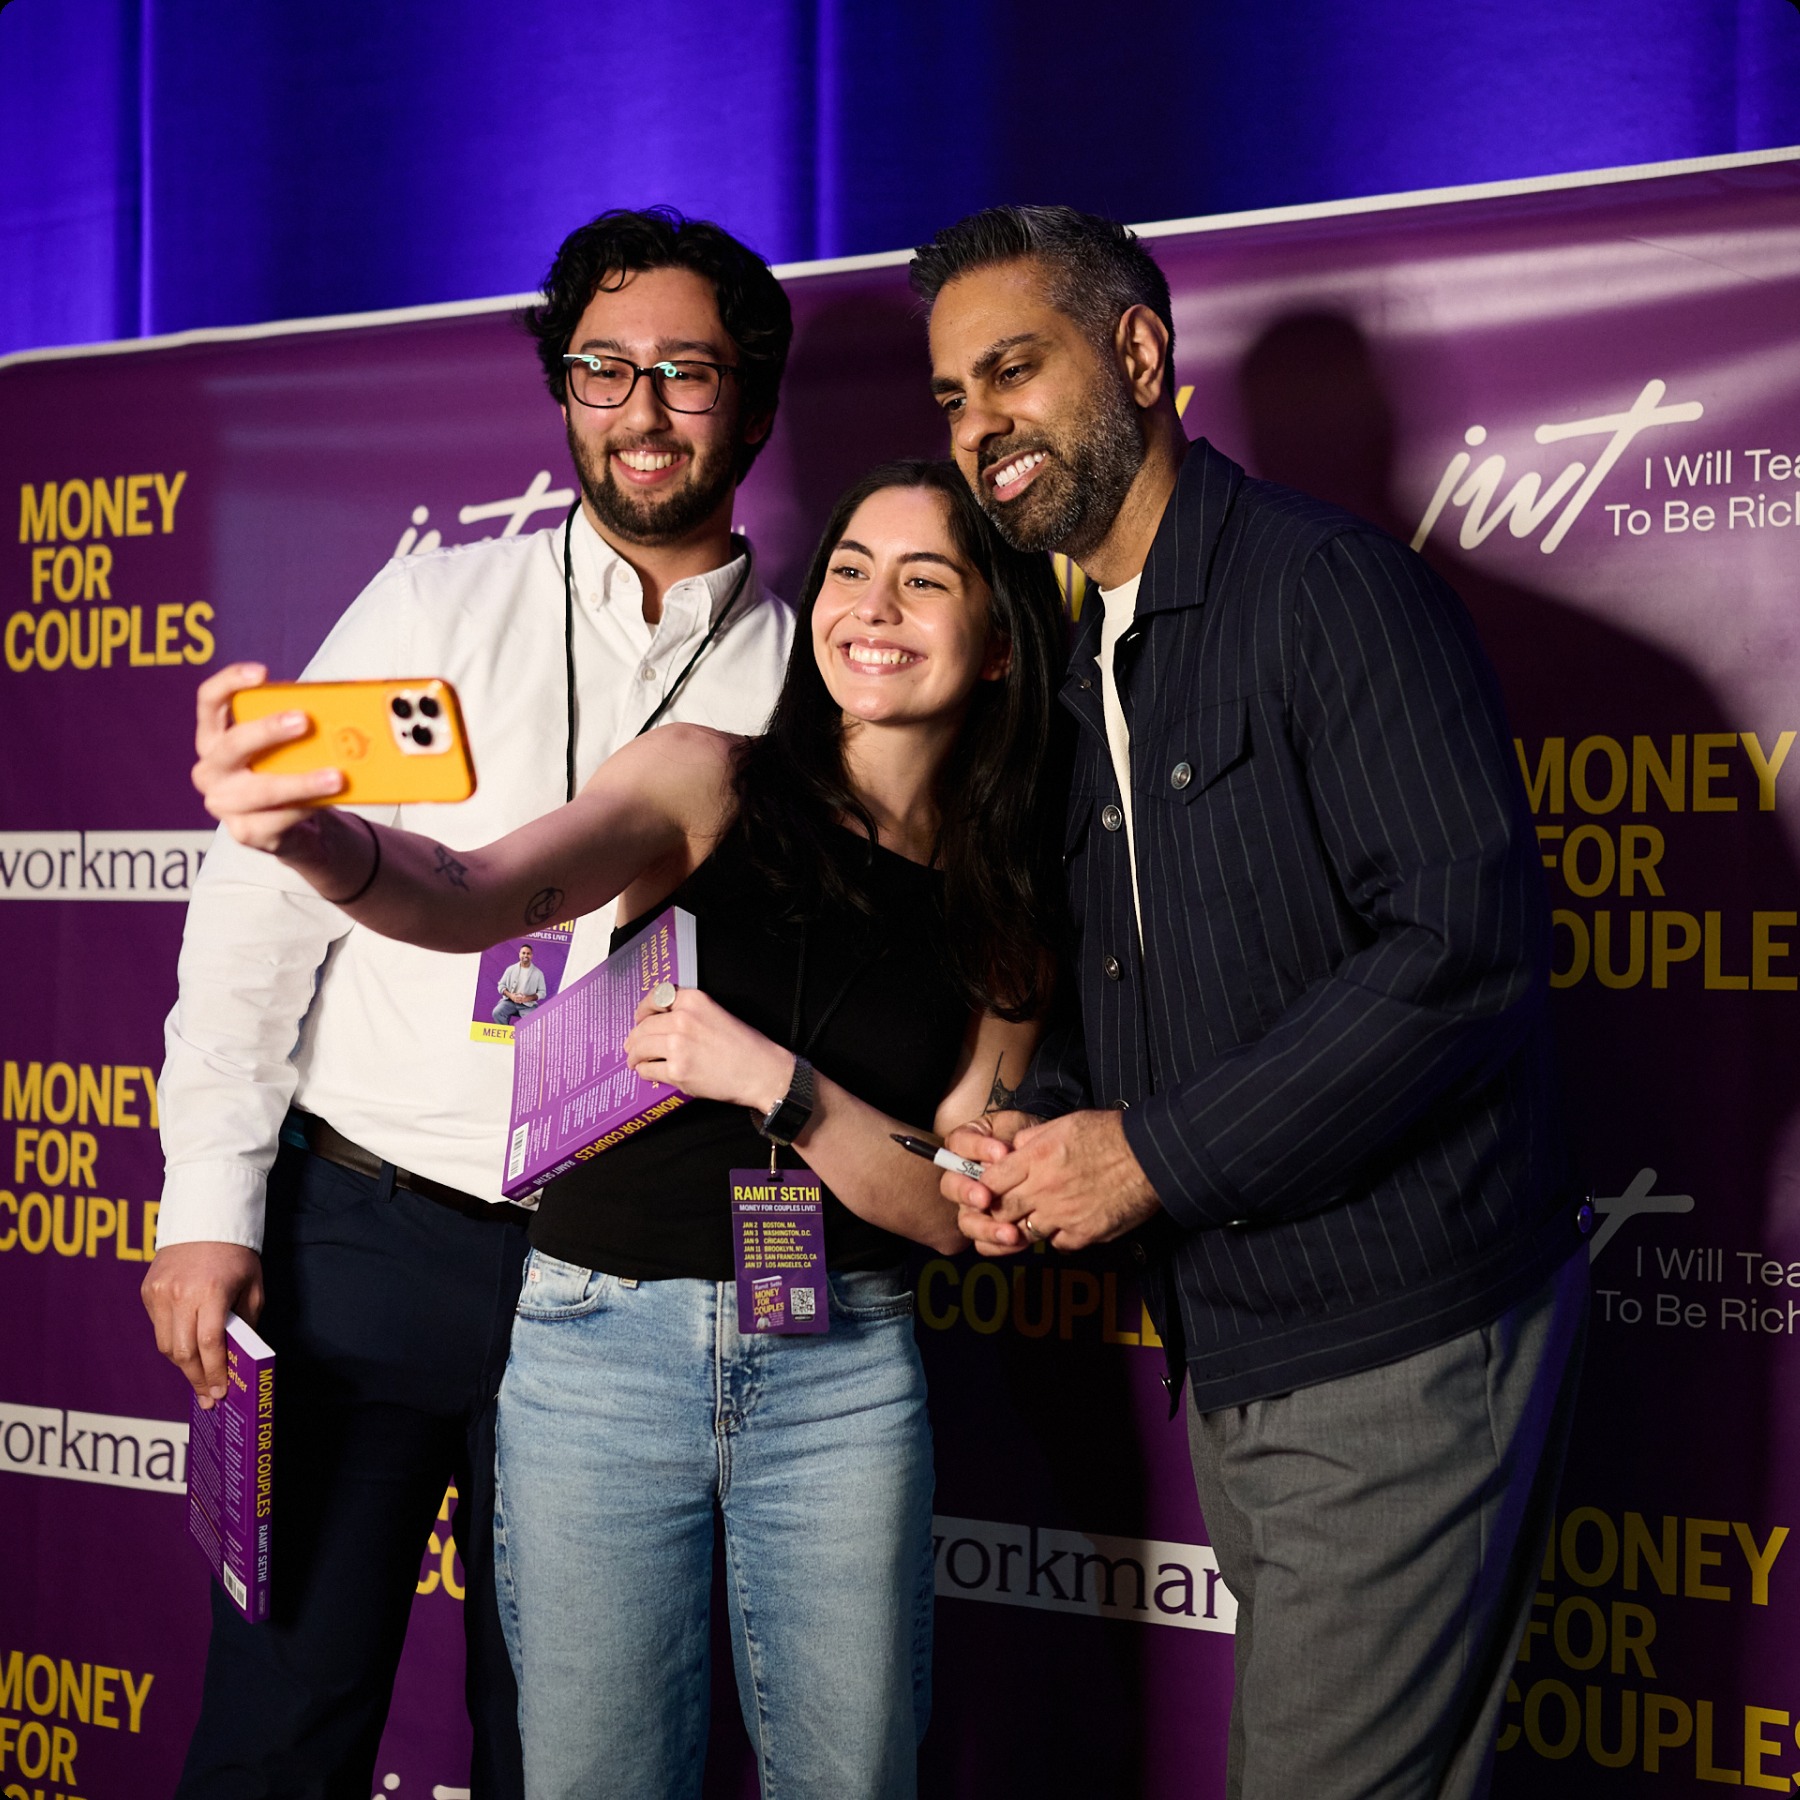
His 2024 book Money for Couples extends that work into a ten-step plan. The title itself acknowledges the difference between one person managing an account and two people deciding what an account is for. A partner who saves carefully may think they are protecting a shared future. The other may experience the same behavior as a refusal to enjoy the present. Sethi’s contribution is to make those competing stories speakable, then bring the discussion back to numbers and decisions.
The camera enters the room
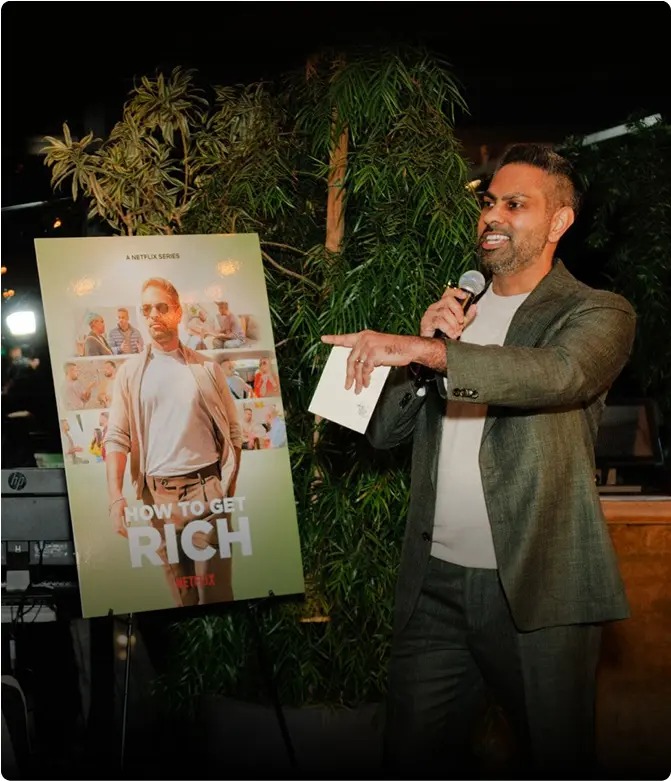
Television widened the audience. In Netflix’s eight-episode How to Get Rich, released in 2023, Sethi visited people around the United States and asked how their financial choices matched the lives they said they wanted. The title echoed the old website, but the scenes had more friction than a slogan. There were debts, housing arguments, wedding plans and the ordinary difficulty of telling another person the truth about money. Cameras made the private decisions visible, but visibility alone did not settle them.
That is one reason the podcast remains a natural home for him. It gives an argument time to unfold. He can stop at a surprising number, ask where a belief came from and wait while two guests hear each other answer. In a 2025 episode, Cassandra joined him on the other side of the interview, with a friend asking the questions. The finance host had to speak about his own marriage and money choices. It was a fitting reversal for someone who asks strangers to be candid in public.
The work also reveals a side of Sethi that his emphatic book title can obscure. He has written about being socially awkward when he was younger and deliberately learning how to talk with people. That admission helps explain the precision of his questions. The interviewer who can seem theatrical when he reacts to a spreadsheet is also trying to make jargon intelligible. He has recalled not knowing what a restaurant server meant by “protein” when he was younger, and used the memory to ask finance professionals for more patience with people who do not know their vocabulary.
A definition that keeps moving
Sethi’s public career now spans a website, courses, books, a television series and weekly conversations. The continuity is his belief that money should be intentional. The change is in where he looks for the intention. At first it lived in a system: accounts, transfers, negotiations. Now it often emerges through a story about family, a disagreement between partners or a purchase someone can afford but cannot quite allow themselves to make.
He is still capable of the crisp line. He still likes a plan. Yet his most durable question has no preset answer. What is a Rich Life? A spreadsheet can test whether the answer is affordable. It cannot choose the answer. That remains the work of the person holding the scholarship check, the couple at the kitchen table, or anyone who has saved for years and finally needs to say what the saving was for.