A packet of medicine has a surprisingly eventful working life. It passes through a packaging line, a warehouse, a distributor and, eventually, somebody’s hands. Each stage needs to know what it is handling. Behind that ordinary packet sits an extraordinary amount of coordination. This is the sort of business Parabellum Investments finds interesting: specialist technology that other businesses need to keep working.
- It buys control, primarily with its own capital.
- Its companies handle banking, pharmaceutical traceability and financial data.
- It backs operational improvements and complementary acquisitions.
- It has no prescribed exit timetable, but it does sell businesses.
Parabellum is the family office of Rami Cassis, founded in 2012. Its territory is the lower mid-market: operating companies with established capabilities and room to grow. Sellers can be founders, corporate groups disposing of non-core assets, or other investors. The pitch combines a buyer’s cheque with practical help running the company. A founder considering a sale is being offered a new working relationship as well as a transaction.
01 The engineer at the other end of the deal
Cassis began his career as an operating engineer at Schlumberger, where he spent ten years before moving through consulting and executive roles. At Atos, he ran the UK business-process and IT-outsourcing operation. His degrees are in aerospace engineering and mathematics. These are useful biographical details because they explain the question behind Parabellum’s proposition: once you own this thing, how will you make it work better?
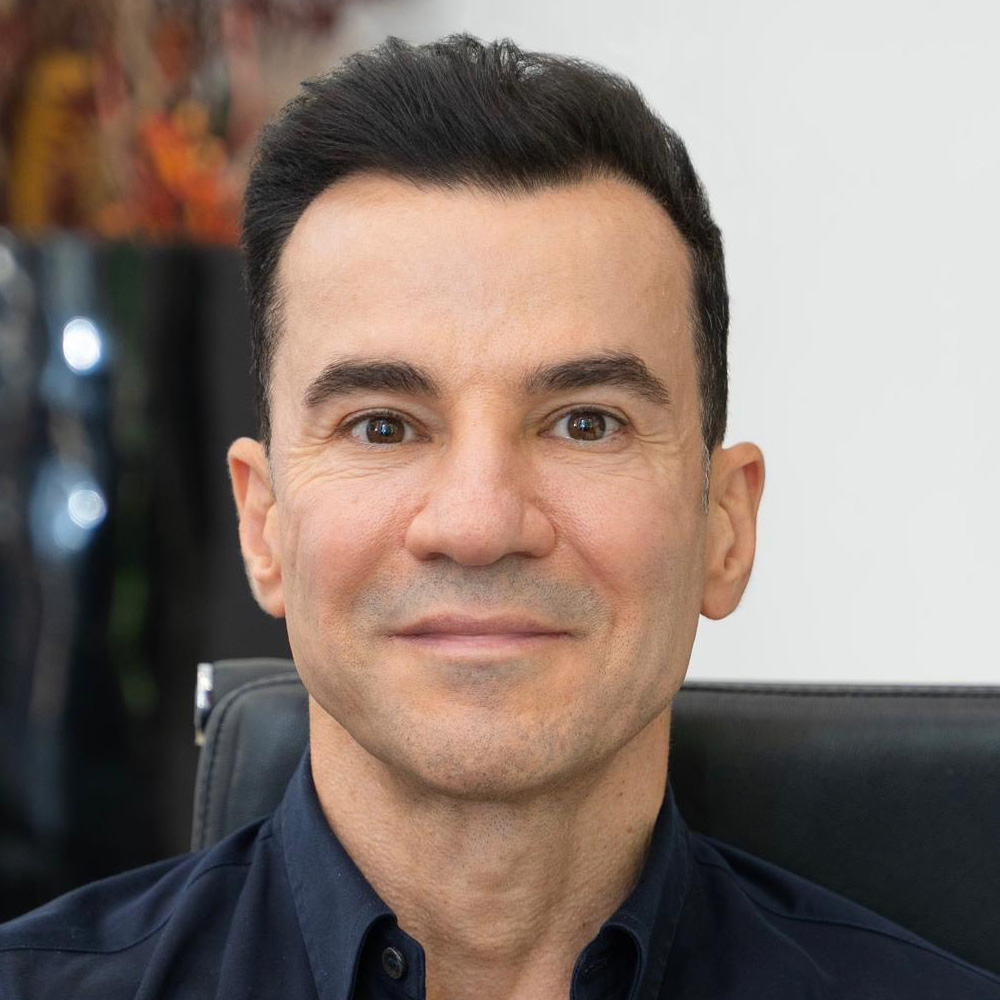
The firm says it mainly invests its own money and generally seeks full ownership or a controlling stake. Decisions therefore sit close to the person who will live with their consequences. Its team brings finance, legal, HR and commercial skills alongside operating experience. Management teams get support, but the owner also retains the ability to intervene. That arrangement depends on a willingness to work together after the lawyers have finished.
“The decision maker is the operator”
Parabellum Investments, describing its approach
One concrete example came in 2020. Parabellum partnered with Acacia to acquire technology-services provider The Column Group. Cassis became interim co-CEO alongside Acacia’s Gavin Long while a permanent appointment was planned. The acquisition involved a business with more than 400 employees and $90 million in 2019 revenue. Operational involvement, in that instance, included taking a management job.
02 Buy the missing piece
Consider advanco, the Brussels-based serialization company Parabellum acquired in April 2020. At the time, its ARC software was used in more than 35 countries, and its customers included Pfizer, Zentiva, UCB and Helsinn. The software helps manufacturers track medicine serial numbers. This is enterprise software with a very physical destination: the production line.
In June 2023, advanco acquired Vantage Consulting Group, a manufacturing-automation specialist. Vantage brought design, implementation and validation engineering. The logic is unusually easy to picture. A customer needs software to track products, and engineering to make the surrounding manufacturing process function. Combining those capabilities lets the supplier address more of the same customer’s problem. The announcement also identified North America as an expansion priority.
Something similar happened in banking. Parabellum’s ieDigital acquired US credit-union technology provider Connect FSS in 2023, followed by AI specialist ABAKA. In 2024, the three came together under the Fintilect brand. The ingredients covered digital banking, a US customer base and personalization technology. Their customers were financial institutions trying to improve the service consumers actually touch.
03 Patient does not mean permanent
The ownership story subsequently forked. Volaris announced its acquisition of Fintilect’s UK arm in October 2025. Its following year-end review said the US arm remained with Parabellum. An investment can grow by combining businesses, then change shape again. For anyone evaluating an investor, following those changes is more useful than admiring an undated collection of portfolio logos.
Parseq provides another example. In February 2026, Parabellum announced the business-services company’s sale to Paragon. The announcement said its back-office and payments operation had increased revenue from £11 million to £25 million over the preceding three years. Its earlier expansion included secure-print and payments specialist TALL and India-based Column Software Solutions. The sequence was acquisition, integration, growth, then a new owner.
Parabellum says it has no prescribed exit horizon. The distinction matters: freedom over timing still allows a sale when another owner makes sense. Its own-capital structure changes who controls the calendar. Conventional private equity funds and strategic corporate buyers remain alternatives for sellers; a specialist software acquirer such as Volaris can also become the eventual buyer of a portfolio operation.
04 The data has to get there first
In June 2026, Parabellum acquired Crux Informatics. Crux handles external data for financial and technology organizations. Its products include Sphere, a managed service, and ArrayX, an AI-driven ingestion platform. The work involves getting data into usable shape and keeping it flowing. A financial model is only useful when the information feeding it arrives reliably.
The acquisition announcement described connections to more than 200 data providers and thousands of production pipelines. Crux extends Parabellum’s interest in the infrastructure behind financial services. As with pharmaceutical tracking, the commercial appeal lies in a difficult recurring task that customers need someone to perform well.
05 A useful lesson for the seller
There is a practical idea here that travels beyond acquisitions. Identify a specific customer problem before choosing a growth project. Cassis’s public management advice emphasizes speaking to customers early and checking forecasts against the sales pipeline. A complementary purchase makes sense only if the combined business can deliver the promised capability.
For an owner seeking operational help and willing to sell control, Parabellum offers a recognizable proposition. A founder determined to retain control faces a basic mismatch. And patient capital still requires sound execution: engineering teams, software products and customer relationships have to work together. The interesting test begins after the deal, when the medicine packet, the banking customer and the financial data all resume their ordinary journeys.