A customer copying data from one software product into another is doing more than wasting an afternoon. They may be pointing out a merger. Don Butler, a managing director at Thomvest, described serving on two boards where customers were moving data between separate SaaS offerings. They wanted the products connected. In one case, two customers went further: why didn’t the companies simply combine? Eventually, they did. In venture capital, the conversation often starts with a founder’s vision. Here, a useful clue arrived in the customer’s unfinished work.
- Thomvest invests family capital across technology companies and a broader investment office.
- Its venture focus spans fintech, cybersecurity, and AI and data infrastructure.
- The practical offer combines investment with help on finance, hiring, strategy, and introductions.
A different clock on the wall
Peter J. Thomson founded Thomvest in 1996, driven by an interest in technology and its effect on everyday life. He supplies the firm’s capital and sets its investment direction. The name covers a group of investment companies acting for Thomson and his family. The venture business operates from San Francisco; a Toronto family investment office handles investments outside that portfolio.
That distinction explains a lot. A conventional venture partnership raises money from outside limited partners and works within a fund’s agreed life. Thomvest has been described as an evergreen investor. Family backing gives it a different capital relationship and potential flexibility over timing. The sensible interpretation is patient ownership, rather than a promise that every company gets unlimited time or money.
The Toronto operation also broadens the picture beyond startup investing. It invests in private equity funds and co-investments, public equities, credit, and real assets including infrastructure and farmland. A founder approaching Thomvest Ventures is entering one specialized part of a larger family investment enterprise.
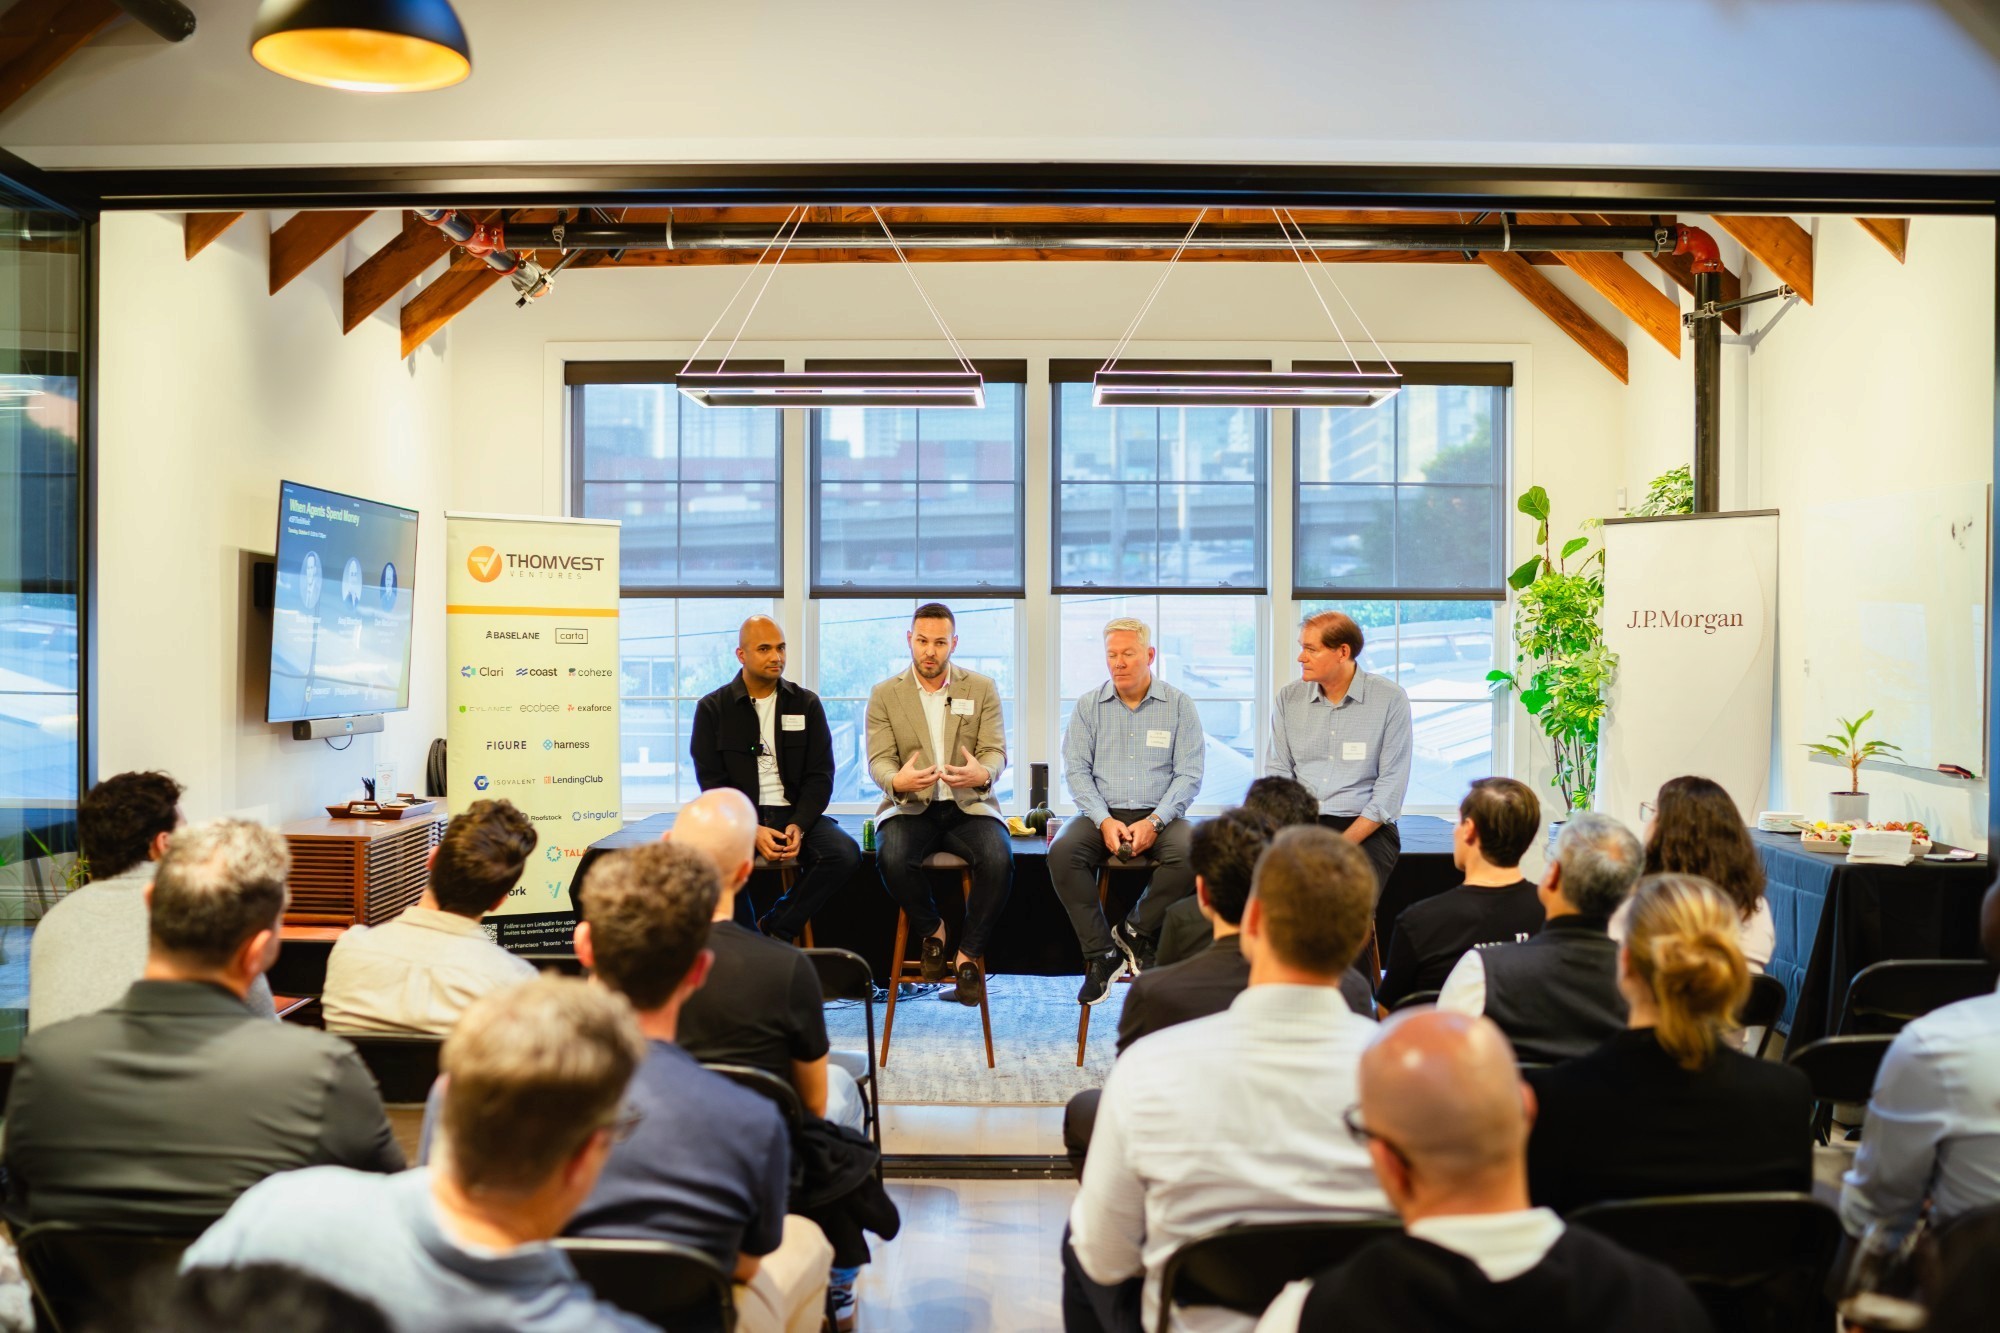
The check buys a working relationship
Thomvest’s counterparties are founders and management teams seeking capital and help building businesses. Its venture portfolio stretches across early and growth stages. Familiar names include SoFi, Carta, LendingClub, Cohere, and Harness. These companies are investments, rather than customers buying a Thomvest software subscription.
The business model is ownership: invest capital, help businesses develop, and seek returns as their value grows and investments are realized. Portfolio companies receive more than a place on a website. Thomvest says it assists with recruitment, partnerships, and expansion. Its team includes a portfolio finance associate working on financial models, performance tracking, and capital planning, alongside operating and strategic advisers with enterprise technology experience.
This is where sector knowledge can earn its keep. A financial technology founder may need an introduction to someone who understands credit risk. A security startup may need help translating technical capability into a sales process. The value depends on whether the investor’s experience matches the company’s next difficult decision. Founders have alternatives: specialist funds, larger venture partnerships, and other family investors. Some will overlap with Thomvest as co-investors. Choosing among them means checking who will attend board meetings, make introductions, and answer questions when a plan misses its targets. A familiar portfolio name is a starting point for that diligence. Speaking with the people who built those businesses is a better way to learn how an investor behaves.
“Then we go look for the right team.”Don Butler, on Thomvest’s research process
A fund is not a sales figure
In January 2024, Thomvest announced a new $250 million fund, bringing reported venture assets under management to $750 million. It also promoted Umesh Padval and Nima Wedlake to managing directors. The announcement described a sector-specific, stage-agnostic strategy and more than 75 investments made by that point.
Those dollar amounts deserve careful reading. The $250 million was investment capital for a fund. The $750 million measured assets under management. Neither number describes annual revenue. For founders, the economic exchange is company-specific: equity financing trades ownership for capital. The meaningful cost is dilution and the terms negotiated around that ownership.
First, find the thing that cannot keep up
The research habit is easier to see in a specific investment. In August 2026, operating partner Brad Brooks explained Thomvest’s participation in Lumilens’s Series C. His argument concerned the optical connections between processors in AI infrastructure. As computing clusters expand, moving information between chips becomes a problem of its own. Buying more computing power does not automatically solve the connections.
Brooks also described a relationship with Lumilens founder Ankur Singla dating to his Juniper Networks days. Thomvest already backed Singla’s cybersecurity company Exaforce. In April 2025, Exaforce announced a $75 million Series A involving Thomvest, Khosla Ventures, and Mayfield. That was the full financing round, rather than Thomvest’s individual check.
The investment logic combines a technical constraint with evidence about the people trying to remove it. That offers founders a useful clue about the pitch: explain which customer problem becomes more expensive as the market grows, then show why your team can fix it.
Even the research assistant needed editing
Thomvest’s experiments with AI inside the firm produced a smaller, revealing lesson. Butler described using Gemini in Google Sheets to summarize founder meetings. An instruction to summarize like a reporter made companies sound impressive even when they were behind plan. The experiment required iteration. The first failure was judgment in the summary: fluent language had softened the operating facts.
The same skepticism appears in the firm’s May 2026 research on venture lending. Its conversations with major lenders began with an expectation that AI would have changed loan documentation. The reported surprise was how little the headline terms had moved, even as lenders grappled with less predictable revenue. Evidence complicated the initial hypothesis. That willingness to revise the question matters more than producing a handsome market map.
Follow the customer’s extra steps
There is a version of Thomvest’s method that costs no venture fund to copy. Watch what customers do immediately before and after using your product. Find the spreadsheet, repeated upload, or manual handoff. Butler’s merger account suggests those adjacent tasks can reveal integration partners, acquisition candidates, and unmet demand. Start with the workflow before drawing the corporate organization chart.
There are limits. Combining businesses requires agreement on leadership, valuation, ownership, and governance. Patient capital cannot settle those arguments by itself. Nor does a sector specialist suit every founder: a company outside the investor’s expertise may gain more from another partner. The practical test is whether the people around the table can help with the work that is actually blocking progress. Sometimes that work is optical networking. Sometimes it is two products that customers are tired of connecting themselves.