The revealing detail in Navient’s retreat from student-loan servicing was a piece of software. When the company announced its agreement with MOHELA in May 2024, it said both businesses already used the same underlying servicing platform. No loan-system conversion was required. Nearly 900 employees were expected to change employers. Borrowers were told their account numbers and payment plans would stay the same. A company could surrender an enormous operational responsibility without asking customers to learn a new account number. The phone moved. The loan stayed.
- Hand off the servicing. MOHELA takes on the work; Navient retains portfolio ownership and oversight.
- Sell the sidelines. Healthcare went in 2024. Government services followed in 2025.
- Build around Earnest. New private education lending must support the next chapter.
For anyone who has confused a lender with the company answering a repayment question, this is a useful place to begin. Navient’s transformation depends on that distinction. Understanding it also explains why the familiar name can remain attached to debt after the familiar servicing operation has gone.
A company born carrying a suitcase
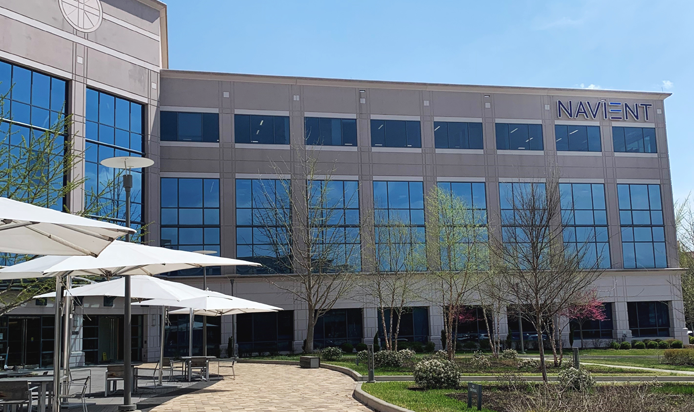
Navient arrived in public markets on May 1, 2014, already carrying nearly $300 billion in serviced student loans and 12 million customers. It had been separated from Sallie Mae. Jack Remondi was its first president and CEO. There was no tiny launch audience waiting to be persuaded; the audience arrived with the business.
That inheritance helps explain its place in finance. Navient has experience managing education debt over long periods, funding portfolios and handling credit risk. Its predecessor’s history reaches back to 1973. But longevity also comes with baggage: loans outlast branding campaigns, executive tenures and the systems originally built to administer them.
The trouble was in the choices
The question that damaged the servicing business was painfully ordinary: what happens when a borrower cannot pay? The Consumer Financial Protection Bureau alleged that Navient steered borrowers toward costly forbearance rather than affordable income-driven repayment. It also cited problems with payment processing and credit reporting. Operational decisions had consequences far beyond a call center.
The 2024 resolution required $100 million in consumer redress and a $20 million penalty. It prohibited federal Direct Loan servicing and restricted other federal-loan activities, while allowing a master-servicer role for Navient’s existing FFELP portfolio. Navient settled without admitting wrongdoing. Its Department of Education servicing contract had already ended in 2021. The sequence matters: the exit was underway before this settlement.
How to dismantle an overhead bill
Management’s stated reason for the wider overhaul came from a board-supervised business review announced in January 2024: simplify, reduce expenses and improve flexibility. There was an economic problem underneath. As old loans are repaid, the portfolio shrinks. An internal servicing operation can leave a company paying for capacity it needs less each year.
Outsourcing offered a way to make servicing expenses move with the remaining work. Divestitures went further. Navient sold Xtend Healthcare to CorroHealth in September 2024. The government-services sale to a Gallant Capital affiliate closed in February 2025, with approximately 1,200 employees transferring. Hospital revenue-cycle work and government processing ceased to be Navient’s growth pitch.
Subtraction had costs. Reported restructuring and other reorganization expenses were $39 million in 2024 and $17 million in 2025, primarily tied to severance. Those figures are separate from the CFPB payment. A smaller organization does not emerge simply because a slide presentation says it should.
Earnest has to earn its keep
The growth business has a different name. Navient announced its agreement to buy Earnest in 2017 at a $155 million cash price. Earnest now supplies private in-school student loans and refinancing. Its customers include students and families financing education, and graduates seeking to replace existing debt with a new private loan.
For borrowers, the potential utility is straightforward: a different rate, repayment term or monthly payment. Earnest’s refinancing help center says it charges no application, origination, late or prepayment fees. Its explanation of the economics is refreshingly direct:
“Our business is built on interest payments, not hidden fees.”
Earnest · Refinancing help center
The tradeoff deserves equal space. Earnest says refinancing federal loans permanently removes their associated federal benefits, including applicable income-driven repayment and forgiveness options. A longer term can also lower the monthly bill while increasing total interest. A smaller payment alone cannot tell a borrower whether the replacement is better.
SoFi and College Ave offer competing private refinancing products. Navient’s particular combination is a consumer lending brand backed by an established portfolio-management business. That combination provides capabilities; it does not guarantee the best offer for every applicant.
More loans. A narrower margin.
In the second quarter of 2026, Navient originated $815 million in private education loans, up 63% from a year earlier. Refinancing contributed $735 million; in-school loans contributed $80 million. The headline suggests acceleration. The accompanying numbers make the story more interesting.
Consumer Lending segment net income was $27 million, versus $26 million a year earlier. Navient explained that refinancing loans carry lower margins than its non-refinance portfolio, alongside lower expected credit losses. More volume changes the mix. It does not translate dollar for dollar into more earnings.
Money itself is another input with a price. In June 2026, Navient announced a $500 million unsecured notes offering carrying a 9.375% coupon. It also finances assets through securitizations. The business has to manage the gap between what loans earn and what funding, losses and operations consume.
The useful part of the experiment
For an operator, the transferable idea is cost discipline around a declining workload. Before copying the outsourcing, notice the compatible technology and employee transfers that made this handoff practical. A vendor arrangement still needs oversight. It cannot rescue bad underwriting or make expensive capital cheap.
For a borrower, the lesson is more personal: identify who owns the loan, who services it, and which protections survive a change. Those questions are useful precisely because the answers can differ. Navient’s next chapter will be judged in both places: the economics of the portfolio and the experience of the person making the payment.
Follow the next chapter
The 2014 video describes the company at launch.