The missing page is a surprisingly useful place to begin. In a mortgage trade, a buyer can want the loan, a seller can accept the price, and the transaction can still wait for a document. Somewhere between agreement and completion, somebody must discover what is missing, find it, and get it to the right person. The price is settled. The work is not.
- mTrade connects the people, documents and data behind residential whole-loan trades.
- Its software covers acquisition, portfolio monitoring and eventual sale.
- One documented customer improvement: missing collateral documents fell from 17% to 7%.
That last number comes from Fitch’s September 2023 review of a J.P. Morgan mortgage securitization. J.P. Morgan Mortgage Acquisition Corp. worked with mTrade to introduce an additional critical-document check. Missing documentation declined by ten percentage points. It is a specific result from a particular workflow, useful precisely because it describes something smaller and more credible than a promise to transform finance.
When the clock becomes part of the price
mTrade’s central argument is that a trade’s economics include its waiting time. Its website asks sellers to consider settlement alongside the headline bid: another day can mean another day of hedging expense, while earlier ownership can change interest earned. The details depend on the transaction. The operational question remains wonderfully plain: what is one day worth?
The company builds the plumbing around that question. Its mT360 platform joins buyers, sellers, loan records, analytics and outside vendors. A whole loan is the mortgage itself, traded as an asset; mTrade works on the institutional process around that asset. For a lender selling loans or an investor acquiring them, the attraction is knowing where the file stands without reconstructing the answer from separate conversations.
“Every Day Matters”mTrade’s company mantra
Two founders, one familiar problem
This was an experienced team returning to familiar territory. Bill Rayburn had taught finance at the University of Mississippi before co-founding mortgage technology company FNC. Lois Lovelady led FNC’s sales and marketing after earlier work in payments and at Wall Street firms. At mTrade, Rayburn became CEO; Lovelady became president and chief revenue officer.
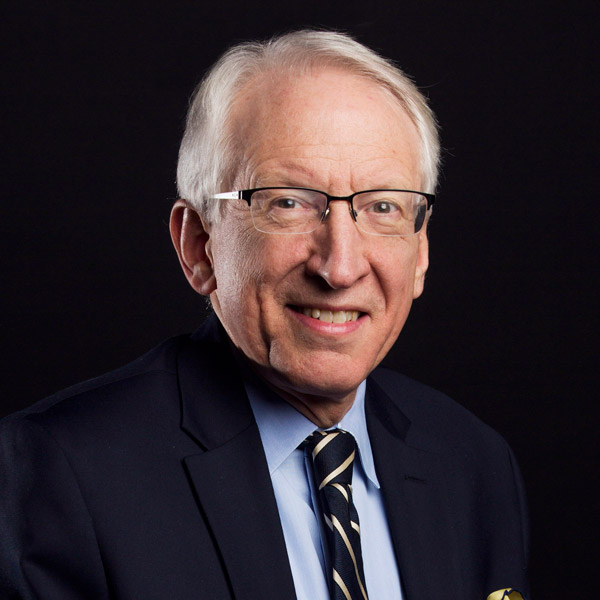
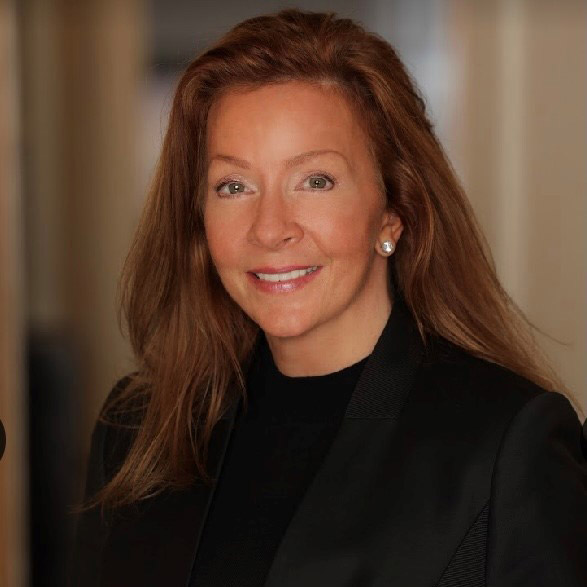
mTrade began as an incubated project inside FNC. According to the Ole Miss Alumni Association’s account, the co-founders bought its assets at the time of FNC’s 2016 sale to CoreLogic. That origin helps explain the focus: mortgage transactions were already their working material. The opportunity was to carry an existing project into a business devoted to moving loans through the secondary market.
Three jobs, one record
The product becomes easier to understand when followed in the order of a loan’s life. First comes acquisition. Sellers send “tapes,” the industry’s term for files of loan-level information. Those files arrive in different formats. mTrade’s acquisition system parses them into a standard format, giving the buyer data it can use downstream. Standardization is the small, necessary task before coordination gets easier.
- 01AcquireStandardize seller data
- 02MonitorRead servicer updates
- 03SellPrepare pools and files
Then comes surveillance: keeping track of the portfolio after purchase. The system ingests servicer tapes, identifies gaps and organizes payment histories, escrow information, comments and transaction records. Finally comes disposition. Loans can be sorted into pools using the owner’s criteria, with bid information and documents presented to prospective and successful buyers. Knowing which documents are absent matters again when the asset leaves.
Two other products address adjacent chores. RateLocker manages pricing and product eligibility, including configurable lock-desk operations and best-efforts or mandatory pricing. Life of Loan Warehouse retains documents and data for later retrieval, including audit inquiries. Business intelligence adds performance measures and counterparty scorecards. Together, the tools make the transaction’s working record useful beyond its first purchase.
The people between the systems
Connectivity also requires the other companies in the transaction to participate. In February 2018, due-diligence provider Recovco announced its integration with mTrade’s Clean Room acquisition system. The announcement described electronic bulk-file delivery and real-time exchange of loan status and findings. Its promise of shorter acquisition times was a partner’s forecast, rather than a measured result. The mechanism was concrete: fewer separate steps to move the same information.
mTrade sells proprietary institutional software alongside client service. Prospective customers discuss their requirements with the company. Each account receives a designated team familiar with its operation. “We work very much like a division of your company,” its service page says. That is a revealing product detail: the software has to function across organizational boundaries, where someone still needs to answer an operational question.
In the wider market, MAXEX offers another approach to residential loan trading, organized around a centralized exchange and clearinghouse. mTrade’s public offering emphasizes connected acquisition, surveillance and disposition workflows. For a buyer comparing options, the useful distinction is the job required: access to exchange liquidity, coordination of an existing trading network, or some combination of both.
Speed has responsibilities
Keeping records together also concentrates responsibility. Massachusetts’ 2026 breach register lists an August 21 notification from Mortgage Trade Holding Co., LLC doing business as mTrade, involving 16 Massachusetts residents. That state figure is not a national total. It belongs alongside the efficiency story: the records that make a trade possible contain information that needs protection.
The lesson another operator can borrow is modest and practical. Map the handoffs. Standardize what arrives. Check completeness before passing it onward. Measure the waiting between steps. This is an inference from mTrade’s approach, not a guarantee of savings. It requires usable inputs and willing counterparties; faster document movement cannot make a weak loan creditworthy. But it can expose the missing page while there is still time to do something about it.