The letter is an unlikely place to look for a technology business. Yet in 2021, New American Funding selected Covius Document Solutions for a particularly consequential kind of correspondence: pre-foreclosure and breach letters. The assignment involved a library of templates covering all 50 states and printing on demand. Before a letter reaches a kitchen table, somebody has to make its words, timing and delivery work together. Covius sells that coordination.
- Customers buy credit checks, title work, documents, loan reviews and workflow software.
- Acquisitions have extended the business across a mortgage’s entire life.
- The practical lesson: make each handoff visible before trying to make it faster.
That opening example explains more than a catalogue of products could. Covius occupies the space between a financial decision and its execution. A lender wants to close. A servicer needs to communicate. An investor wants confidence in a loan file. Each intention creates work that must survive a journey through people, systems and rules.
The mortgage has a backstage
For a borrower, a mortgage can feel like one purchase followed by years of payments. Inside the industry, it breaks into smaller assignments: obtain a credit report, verify income, establish ownership, prepare documents, record changes, review collateral. Covius supplies services and technology for those assignments. Its buyers include lenders, banks, credit unions, servicers and capital-markets participants. Vehicle servicers also use its compliance and borrower-communication offerings.
The product names describe different parts of this machinery. Funding Suite handles credit reporting and related tools, with dashboards showing purchasing costs and open orders. DocData covers imaging, indexing and data extraction. Nationwide Title Clearing handles work such as lien releases and mortgage assignments. Clayton reviews residential and commercial loans and monitors servicing. RealtyBid provides auctions and disposition services for properties, including bank-owned real estate.
Illustrative service map; individual loans take different paths.
A new name, then a shopping list
The current business emerged from a change in direction. Rick Seehausen co-founded predecessor LenderLive Holdings in 1999. In 2018, the parent adopted the Covius name while preparing to sell its private-label mortgage-fulfillment division. Covius had already been the name of its SaaS development platform. The company borrowed its software identity for a broader services business.
Chairman and CEO Rob Clements explained the timing: “With the pending sale of our Network Division, we chose a new brand.” What followed makes the choice legible. In 2019 came selected Chronos credit, verification, REO and auction businesses. Clayton’s due-diligence and surveillance operations arrived in 2020. Nationwide Title Clearing followed in 2021.
Money helped assemble that collection. New Residential’s SEC filing records a $27.3 million common-stock investment in May 2019, alongside a $35 million four-year subordinated debt facility. Those are different instruments: ownership capital and borrowed money. Treating them as one venture round would obscure how this expansion was financed.
Buy the connections, too
Title365 added another piece. Covius announced an agreement to acquire it from Blend in June 2025; by August 2026, it reported the acquired operations fully integrated into Covius Settlement Services. The original announcement described a title business licensed in 43 states, with existing links into lending platforms and customers spanning first mortgages, home equity and default.
The attraction was partly reach. Covius’s existing loss-mitigation and default-title work would sit beside a stronger origination operation. It was also connectivity. In the integration announcement, executive Joe Chappell described access to digitally integrated services “all under a single MSA.” A master services agreement sounds dry. For a buyer coordinating vendors, fewer contracting and connection chores can be a concrete benefit.
A lender buys a finished task. Covius’s strategic bet is that the connections between tasks are worth owning, too.
This is its competitive position: a collection of specialist operations tied to technology. A customer can instead hire separate title, document and loan-review providers, or perform work internally. Covius argues for breadth and integration. Its business combines outsourced services with managed applications; the relevant unit of value may be a completed document, a reviewed file or an operating workflow.
For a potential customer, that breadth creates a practical buying question: which part of the process needs outside help? A credit-reporting order and a custom workflow application solve different problems. The sensible comparison starts with the task, the systems it must connect to and the evidence needed when something goes wrong. A long service catalogue becomes useful only when those requirements are clear.
The spreadsheet reaches its limit
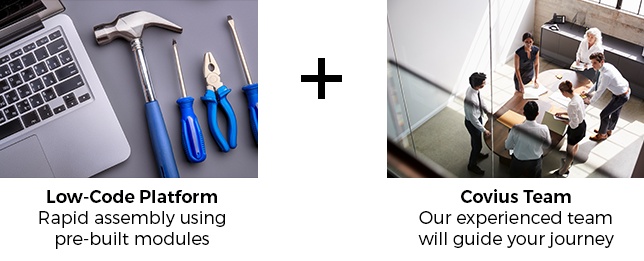
Convergence makes the software argument explicit. Covius assembles custom applications from reusable low-code modules, then manages the platform. The toolkit includes interfaces, workflow, document storage, reporting and integrations. It addresses a familiar predicament: a process assembled from email and spreadsheets becomes harder to supervise as volume grows.
Its technology site describes an unnamed loan-review client whose process required several people to monitor progress. After implementation, the company reports underwriting time fell 30%, with a portal showing clients current status. Another unnamed client moved from phone-and-email orders to a web portal, reducing processing from days to hours. These are company-reported examples, rather than independently measured averages.
Underwriting time, indexed. One unnamed client; Covius-reported result. Actual hours not stated.
Even the fixer-upper gets a data layer
RealtyBid offers a different illustration of the same impulse. A 2025 FoxyAI partnership adds condition analysis from property photographs and condition-adjusted valuations. Weiss Analytics supplies valuation information and local comparables; Blue Book International contributes repair-cost inputs for renovation-return estimates. The ambition is to give bidders more information about the house they might buy and improve. Estimates still depend on the evidence fed into them.
There is also a distinction between moving information and resolving it. A portal can show where a file sits; it cannot, by itself, settle a disputed ownership record or decide what an unusual document means. Covius’s combination of specialist services and software makes sense in that gap. Automation handles the repeated route, while the underlying expertise matters when a file takes a detour.
The transferable idea is modest and useful: expose the queue, define who handles an exception, then automate the repeatable work. That is an inference from Covius’s examples, not a universal recipe. Poor data, missing integrations or unresolved title problems can still require human attention. The mortgage’s backstage remains crowded. Covius’s opportunity is to help the people there pass the file along with fewer surprises.