A monthly transfer can tell two stories. In one, money leaves a bank account in New York and arrives with a relative in Lagos. In the other, a lender in New York sees no evidence that the sender has reliably made that payment for years. The first story has a receipt. The second has a blank page. Kredete, a fintech founded by Adeola Adedewe, set out to make that blank page less empty.
- Kredete combines cross-border transfers with opt-in reporting of eligible activity to U.S. credit bureaus.
- Its first product was an African lending marketplace. The company pivoted toward diaspora remittances in late 2023.
- Consumers get transfers, credit tools, accounts and cards; businesses get payments and account infrastructure.
- A $22 million Series A in 2025 and the 2026 acquisition of Gravv moved Kredete further into payment rails.
The 17th rejection
Adedewe told Afridigest that a premium bank declined him for a credit card 17 times after he moved to the United States. His work and education had travelled with him. His credit history had not. He knew the problem from both sides of the counter: before founding Kredete, he had worked at JPMorgan on cross-border payments. The experience made the immigrant’s predicament unusually legible to him. A person could be dependable with money and still arrive in a new country as an apparent financial stranger.

The original answer was a digital lending marketplace in Africa. It offered credit scores and brought borrowers and lenders together, using data and software to help with decisions. By Adedewe’s account, the first obstacle was less glamorous than a bad algorithm: identity and credit information sat in different systems, and banks and bureaus were slow to change. The marketplace attracted users, but building the underlying credit infrastructure would take longer than he had expected.
So Kredete changed its starting point. Instead of waiting for African credit records to become portable, it looked at a habit already visible in the United States: immigrants sending money home. In late 2023 the company shifted toward remittances paired with credit building. A transfer people were making anyway could become evidence in the country where they now lived. That is the useful lesson in the pivot: the customer’s repeated behavior was already there. Kredete’s job was to give it another use.
“If you support your family financially, that should count toward your creditworthiness.”Adeola Adedewe, Kredete founder and CEO
One payment, two destinations
For a consumer, the first half is familiar. The app lets users send money through supported corridors and see the exchange rate, fees and expected amount received before confirming. The recipient can be paid in local currency through available methods. Behind some transfers, Kredete says it uses dollar-linked stablecoins as a settlement tool with licensed payout partners. The person sending dollars and the family member receiving local currency do not need to manage a crypto wallet to make an ordinary remittance.
The second half requires a deliberate choice. Kredete says eligible rent payments and international transfers can be reported to major U.S. credit bureaus after a user opts in. Its credit feature requires a Social Security number, and the company’s terms say score improvements are not guaranteed. The distinction matters: a transaction is not a magic credit point. It is one more piece of account activity that may enter a credit file under the program’s rules.
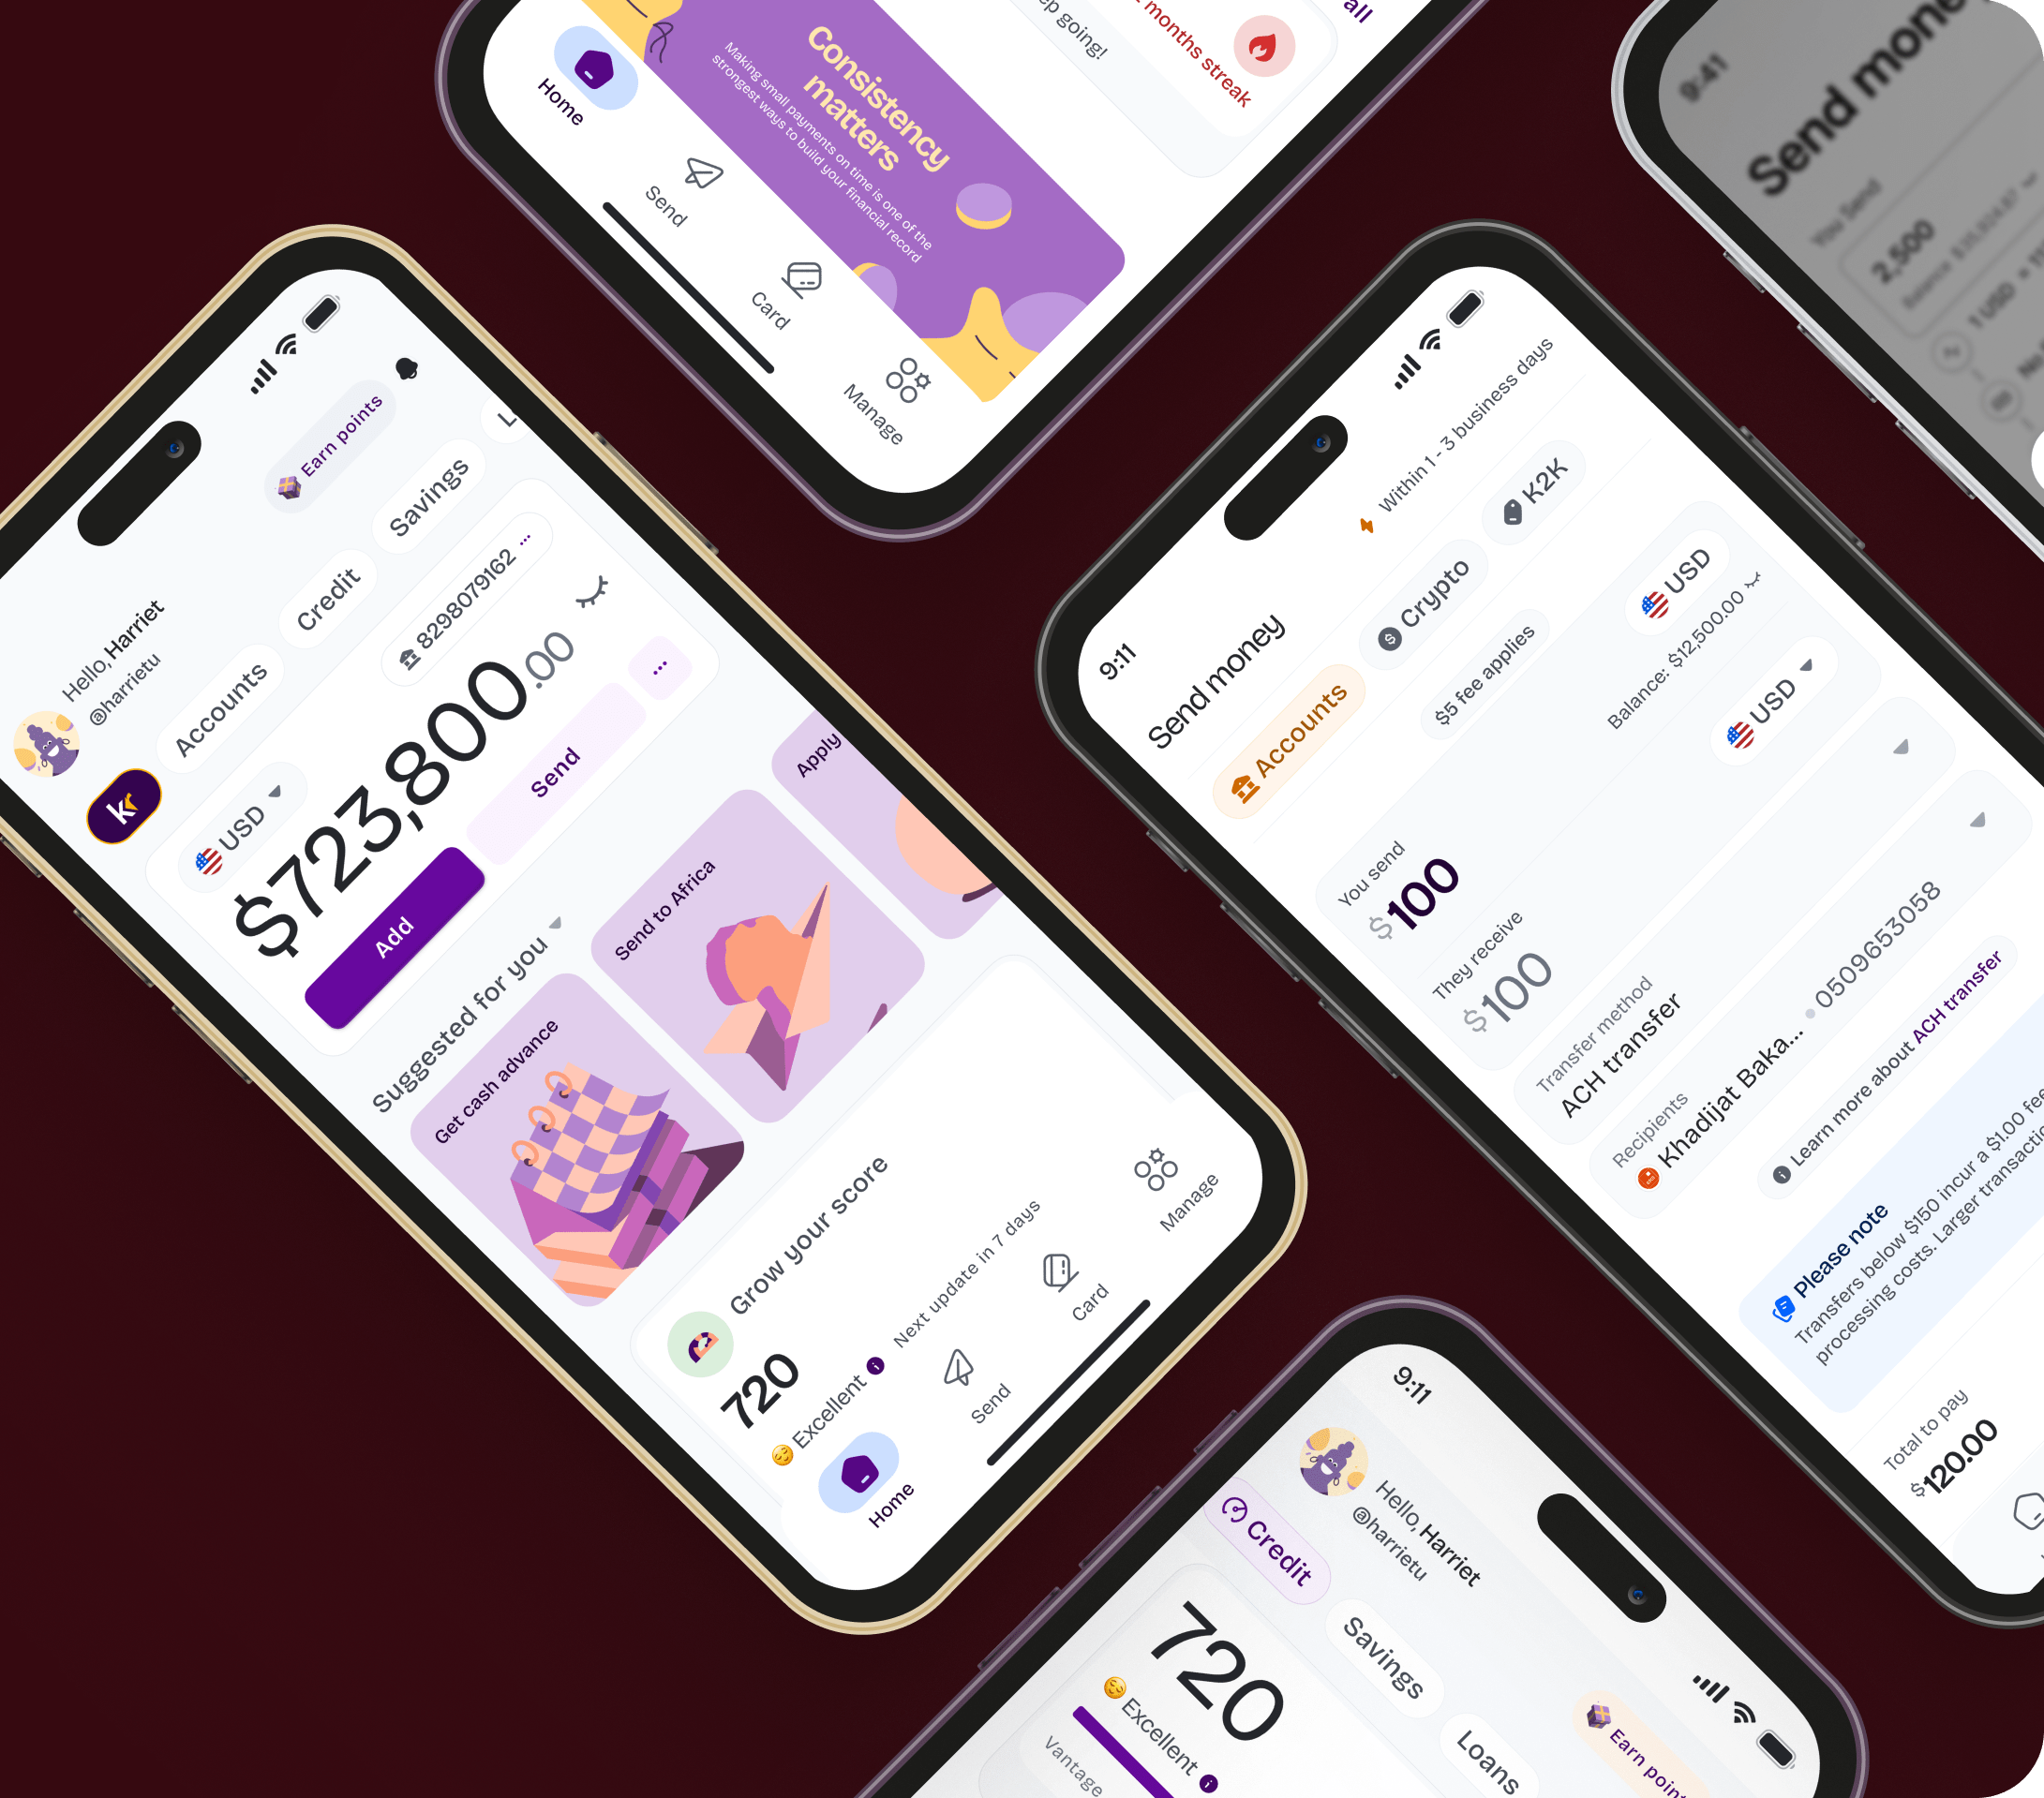
This is where Kredete differs from a conventional transfer service. Wise, Remitly, WorldRemit and Western Union all give a sender ways to move money. Kredete wants that transaction to stay useful after the transfer is complete. It now puts credit reports, rent reporting, savings features, accounts and cards beside the send button. A product image shows the idea plainly: a balance, a credit score and a transfer occupy the same screen. The illustrated balances are interface examples, not a typical customer’s finances.
The price of “free”
The economics are easier to understand once the headline fee is separated from the full transaction. Kredete’s current terms say the app discloses its fee, exchange rate and expected payout before a transfer is confirmed. Third-party institutions may add charges. The company also says any advertised mid-market rate or no-markup offer applies only to the stated transactions and conditions. For a reader comparing services, the number that matters is the amount the recipient actually gets for the sender’s total spend.
There is also a published subscription: Kredete+ costs $6 a month or $66 a year. The company advertises zero service fees on remittances for members, preferred exchange rates, a physical Visa card, waived account and card-funding charges, and more frequent credit reports. A frequent sender can calculate whether those benefits exceed the membership price. Someone who transfers once a year may reasonably arrive at a different answer. On the business side, Kredete sells payment and account capabilities to companies through its own platform and APIs; public pages do not supply a single price for every business integration.
The rails become the business
Kredete’s consumer story explains why someone might open the app. Its enterprise story explains why the company spent years on the plumbing. Its API documentation describes how a business retrieves supported currencies, checks recipient details, creates a recipient and initiates a payout. Kredete for Business offers multi-currency accounts, cards, vendor payments and invoicing. Banks, fintechs and platforms serving emerging markets are now customers or prospective customers alongside the diaspora sender.
The September 2025 Series A supplied $22 million, led by AfricInvest with Partech and Polymorphic Capital participating. Kredete said then that it had facilitated $500 million in cumulative remittances and reached 700,000 monthly users. Those are company-reported figures from that date, useful as a snapshot rather than a timeless scoreboard. By September 2026, its about page described more than six million people served and $15 billion in cumulative transfers. The measures and periods differ; growth claims deserve their labels.
The next move was an acquisition. In September 2026 Kredete announced that it had bought Gravv, which connects bank partners, blockchain networks and local payment rails. Kredete says this brings settlement, foreign exchange, liquidity, routing and reconciliation closer to its own products, while making the infrastructure available to other builders. The purchase price was not disclosed. Gravv’s own reported scale - more than $3 billion in annualized volume and over 1,000 business customers - is a different measure from Kredete’s cumulative transfers. Adding those figures together would produce a number without a sensible meaning.
The company has also launched a stablecoin-backed Visa card with Visa, Stellar and Rain and said in April 2026 that it was live across 50 African countries, with Gulf expansion planned. Banking and remittance services still depend on partner licensed institutions; Kredete says plainly that it is a fintech, not a bank. Availability varies by country and product. A card in one market, an eligible credit-reporting feature in another and an enterprise payout route in a third do not necessarily arrive as one universal bundle.
The useful part of the story
Adedewe’s first attempt tried to connect lenders and borrowers where credit information was patchy. The later attempt began with a payment that could already be verified. That shift made the proposition sharper: make a familiar act of support count twice, once for the person who receives the money and once for the person who sends it. It is a model others can study, but it depends on licensed payment partners, bureau reporting arrangements, usable identity data and customers willing to opt in. Remove those conditions and the tidy three-step diagram becomes a much harder business.
Kredete is now selling two things at once: a financial home for people whose lives span countries, and infrastructure for the institutions that move money between them. The modest insight beneath the complicated rails is still the best one. A person’s financial habits do not become less real when they cross a border. The difficult work is persuading the systems on both sides to see them.