Jorge Raull once found himself being asked to leave a conference where he was a registered guest. His offence was a missing badge. At a Miami hotel, he had left it in his room; an organiser, David Landsman, mistook him for someone who had wandered in without paying. Raull tried a joke. The joke did not immediately improve matters. Hugo Cuevas-Mohr intervened, and the misunderstanding became a running gag: at later meetings, Raull would make a point of displaying his credential. Eventually, Cuevas-Mohr made him a VIP badge.
It is a pleasingly small mishap in the career of someone whose business depended on getting things through the right doors. Raull founded TransNetwork, the payments business that became a foundation of Movantis. His working life crossed Mexico, Britain and the United States. The business connected financial institutions and retailers, letting other companies send money through a common network. The badge was optional only in his hotel room. In payments, the credentials had to travel with the transaction.
A banker learns both sides of the border
Raull came to the business with experience of institutions, rather than a consumer app. He studied industrial engineering at Universidad Iberoamericana in Mexico, completing a degree with a systems specialisation in December 1983. In January 1984, he joined Citibank’s corporate division in Mexico City. His subsequent MBA at the University of Texas at Austin, completed in May 1991, added a second country to his educational history.
From August 1991 to August 2000, he worked at Banco Nacional de México. His roles included business development in Houston and general management of the bank’s London and Houston agencies. Between 1995 and 2000, he was general manager in Houston. By the time he was building a payments company, borders were already part of his professional geography. He also spoke Spanish, English and German, an unusually practical collection of tools for a career spent between markets.
There is an engineering problem inside a payment network: separate systems have to cooperate reliably. Raull’s education and banking career sit comfortably beside that problem, although a résumé cannot tell us the moment an idea arrived. What his record does show is years inside corporate banking before the entrepreneurial chapter. He had worked where money was organised, accounted for and moved between institutions. TransNetwork would make those connections available to other businesses.
Universidad Iberoamericana
University of Texas at Austin
Houston agency manager
The shop counter belongs in the picture
A remittance has two ends. Someone sends money; someone else needs a usable way to receive it. TransNetwork’s place between those ends was a business serving businesses: connecting money-transfer companies with banks and retailers that could pay recipients. For the family collecting the transfer, the familiar name might be the shop or bank. Much of Raull’s company’s work happened behind that familiar counter.
In February 2017, when Nexxus Capital announced an agreement to invest in Translatum Holding, the holding company associated with TransNetwork, the network already reached 20,000 paying locations through 24 payers in eight countries. Those countries included Mexico, Guatemala, El Salvador, Nicaragua, Costa Rica, Colombia, Ecuador and Peru. The investment announcement described a common technology through which regulated financial institutions could connect. A relationship built once could give access to numerous places where money could actually be collected.
The distinction between a payment and a paying location sounds fussy until somebody needs one. A location makes a network tangible. It has opening hours, staff and a position in somebody’s daily journey. The company’s reach depended on those local relationships as well as on its central technology. Seen that way, the banks and retailers were part of the product. Their usefulness was measured at the receiving end.
More doors, and a seat at the table
The network continued to widen. A Nexxus portfolio report for the third quarter of 2021 described more than 58,000 payout points across nine Latin American countries. By Nexxus Day 2022, Raull’s speaker biography described more than 60,000 locations in 12 countries. These are snapshots taken at different dates, rather than a promise about every service available at every counter. Together they give a sense of the work accumulating behind the corporate name.
Raull also took a role in the industry’s collective affairs. In January 2018, the Money Services Business Association announced his election to its board, alongside WireCash co-founder Ran Grushkowsky and Pontual Money Transfer chief Fernando Fayzano. The association represented the non-bank money-services industry. Its concerns included relationships with banks and regulators, the conditions under which licensed providers operated, and the service their customers received.
For a founder connecting institutions across borders, such a seat put him among people wrestling with related practical questions. A payment business needs counterparties willing and able to work together. Its software lives within a much larger arrangement of permissions, commercial agreements and operating rules. Raull’s banking background and association work belong to that less visible part of the story. The transfer on a customer’s screen is the brief, public-facing moment of a longer institutional conversation.
There was work to do inside the network, too. Remesas y Pagos Cusca’s report for 2018, which listed Raull as its first manager, described an animated training video for people involved in paying remittances. It covered payment procedures, customer verification and the prevention of money laundering. The intended benefit was easier access to training and less time needed to complete it. That is a modest detail beside an acquisition, but a revealing one. A network depends on people understanding how to process the transaction in front of them. The local employee, the institutional partner and the central technology all have a part in making the payment usable. Training was one of the ways this subsidiary worked on that connection.
Buying a different set of possibilities
On May 15, 2024, TransNetwork announced its acquisition of Inswitch. Raull was identified as founder and CEO. The combination joined TransNetwork’s payment network with an embedded-finance platform: technology that companies could use to offer financial services within their own products. Ronald Alvarenga, Inswitch’s CEO, was the executive Raull named when looking ahead to the teams working together.
The planned offering extended beyond moving money between countries. It included digital wallets that could carry a client’s brand, domestic payments, and the issuance and processing of physical and digital cards. Those capabilities suggest a broader commercial ambition: helping a partner build more of the experience around the payment. A recipient’s relationship with the service could continue after the money arrived.
“fast, secure, and convenient digital payment solutions”
Jorge Raull, describing the goal of the Inswitch acquisition, May 2024
Raull’s phrasing was practical. Speed matters, but so do security and convenience; the three requirements have to coexist. The acquisition also brought a complementary opportunity for Inswitch, whose team could use TransNetwork’s infrastructure to expand its offering in the United States. Each side brought something the other could use. The appeal lay in the combination of an existing network and a wider set of financial tools.
Ten years, two yellow ribbons
Later in 2024, a photograph from Remesas Cusca’s tenth-anniversary coverage showed Raull beside Gustavo Ruiz. Each held a yellow strip carrying the Remesas Cusca name. Raull was identified as executive chairman of TransNetwork; Ruiz was CEO. The photograph captures a useful change in the story: the founder and the executive running the company, standing together at a business with its own local identity.
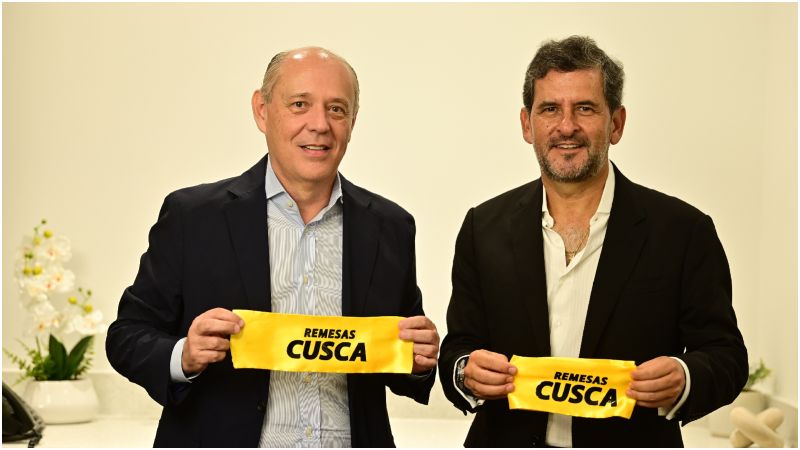
In El Salvador, Raull described the aim as extending access to remittances through more payout points and flexible hours and days. Recipients could use account deposits, cash and other channels offered by payment partners. The emphasis was on giving people workable choices. For all the language of platforms and processing, the customer’s question remained wonderfully concrete: where, when and how can I collect my money?
The local operation connected with financial institutions and retailers, as well as digital channels. The anniversary was therefore more than a date on a corporate calendar. It offered a view of Raull’s business at the scale where customers encountered it: one country, a network of partners, several ways to receive a transfer. His stated ambition there was access, expressed through the ordinary details of opening hours and collection methods.
A name that followed him
Raull died on May 20, 2025, aged 65. TransNetwork remembered him as its founder and executive chairman. Colleagues’ tributes brought the focus back to relationships. Erick Schneider recalled Raull taking time to advise him about growing his team at WorldRemit. Inswitch remembered the warmth he brought to the business. Those recollections give the institutional career a human scale: advice offered, trust extended, a conversation that stayed with someone.
In March 2026, Movantis emerged as the corporate brand bringing together infrastructure developed through TransNetwork and integrated businesses including Spectrum, Inswitch and Appriza. Gustavo Ruiz was named chairman and CEO of the entities under the brand. The timing matters. Movantis belongs to the continuation of the business Raull helped establish; its launch came after his lifetime.
Its stated proposition was a single integration across markets and financial capabilities. That formulation carries forward the logic visible in TransNetwork’s earlier network: make a complicated collection of local connections usable through a common system. The company’s name changed while the underlying task remained recognisable. For Raull, the record runs from corporate banking to payout networks to a wider range of financial services. For the people receiving money, the result still has to work at the other end.