Jeffrey Sprecher has a habit of taking things apart. As a child in Madison, Wisconsin, he investigated household gadgets in the family garage. A toaster oven came early; a Toyota came later. Eventually, the object requiring attention was the machinery by which people buy and sell things they may never actually see: electricity, oil contracts, financial risk.
There is an appealing mismatch between that garage education and his eventual purchase of the New York Stock Exchange. One involves screws. The other involves a building whose columns suggest that money has always known exactly what it is doing. Sprecher’s career has repeatedly depended on noticing where the machinery behind the columns could work differently.
He founded Intercontinental Exchange in 2000, after acquiring its struggling predecessor, Continental Power Exchange, in 1997. In November 2005, ICE listed its own shares on the NYSE. Eight years later, it bought the exchange’s parent. Becoming a customer, then a listed company, then the owner is a reasonably thorough way of getting to know a business.
California looked warmer
Sprecher graduated from the University of Wisconsin-Madison with a chemical engineering degree in 1978. He later earned an MBA at Pepperdine. His early working life was in industry, including Trane and Western Power Group, rather than in a brokerage house. At Western Power, he spent fourteen years in roles that included president, developing and financing power plants.
The route west had an ordinary human inducement. He remembered Wisconsin’s winter walks between his fraternity house and the engineering building. California offered a more inviting climate. The future exchange operator began with the sort of geographical calculation that requires no spreadsheet.
Power plants gave him a practical education in markets. A plant needs fuel. Its output needs buyers. Prices matter before construction and throughout operation. A better mechanism for finding those prices could be useful to someone making decisions about real equipment and real capital.
That background helps explain why his later enterprise began with an operational problem. He knew the customer’s side of the transaction. He had occupied it.
An exchange needs someone on the other side
Sprecher’s idea was to make energy prices accessible through an electronic marketplace. The early team included Chuck Vice and a small group of technologists. Building software occupied only part of their time. Sprecher and Vice also went looking for people who might use it, meeting more than a hundred companies during the first few years.
For an exchange, a beautifully engineered empty room is still an empty room. Buyers need sellers, sellers need buyers, and both need reasons to turn up. That problem makes the founding of ICE a story about persuasion as much as programming.
Its original shareholders included energy companies and financial institutions. The 2005 securities prospectus records names such as BP, Goldman Sachs, Morgan Stanley, Shell affiliates, Société Générale and Total affiliates. Ownership and commitments to send business to the platform helped bring participants into the same market.
There was engineering in the details, too. The platform incorporated credit limits, filters for counterparties and electronic confirmations. Those features addressed the decisions people actually faced before agreeing to a trade. Transparency had to survive contact with a working day.
Sprecher later put his starting point plainly: “I started the company because I wanted to become a customer.” That is an unusually useful explanation of a founder’s motivation. It identifies a job he wanted done and the person who wanted it done.
“I started the company because I wanted to become a customer.”Jeffrey Sprecher
The customer bought the building
The expansion came in stages. ICE acquired London’s International Petroleum Exchange in 2001, then the New York Board of Trade in 2007. Energy was followed by agricultural contracts and other financial markets. Each acquisition brought an existing community of users as well as a business to operate.
Then came NYSE Euronext. The transaction closed on November 13, 2013, with an approximately $11 billion value at completion. The company that had arrived on the NYSE as a listed stock in 2005 now owned its parent. For the cameras, the exchange supplied an instantly recognizable setting. Inside ICE, the purchase added a collection of markets and capabilities.
A detail from the negotiations restores the people to the deal. On the whiteboard in Sprecher’s Atlanta office, ICE and its target were represented by baseball shorthand: Braves and Yankees. His wife, Kelly Loeffler, had added a drawing of a cat hanging from a tree. Even a negotiation measured in billions can apparently benefit from office encouragement of the feline variety.
Sprecher and Loeffler married in 2004. Both came from the Midwest and made Atlanta home. She worked in ICE’s leadership, including investor relations, before her subsequent political career. Their shared appetite for work was part of their account of the relationship.
A place for people among the screens
Buying the NYSE posed a question that the earlier acquisitions had helped make unavoidable: what should happen to the humans on a trading floor when computers can match orders?
Sprecher’s answer has allowed for a combination. In a 2020 conversation, he described the NYSE’s electronic platform and human participation as complementary. He argued that the combination improved bid-offer spreads and the determination of closing prices. Those prices matter beyond the final trade of the afternoon because they feed indices and other financial products.
There is a revealing discipline in that position. Someone associated with moving markets onto screens could still see a role for people. An engineer can replace a component, retain it or give it a different job. The answer depends on the performance of the assembled system.
This is also where the tidy version of a technology founder’s story becomes less useful. A screen does not abolish the need for market rules, oversight or trust. It changes how those responsibilities are carried out. The exchange operator remains responsible for making the arrangement work when the participants disagree about what they want.
Prices have an afterlife
The purchase of Interactive Data Corporation in December 2015 carried an announced $5.2 billion price tag. It expanded ICE’s financial information business, adding pricing, analytics and trading-related services. The exchange company was becoming a business that supplied information as well as venues.
A trade produces a price, but the usefulness of information continues after the transaction. Financial firms need to value holdings, assess exposures and make decisions across markets. Data services put ICE into those recurring working routines.
The distinction matters when looking at Sprecher’s career. An acquisition list can resemble a collector’s inventory. The data business shows another logic: connecting activities that customers already need to perform. A market supplies transactions; surrounding services help customers interpret and manage what they own.
In his 2019 shareholder letter, Sprecher described fixed income and data as an expansion of ICE’s addressable market. The opportunity was broader than bringing another contract onto an exchange. It involved serving institutions through more of their daily work, including work that continues when trading is quiet.
The paperwork moves into view
Residential mortgages might seem a long journey from power trading. Follow the process rather than the product, and the connection becomes easier to see. A home loan involves people, records, approvals and repeated transfers of information. Delays at the connections are expensive to everyone waiting for the next step.
ICE built its mortgage position through investments and acquisitions including MERS, Simplifile and Ellie Mae. It completed the $11 billion Ellie Mae acquisition in September 2020. In his shareholder letter that year, Sprecher described linking the mortgage origination process with existing closing and post-closing networks.
Black Knight followed in September 2023. The announced value of the consideration at completion was approximately $11.9 billion. Its software and data extended ICE’s reach into mortgage lending and servicing. Sprecher’s stated aim was to apply the company’s digitization approach to the homeownership process.
For a borrower, the attraction of better connections is easy to understand. Nobody takes out a mortgage in order to develop a rewarding relationship with document handling. Sprecher had found another industry in which the less glamorous work was central to the experience.
There were also limits to how much could be assembled under one owner. The Federal Trade Commission challenged the Black Knight transaction over competition concerns. A settlement required the divestiture of Empower and Optimal Blue to Constellation, alongside other protections. The final consent order arrived in November 2023.
That episode belongs in the account of his achievements. A company can propose efficiency through integration while regulators worry about reduced choice. Both questions concern the customer. As ICE’s footprint expanded, Sprecher’s task included negotiating that tension, rather than simply acquiring the next piece of software.
The garage habit survives
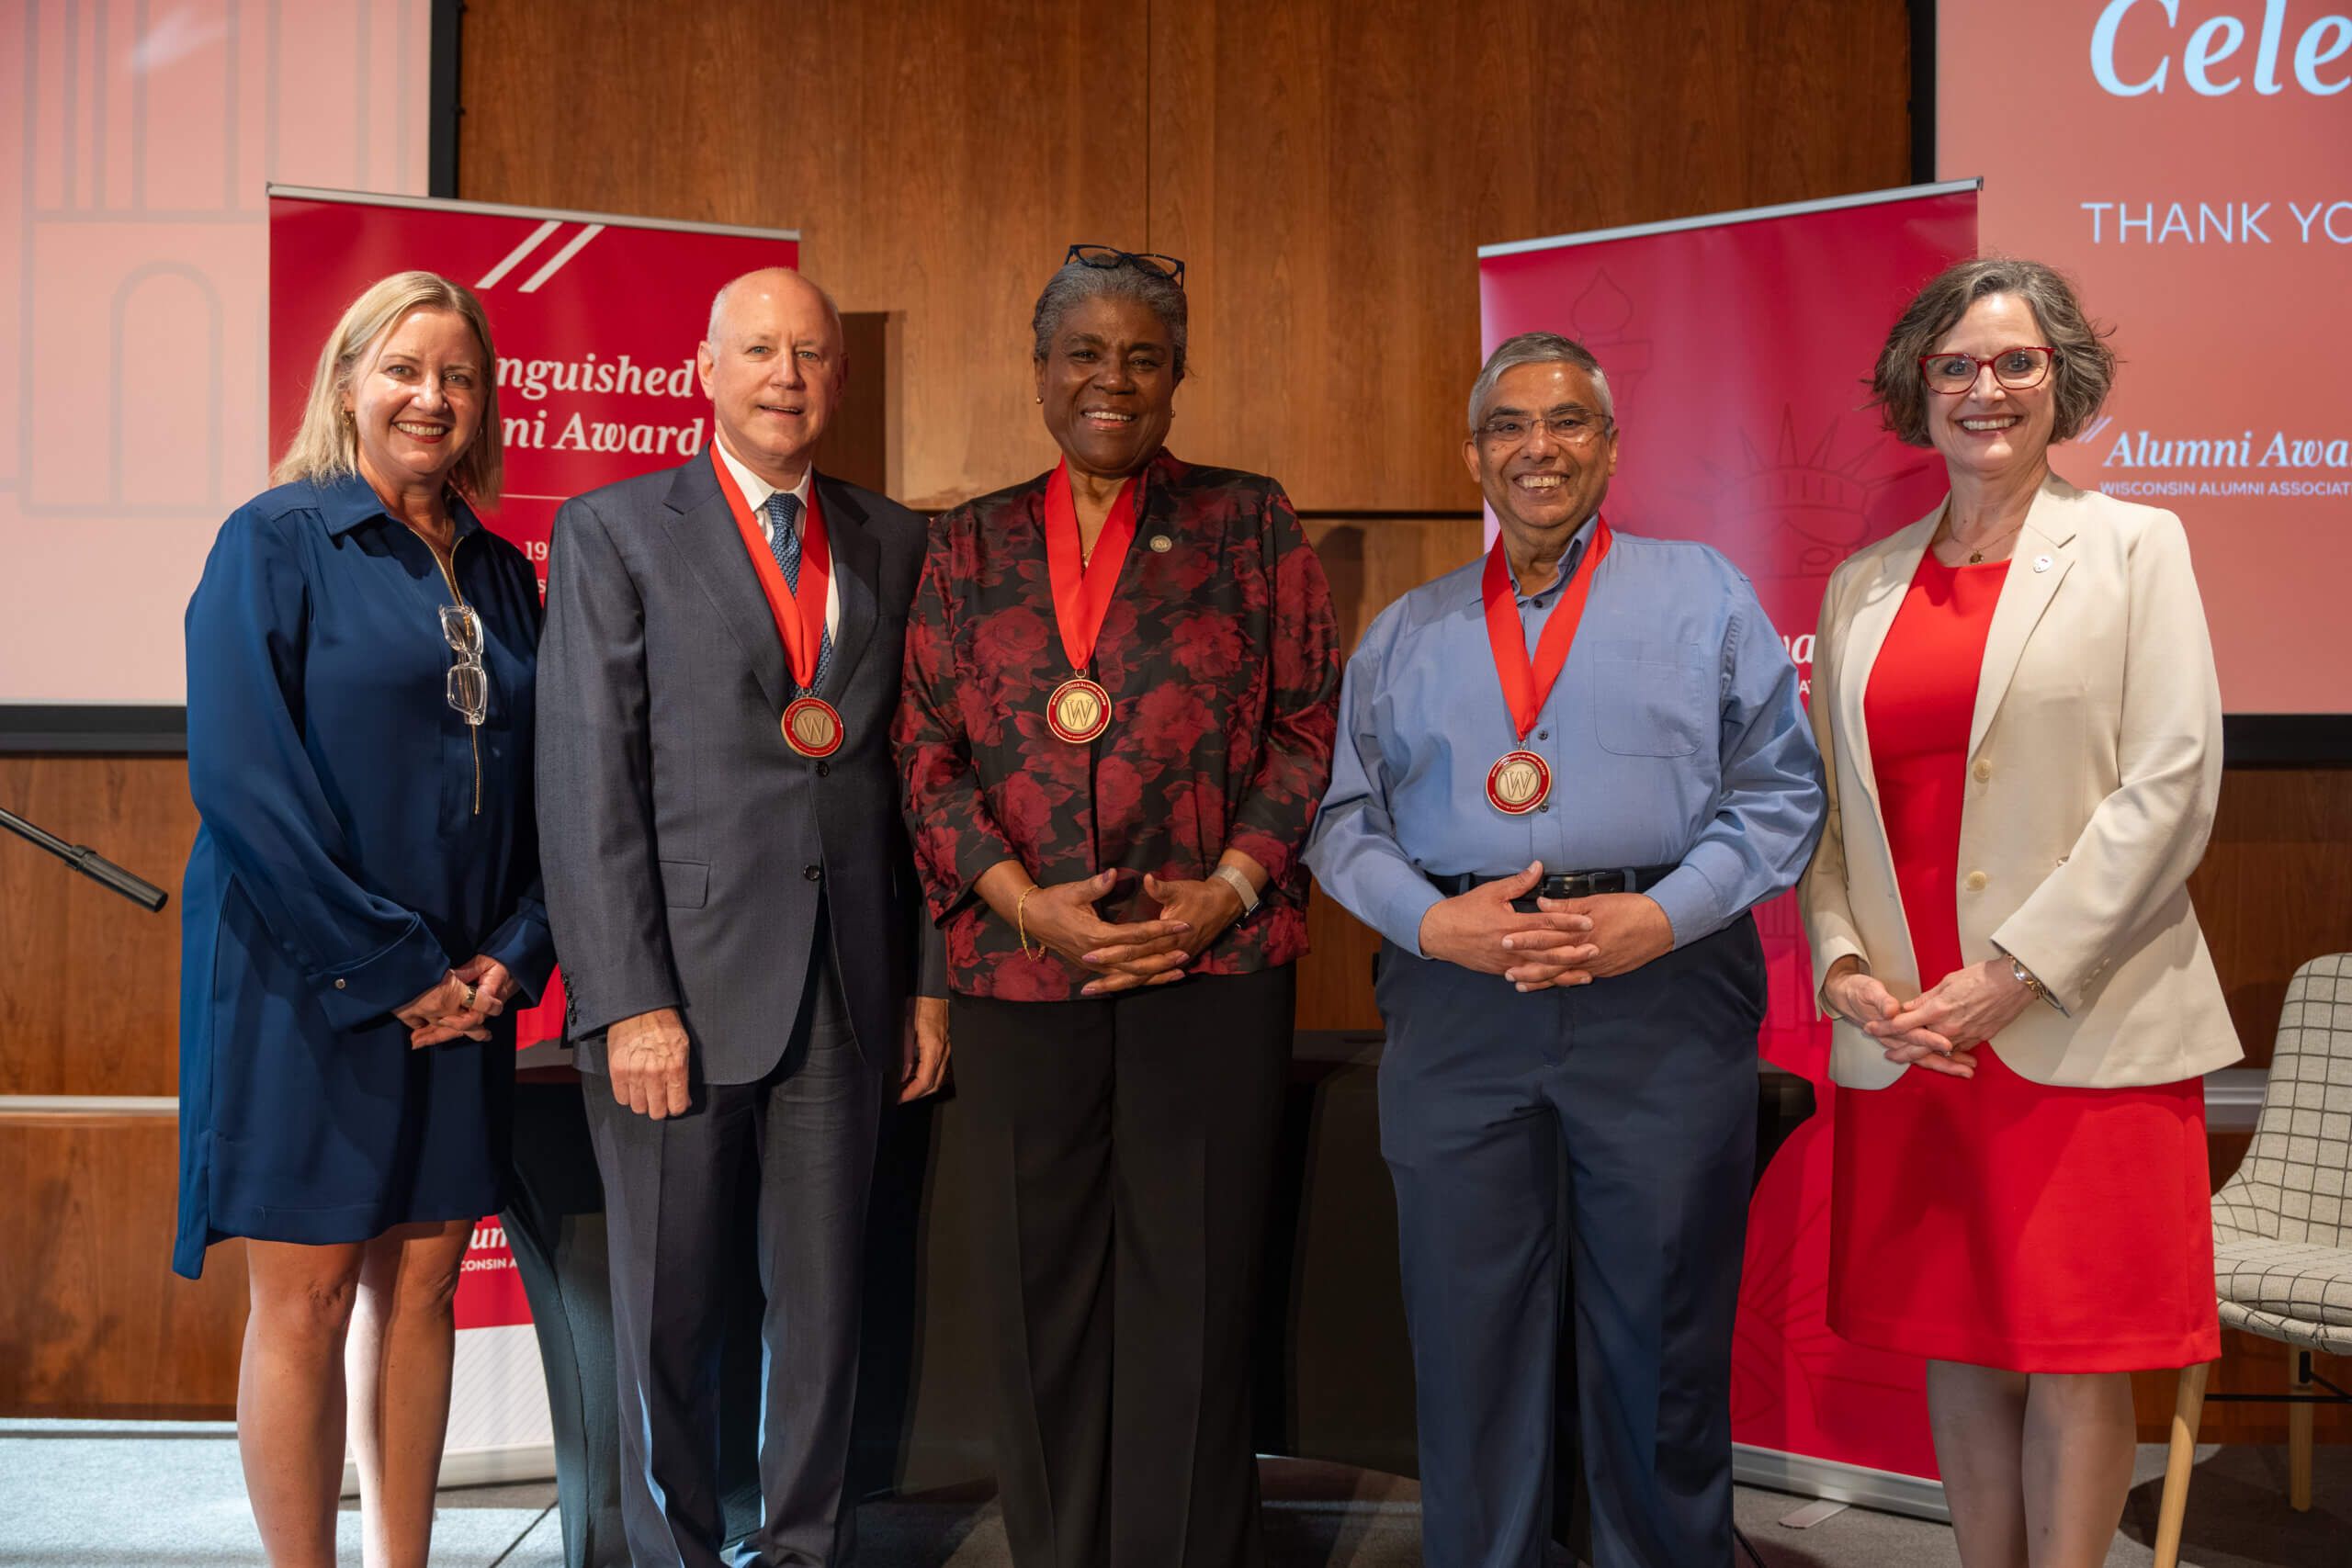
Recognition arrived from both his profession and his university in 2025. FIA inducted Sprecher into its Hall of Fame. Wisconsin honored him with a Distinguished Alumni Award. The photograph from the alumni celebration places him back among fellow honorees, wearing an award medal rather than presiding over an acquisition announcement.
His Wisconsin connections have lasted beyond the degree. He served as a Wisconsin Alumni Research Foundation trustee from 2014 to 2020. He has also spoken about returning annually to see university friends. The corporate map has spread across countries; some of the personal map still leads back to Madison.
By July 2026, ICE reported second-quarter net revenues of $2.7 billion, up 5 percent from a year earlier. Sprecher remained chair and chief executive, discussing customer demand for regulated markets, data and technology. The scale bears little resemblance to the early team’s search for participants.
The underlying question remains recognizable. Where are people struggling to connect? What information would help them make a decision? Which piece of the process is making the rest unnecessarily difficult?
Sprecher’s career offers a particular answer to what an engineer might do after leaving engineering school. He can design equipment. He can finance the plant that houses it. He can become frustrated with the market the plant depends on, and spend the next several decades working on that instead.
The toaster eventually gave way to a rather larger repair bill.