A bank’s trading screen is a small act of theatre. The name at the top belongs to the bank. The prices belong to its business. The machinery underneath may belong to somebody else. In April 2025, Mauritius Commercial Bank announced that it had integrated Integral’s technology into MCB Wave, its electronic foreign-exchange platform. Its customers would see the bank’s brand. Integral would help make the performance possible.
That arrangement explains Integral rather better than the usual procession of fintech adjectives. The company supplies infrastructure for institutions that want to run a trading business: collect prices, construct their own quotes, send them to customers, execute orders and manage the resulting exposure. It sells the machinery. Its customer decides what sort of business to build with it.
The story in four trades
- The buyer: banks, brokers, payment firms, crypto businesses and metals specialists.
- The job: connect liquidity, pricing, distribution, execution and risk in configurable workflows.
- The economics: fixed subscriptions for Integral FX and Integral Digital technology.
- The next move: apply institutional trading infrastructure to digital assets and physical precious metals.
The bank’s name on somebody else’s engine
For MCB, the project was about upgrading a single-dealer platform and extending its network across Africa. Integral supplied white-label technology and automated pricing distribution. Corporate and institutional customers could use a branded interface; the bank could distribute its own liquidity. Kabir Ramburn, MCB’s head of business management for financial markets, called Integral “the operational heartbeat” of the platform.
White labelling sounds cosmetic until you consider the buyer. A bank wants technology that serves its relationships, products and policies. It does not necessarily want to hire a small software company inside its treasury department. Integral’s proposition is that an institution can rent the underlying capability while keeping the choices that make its service distinct.
“the operational heartbeat”
Kabir Ramburn / Mauritius Commercial Bank / April 2025
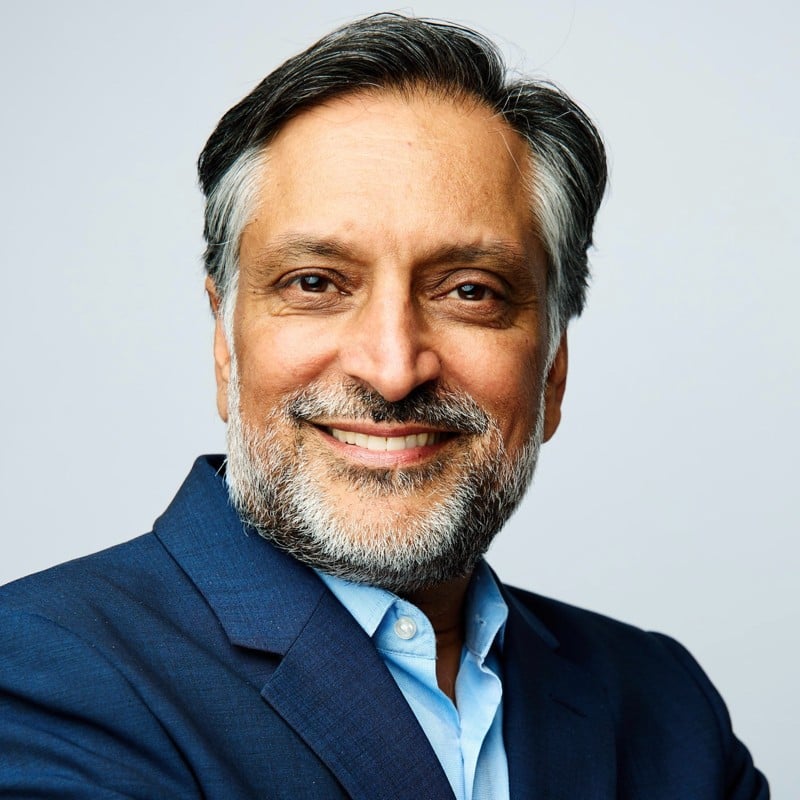
Harpal Sandhu founded Integral in 1993 on Stanford’s campus. He remains its founder and CEO. The official account describes a vision of combining technology and finance for end users. Today, the company reports more than 200 clients globally. This is an enterprise business whose work frequently appears under another institution’s name - an unusually discreet way to participate in financial markets.
The expensive part is the choreography
An exchange rate is a deceptively tidy answer to an untidy process. A trading desk may receive prices from several providers, decide which sources suit a particular customer, add a spread, check available credit, execute an order and decide whether to keep or hedge the exposure. Every handoff creates another place for delay, inconsistent data or an awkward manual intervention.
Integral’s liquidity aggregation brings different sources together. Its Price Engine applies rules to construct quotes by customer, product, trade size and other parameters. The execution management system routes orders and supports algorithms, including time-weighted execution and iceberg orders. Risk tools govern internalization, warehousing and hedging. Analytics give the desk a view of what those decisions produced.
- 01 / LISTENGather and normalize liquidity from chosen providers.
- 02 / PRICEApply the institution’s pricing rules and client terms.
- 03 / DISTRIBUTESend quotes through branded screens, APIs or other platforms.
- 04 / EXECUTE + CONTROLRoute the order, track exposure, hedge under defined rules.
A revealing example predates today’s crypto story. In 2016, FX Week reported that banks and retail brokers had asked Integral for tools to internalize customer flows. Matching or managing exposure inside the business could be more efficient than automatically sending it all into the market. Integral built FX Yield Manager; it won that year’s e-FX Initiative award. The prompt came from customers facing tighter margins and regulatory pressure. The product followed the operational problem.
The current risk offering carries that logic forward: rules can determine when exposure is held and when it is hedged, with limits and monitoring around the decision. Automation makes the policy repeatable. It does not relieve the institution of choosing a sensible policy in the first place.
A monthly bill in a market that never sits still
Integral FX and Integral Digital use fixed subscriptions for technology usage rather than volume-based brokerage fees. The attraction is plain: an active trading day need not create a proportionately larger software bill. Institutions can take individual modules or the full stack, so buying the machinery need not mean replacing every tool at once.
Two ways a technology bill can behave
A useful precedent is Swissquote. In November 2020, it extended a relationship already more than a decade old with a multi-year, fixed-cost monthly subscription. The agreement also expanded services into swaps and CFDs. That is a concrete example of an established customer adding products through shared infrastructure.
The subscription still sits inside a larger operating budget. Connectivity, execution relationships and the institution’s own controls matter. A fixed technology fee does not make every trade free. The sensible comparison is the cost of running the required workflow, including integration and oversight, rather than the headline on one invoice.
In January 2024, Vistara Growth announced $30 million in growth financing for Integral. The money was intended to expand go-to-market teams and advance the product roadmap. Vistara pointed to institutions replacing on-premise and internally built systems with modular cloud software. Its investment backed a specific purchasing shift: outsourcing more of the engine room.
A global platform with a local accent
Banco de Chile supplies a particularly useful example of why configuration matters. Its November 2025 deployment combined Integral’s Price Engine and Liquidity Aggregation with Datatec, Chile’s interbank FX infrastructure provider. Live local spot prices could feed executable rates for Chilean peso spot, forwards, swaps and offshore non-deliverable forwards, distributed across several channels.
The problem was partly the burden of manual processes; the purchasing reason was fit. Banco de Chile’s treasury manager highlighted integration with internal architecture and regional market dynamics. A global network is useful only if it can accommodate the market in which the customer actually works.
Access Bank Nigeria’s February 2025 announcement concerned another kind of reach. Alongside aggregation and pricing, Integral established foundations for sub-white-labelling services to other entities and affiliate banks. A branded interface could be passed along the network. The same underlying system could support several institutional relationships.
Then there is Goldwise. In July 2026, the Cardiff-based precious metals fintech announced that Integral would support GoldwiseConnect, its precious-metals-as-a-service infrastructure. Pricing, aggregation and risk technology underpin 24/7 institutional trading in physical gold, silver, platinum and palladium. Prices can also reach its existing mobile app through an API. The metal may sit still. Its distribution need not.
Crypto adds a credit problem
Integral Digital extends the workflow approach to digital assets. Its connectivity layer normalizes access across exchanges and market makers; settlement tools coordinate net positions and post-trade actions. Zerocap’s August 2026 announcement described customized liquidity pools, synthetic cross-currency pricing and integration with back-office providers. In September, Grupo Salinas selected the platform for COINPRO’s institutional digital-asset desk, combining crypto and fiat workflows.
Connectivity, pricing, execution workflows, risk and settlement. Credit generally rests on bilateral relationships.
A separate crypto prime brokerage offering using stablecoin margin and on-chain transfers.
Credit is a separate obstacle. Integral Digital’s FAQ says its technology relies on bilateral trading relationships, with PrimeOne available as an alternative. Launched in September 2025, PrimeOne uses the Codex Layer-1 EVM blockchain to combine credit, trading and net settlement. USD stablecoin margin moves between counterparties’ wallets as positions change value; trading limits respond to margin balances.
Integral says this mechanism sharply reduces counterparty credit exposure, and named Virtu Financial and Europa Partners among launch participants. That is a claim about the design, rather than a promise that risk disappears. Its usefulness depends on counterparties participating, collateral being available and the underlying infrastructure functioning. The clever part is the attempt to make credit move with the position instead of lagging behind it.
What to borrow from the machinery
For an institution considering Integral, the first useful exercise is to map its workflow. Which liquidity sources must connect? Who receives which price? What exposure may the desk retain? Which local venues, back-office systems and regulatory arrangements must survive the upgrade? The customer examples suggest that specificity is a purchasing advantage.
Alternatives include LSEG FXall, Bloomberg FXGO, 360T and FXSpotStream, depending on the task, as well as an internal build. An execution service and a configurable pricing-and-distribution stack solve overlapping but different problems. Integral makes sense when those connected workflows are the job. A desk seeking only access to a venue should compare that narrower requirement on its own terms.
The idea readers can copy is to standardize the infrastructure while being precise about the decisions that remain theirs. Prices, risk appetite, customer relationships and distribution strategy deserve deliberate choices. Integral’s quiet proposition is that an institution can make those choices without manufacturing every cog. There is something pleasingly economical about a technology company whose best work lets another business keep the spotlight.