In 2019, Blair Silverberg was asking founders an unfashionable question: what does your money cost? The former venture investor had watched companies sell slices of ownership to finance expenses that might have been paid for with debt. Advertising budgets, inventory and predictable working capital do not always require a new shareholder. Sometimes they require a lender willing to understand the business.
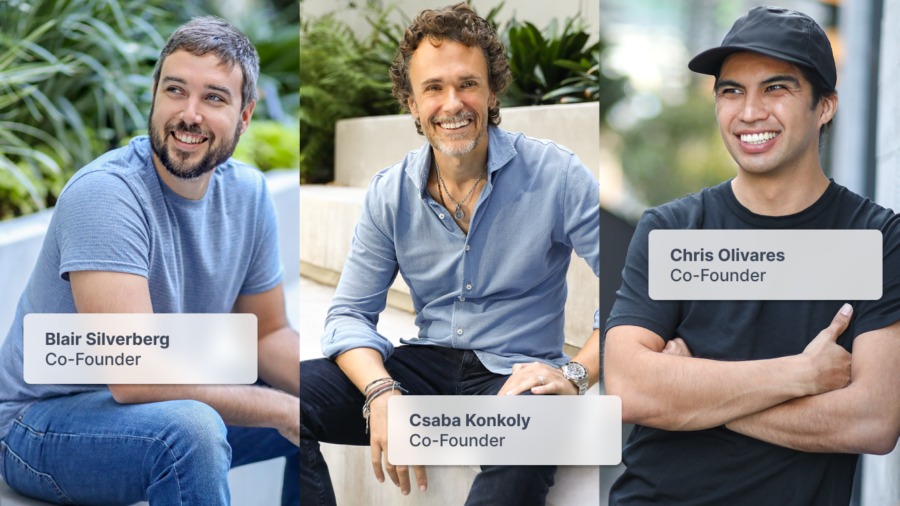
Silverberg and co-founders Csaba Konkoly and Chris Olivares called their venture Capital. Its early promise was brisk: analyze financial performance with software, then offer financing without the long tour of investor meetings. The tool was called The Capital Machine. Five years and one name change later, the machine is still present, but the proposition has grown more interesting. Hum Capital now runs a lender marketplace and, through Hum Financial, lends directly. It can introduce you to a source of money or be that source itself.
The short version
- Hum serves established US businesses seeking at least $1 million, with at least $2 million in annual revenue.
- Its marketplace matches borrowers with lender criteria; Hum Financial underwrites and funds some loans itself.
- Exploring financing is free. A completed marketplace deal brings a success fee; a direct loan carries interest and disclosed fees.
- Connected accounting and payment data may speed analysis. It does not eliminate due diligence or repayment risk.
A different first meeting
The conventional fundraising introduction often begins with a person who knows another person. Hum would prefer to begin with numbers. A company can connect systems such as QuickBooks, Stripe or Shopify, allowing the platform to assemble a current view of revenue, margins and financial position. For lenders, Hum standardizes statements and charts. For borrowers, the result is a more legible application and a better idea of which financing options fit.
That is a practical distinction. A software company with recurring revenue, a manufacturer with equipment and a beauty brand awaiting payment from retailers each need different credit structures. A generic deck can flatter all three while explaining none of them. Hum's argument is that the underlying books can reveal the actual borrowing case. Its marketplace then sorts possible lenders by their criteria. Hum says its current network contains more than 900 partners, although a large network is useful only when the matches are relevant.
The two doors
The first door is Hum Financial. Here Hum is the lender of record: its team underwrites, structures and funds the loan. The company advertises financing from $1 million to $50 million, with terms that vary by deal. It reports more than $445 million deployed since 2021 to more than 125 companies. A $200 million debt facility announced with Synovus Bank and InterVest Capital Partners in 2025 expanded the money available for this business. That facility is funding capacity for Hum, not an equity investment in the startup.
The second door is the marketplace. Hum organizes a company's information, compares it with lender preferences and introduces potential partners. Those lenders conduct their own due diligence and make their own decisions. The distinction is worth remembering when someone promises a fast preliminary answer: an indication of interest is neither a funded loan nor permission to ignore the covenants.
A connected data feed can shorten preparation; underwriting and legal work still govern a close.
What a million dollars actually costs
Hum charges nothing to create an account, connect data or explore possibilities. That is the easiest price to quote. The costly decision arrives later. A marketplace borrower pays Hum a success fee, calculated as a percentage of the capital raised, only when a deal closes and money becomes available. A direct borrower pays the interest and fees in its term sheet. Hum does not publish a universal rate; revenue, collateral, cash flow, use of proceeds, size and term change the price.
At launch, Capital described a flat fee of 5% to 15% on its own financing. That historical figure should not be mistaken for a current quote. The useful exercise is to set every term beside the alternative: the cash interest, upfront and closing fees, repayment schedule, security, covenants and any cost of equity you would otherwise sell. Debt protects ownership, but a payment date does not care whether a new product launch is late.
“There’s no excuse for not knowing your cost of capital.”Blair Silverberg, at Capital's 2019 launch
A face mask and a credit facility
The model becomes less abstract in Hum's work with LOOPS. The skincare company had demand from retailers including Target, CVS and Ulta, but larger orders meant buying more inventory before retail cash arrived. Hum's Strategic Capital team arranged a $1.75 million facility in 2024. The problem was not a shortage of ambition. It was the delay between a purchase order and a paid invoice.
Other deals show why lender matching matters. Ridepanda, which operates an electric-mobility platform, obtained a $3.8 million sale-leaseback facility through an equipment finance partner. P97 Networks raised facilities with a potential maximum of $43 million in venture debt after five investor matches on Hum's platform. These are different instruments for different cash flows. The common method is to translate the business into a financing structure a lender can actually underwrite.
The machine acquires judgment
Hum's own history complicates the tidy tale of software replacing bankers. The company launched the Intelligent Capital Market in 2021, introduced SmartRaise for faster preliminary terms in 2023 and then strengthened its direct lending operation. Andrew Eisen became CEO in 2024. In 2025, Silverberg moved to lead advanced analytics, while Stephen Isaacs, whose background includes building a large sponsor-finance business at BMO, became president. Hum's account of its credit operation now emphasizes experienced judgment working with its AI tools.
That looks like a change of emphasis, not an admission that the software failed. The early belief was that data could make a fragmented market easier to navigate. The later lesson is that taking credit risk also requires people who understand a balance sheet, a contract and the borrower behind them. The company still sells speed and access; it now owns more of the decision and, on direct loans, more of the risk.
Hum also once expanded its marketplace to equity fundraising. Its current FAQ says the platform offers debt only. That narrowing makes the promise clearer. If a company has no revenue, or is seeking less than $1 million, Hum says it is outside today's borrower criteria. If revenue exists but repayment would strain the business, a non-dilutive label cannot turn an unsuitable loan into a good one.
What to copy from Hum
A founder does not need Hum's software to borrow its best habit. Start with the books. Build a clean monthly picture of revenue, margins, cash flow, receivables and obligations. State exactly what the money will buy and when that spending should produce cash. Then compare several ways to finance it using total cost, flexibility and downside, rather than choosing the offer with the friendliest headline rate.
The same discipline works on the lending side. Ask for the data that explains a business model, then decide where judgment must enter. A useful match is more than a shared industry label. It is a lender whose loan size, collateral appetite, repayment schedule and tolerance for the borrower's kind of volatility all fit. Hum's real product is that translation. The technology reads the books; the transaction succeeds only when the humans read the consequences.