A fintech founder can build a beautiful app and still be stopped by a very unglamorous question: who is allowed to do what? The answer may involve a bank, a lawyer, a regulator and an investor, each speaking a slightly different language. House of Finance & Tech Berlin, usually shortened to HoFT, has built a business around getting those people closer together. The product is partly the room, partly the preparation, and partly knowing whom to invite.
- HoFT supports fintech growth through coaching, research, introductions and events.
- Berlin funded the launch; private industry support took over in January 2026.
- Its organising ambition is financial wellbeing: more security and choice for the people using financial products.
A public cheque with an expiry date
The origin matters because it explains the unusual guest list. Berlin Finance Initiative and Berlin Partner helped initiate HoFT with the city’s economic administration and IBB Unternehmensverwaltung. The company began in 2024; a support association followed in April. Founding association members included Deutsche Bank, N26, Qonto, Solaris and Upvest. Established banks and their younger challengers were being asked to support the same institution.
Berlin provided more than €3.5 million in launch funding. Institutional support covered 2024 and 2025, then ended as planned. From January 2026, the association became the financial foundation for continued operation, alongside commercial offerings. This was the intended handover from the beginning. The useful lesson for another city is to recruit the future supporters while public money is still paying for the start.
Berlin’s public launch funding
The room has a working address
HoFT’s chief executive, Sebastian Schäfer, previously built and led Frankfurt’s TechQuartier. In a Germany Trade & Invest interview, he described the aim as a “focal access point for the finance and tech community in Berlin”. The phrase is modest, but precise. An ecosystem needs somewhere a newcomer can begin without already knowing everybody.
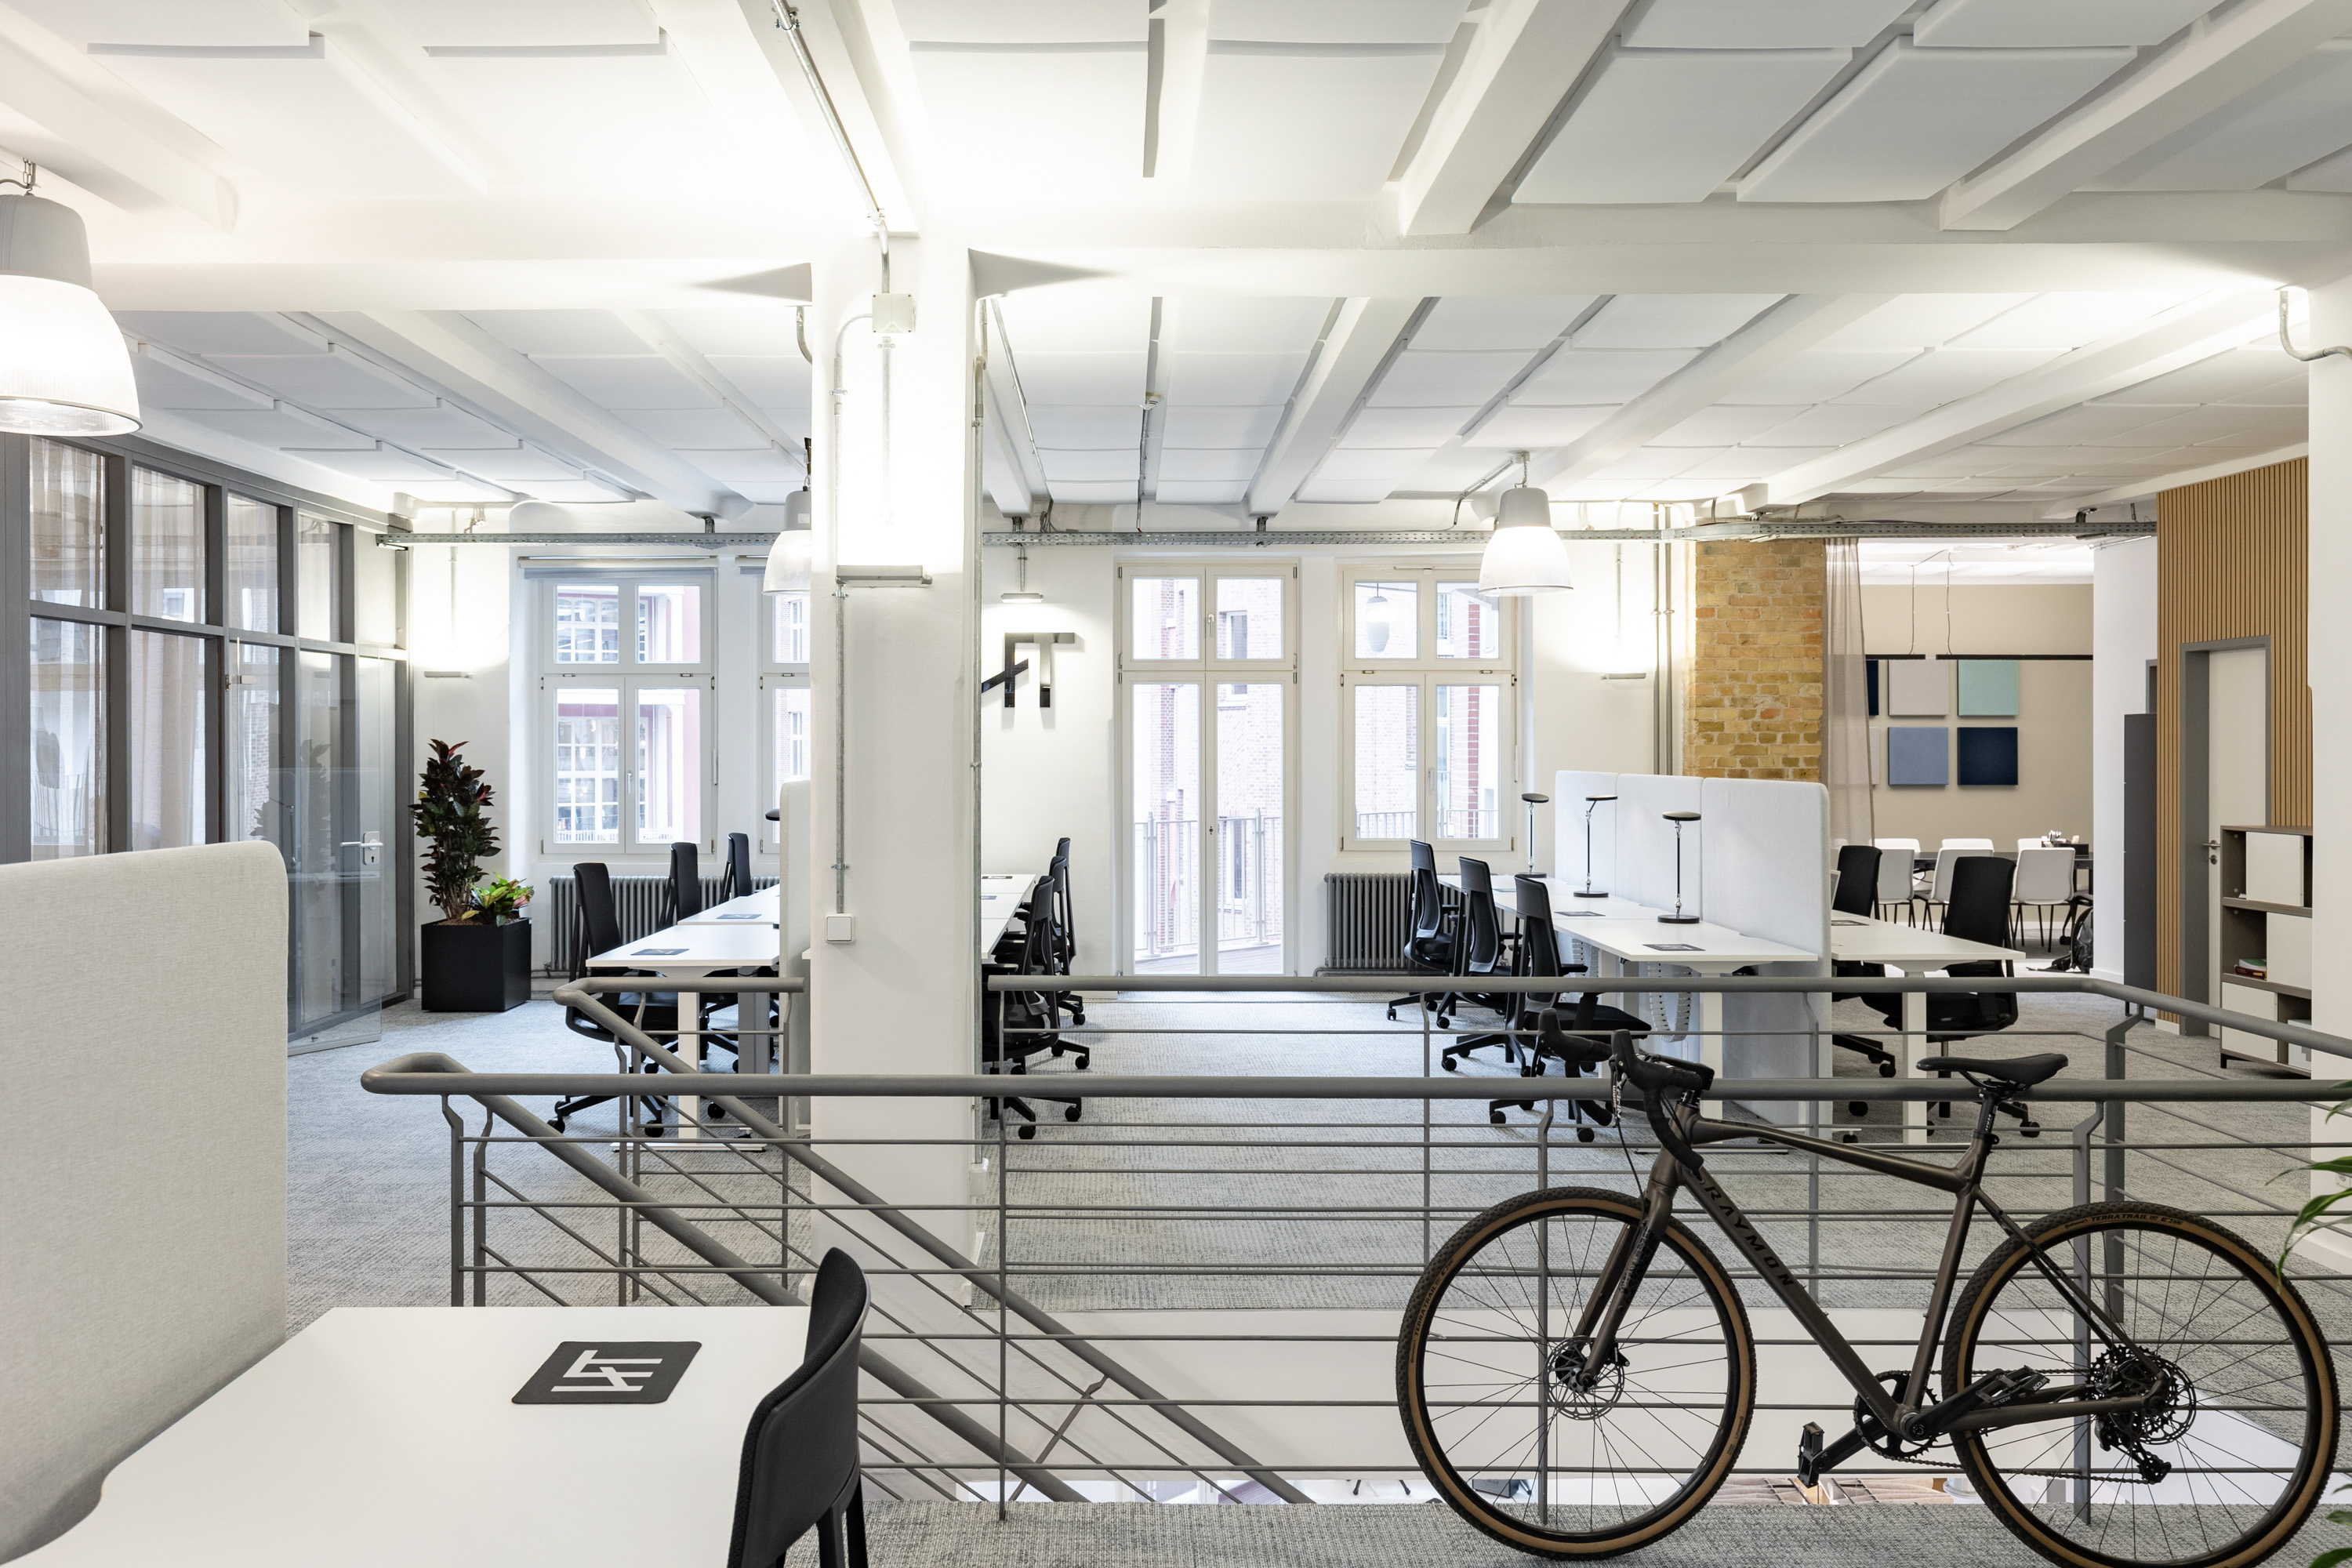
Today its campus is in Backfabrik, a former industrial bakery. Flex desks cost €350 net per month, fixed desks €550, and private office desks €650. Entry is by application, and the workspace is reserved for fintech teams. Meeting rooms, a showroom and industry events make the proposition more specific than renting a chair. Airwallex and Atrya provide public tenant testimonials; proximity to other founders and partners features in both.
A licence question before a launch party
The Scale-up Academy makes the coordination argument concrete. Its 2025 tracks addressed regulation and compliance, fundraising and investment, and European market entry. Named contributors included BaFin, financial institutions, fintech operators and specialist advisers such as Annerton, Luther, Schalast and KPMG. Participants could work on their own regulatory roadmaps rather than collect general encouragement.
The practical distinction is between doing a regulated activity yourself and working through a licensed partner. HoFT’s published workshop account examines how that choice changes as a company grows. The reader can copy the sequence: describe the actual activity, map the obligations, identify the responsible partner, then revisit the arrangement when the product changes. A workshop introduction does not confer authorisation. Access is useful because it makes preparation more informed.
London supplies a useful correction
International expansion adds another set of people who must understand the product. HoFT’s Fintech Immersion Programme combines preparation in Berlin, a delegation abroad and follow-up at home. The European Union and Berlin co-finance this particular programme, even after institutional operating support ended. Its London delegation ran in April 2026.
The resulting account challenged a familiar sales instinct. At Barclays, the delegation heard about scouting that starts with a bank’s identified problem. A startup’s claim to move quickly means less if integration into the bank absorbs that advantage. HoFT’s takeaway was to research the institution’s priorities and shape the pitch around a specific need. That is a change in the recommended approach, not evidence that every participating founder changed course.
The first useful introduction begins with a problem somebody actually wants solved.YesPress analysis of HoFT’s market-entry approach
Why the number is 53
HoFT’s more distinctive choice is what it wants this machinery to accomplish. Financial wellbeing gives the network a purpose beyond company growth. Its 2025 research with Roland Berger surveyed 1,000 people and reported a German financial wellbeing score of 53 out of 100. Fifty-two percent experienced financial worries at least weekly; 27 percent reported insufficient control or overview of their finances.
Financial wellbeing baseline
The score draws on the US Consumer Financial Protection Bureau’s methodology. It concerns felt security and freedom of choice, rather than simply the size of a bank balance. HoFT states a collective target above 60 by 2035. That is an ambition, not an achieved result. Its public assessment tool lets individuals explore the concept, while research gives institutions a common starting point.
Sell the connection, measure the consequence
The commercial offering now includes membership, research access, curated fintech matching, innovation scouting, ticketed events and workspace. Banks can seek solutions to a defined challenge; fintechs can seek relevant institutional buyers. Employers have another entry point: HoFT’s workplace research, drawing on 5,020 employees across 13 industries, informs diagnostic and provider-selection services.
Those customers arrive with different problems, which is why HoFT occupies an awkward but useful space between a hub, an adviser and an industry association. Specialist lawyers, other accelerators and ordinary coworking providers remain alternatives for individual needs. HoFT’s proposition combines them around fintech and financial wellbeing. Whether that combination is worth buying depends on the relevance of its introductions.
There is a discipline here that readers can borrow. Start with the problem, prepare before the meeting, and follow up after the trip. For employers, measure the need before choosing a benefit, then measure again. Neither a desk nor a delegation can repair weak demand or an unprepared team. HoFT’s wager is that capable people lose less time when the right conversations happen sooner. The eventual test is what those conversations produce.