Before Gal Krubiner had a company to run, he had a conversation he wanted to keep having. In August 2015, he and a future partner were talking about the gap between new financial technology and the needs of institutional investors. It was a promising subject for an evening. It became a rather demanding way to spend the next decade.
Pagaya, the business he co-founded in 2016, now connects lenders, investors, and borrowers through artificial intelligence. Its premise is that a rejected application can deserve another examination. Its founder’s story has a similar interest in reconsideration: the banker who became an entrepreneur, the friends who became colleagues, the technology company obliged to learn the habits of a financial institution.
There is a pleasing tension here. Krubiner wants financial decisions to become more sophisticated. He describes his own decision to start a business in unusually human terms: finding people whose company he would enjoy for the considerable portion of life that work consumes.
A banker learns to read the room
Krubiner was born and raised in Israel, studied economics and statistics, and built a career that took him through Switzerland, London, and the United States. His degree from Tel Aviv University combined applied science, economics, and statistics. Between 2012 and 2016, at UBS, he worked on structuring and distributing credit and asset-backed securities.
That background matters to the kind of founder he became. A loan has several lives: an application, a decision, a stream of repayments, and potentially an asset held by an investor. Krubiner had worked on the financial machinery that connects those lives. His eventual business would place technology inside that machinery.
It is a less immediately photogenic ambition than opening a new bank. No gleaming branch is required. The important moment happens when an institution can make a different decision about an application already sitting in its system. The borrower may remember the approval without ever learning the name of the company that helped make it possible.
Three friends, one difficult proposition
His co-founders brought different skills. Avital Pardo supplied data-science expertise; Yahav Yulzari brought experience raising capital. Krubiner brought his financial background. The friendship between Krubiner and Yulzari had developed in London. Their business would depend on bringing those distinct perspectives into the same room.
Early on, the founders tested their approach by investing in loans available through peer-to-peer platforms, including Prosper and LendingClub, with money raised from friends and family. This let them examine the model using actual investments before constructing a lending operation of their own. Later, when bank conversations ran into concerns about opaque underwriting models, they adjusted their approach toward investors and lending partners.
That sequence has a useful modesty. First, make a test small enough to perform. Then discover what the next customer will actually accept. A spreadsheet can declare an idea viable rather quickly. Persuading someone to entrust money to it takes longer, and comes with considerably more questions.
The application gets another hearing
Consider the business from the borrower’s side. Someone applies to a lender and falls outside the criteria that lender is prepared to accept. Pagaya’s technology can evaluate applications through a partner integration, looking for additional lending opportunities. Funding from institutional investors supports the loans. The existing lender keeps its customer relationship.
Krubiner explained that arrangement in a 2024 television interview: the network joins underwriting technology to funding from institutions such as asset managers, pension funds, and insurers. The capital relationship is essential. Identifying a borrower whom a model considers creditworthy accomplishes little if nobody is prepared to finance the loan.
The appeal is easy to understand. A customer would rather receive an offer than start again elsewhere. A lender would rather retain a customer it can serve responsibly. An investor wants assets that fit its return and risk requirements. The work lies in satisfying all three at the same time. Each participant has the perfectly reasonable habit of caring about a different part of the transaction.
In his 2019 writing, Krubiner returned to related questions: what credit scores leave out, how geography affects consumer credit, and how asset managers might use AI. Those interests place his company in a longer argument about risk. A single number is convenient. Deciding what that number misses is where the argument begins.
New York, followed by the mirror
Krubiner moved to the United States in 2018. For someone building a business that needed institutional capital, New York offered proximity to the people making investment decisions. In his telling, the city’s attraction was wonderfully literal: the decision-makers were inside those buildings, and he wanted to be among them.
Pagaya became publicly traded in June 2022, through a combination with EJF Acquisition Corp. The arrival coincided with a difficult market for financial technology companies. Interest rates were rising; the enthusiasm that had carried many growth businesses into public markets was retreating. Pagaya’s shares experienced pronounced volatility in the months after listing.
A public company gets a running commentary on its prospects, whether management finds the commentary useful or not. Krubiner later described public-company life as working with a mirror in front of him. It made weaknesses harder to ignore and execution more urgent. He also warned against listening too closely to opinions formed over very short periods.
The image suits a founder whose product makes judgments. Once listed, his own organization was being assessed continuously. A lender might take time to approve an integration. A stock market can deliver its opinion before breakfast.
The numbers that complicate the story
The scrutiny became more concrete in the company’s account of 2024. Annual revenue exceeded $1 billion, yet its GAAP results were affected by impairments associated with older risk-retention investments. In his shareholder letter, Krubiner described a $145 million reduction against a previously discussed $275 million fair-value mark. He said the company believed most potential impairments for the 2021-2023 vintages had been taken.
For a business organized around assessing credit, those details belong in the story alongside the growth. Revenue measures activity. An impairment records a reduction in an asset’s value. Adjusted operating measures and accounting profit answer different questions. Reading one as a substitute for all the others would give a rather flattering, and incomplete, portrait.
By the second quarter of 2026, the reported picture had changed. Pagaya recorded $45 million in GAAP net income attributable to its shareholders, $387 million in total revenue and other income, and $3.5 billion in network volume. Auto lending helped drive the increase in volume. These are company results, rather than a measurement of Krubiner’s personal wealth, and the distinctions between them matter.
and other income
A profitable quarter gives the original proposition something firmer to stand on. It also sets up the next examination: whether the network can keep producing results as borrowing conditions change. Consumer credit has a way of returning every confident presentation to the question of repayment.
One hundred deals, and a longer horizon
In September 2026, Pagaya announced a revolving personal-loan facility with an initial size of $460 million. Its structure allowed approximately $850 million of capital to be deployed over a 24-month revolving period. The attraction was visibility: a longer funding commitment can help a lending network plan beyond its next transaction.
The following month brought another marker. On October 12, Pagaya announced its 100th asset-backed securitization, a $650 million auto-loan deal. The company put lifetime issuance above $44 billion since its first securitization in 2018. The language is technical; the underlying requirement is familiar. People supplying money need reasons to return.
The circle around Krubiner was expanding, too. Pagaya announced Marqeta founder Jason Gardner’s appointment to its board in September 2026. Krubiner emphasized Gardner’s experience building infrastructure platforms. For a company selling technology into other institutions, the ability to make useful products and the ability to persuade large organizations to adopt them remain closely connected.
The ambition is to become ordinary
Krubiner received an EY Entrepreneur Of The Year New York award in 2024. It recognized his work founding Pagaya and developing its lending approach. Recognition makes a convenient milestone in a biography. His stated ambition, however, is an everyday kind of adoption on a much larger scale.
At Mind the Tech New York in March 2025, he described a goal of having all 20 major American banks adopt Pagaya’s technology in the coming years. He also traced the business back to Kalisher Street in Tel Aviv. The distance between that starting point and the American banking system gives the ambition its particular shape: build in one financial and technological community, earn acceptance in another.
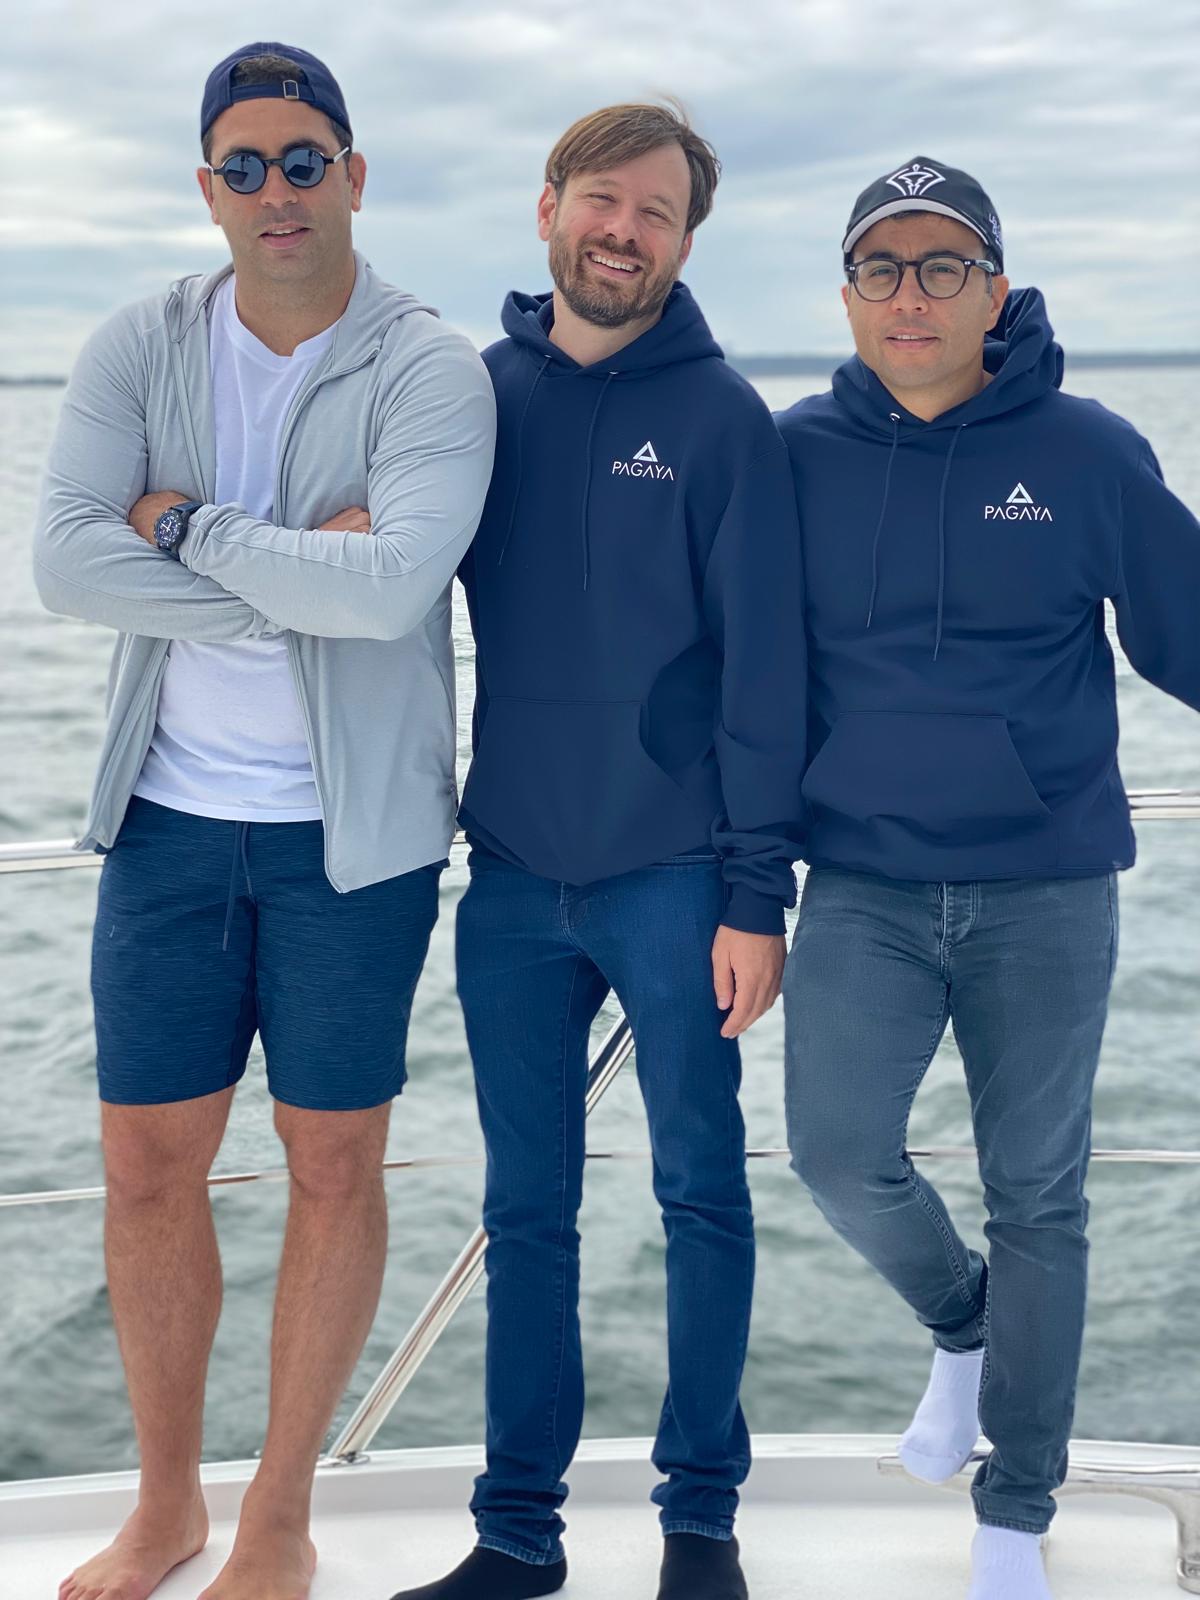
There is another measure of success in his earlier account of entrepreneurship: a new practice becoming common. That is a demanding goal for an infrastructure business. If it works, users may stop noticing the novelty. What once required an explanation becomes an ordinary part of how a lender operates.
His picture of a working day is equally grounded. In 2019, he described early starts without a strict daily routine and made a point of seeing friends and family after work. Long hours were accompanied by a reason to leave the office. Even financial technology benefits from an occasional conversation without a funding requirement.
“I find inspiration in my partners when faced with a challenge.”Gal Krubiner, 2019
That is where the biography returns to its beginning. The company has grown into public filings, institutional funding structures, and decisions about billions of dollars of loans. Krubiner’s account of why he wanted to build it still includes the people he wanted beside him. The applications get their second look. The conversation continues.
Continue the conversation
Interviews, writing, company updates, and places to follow along.