Somewhere between an earnings call and a podcast, a company changes its story by half a degree. The chief executive reaches for a new phrase. A concern once waved away gets a longer answer. Nothing rings a bell. No terminal flashes red. Yet, for an investor paying attention, the shift may matter more than the polished slide deck that arrives three weeks later. Devon Krapcho built his early career looking for changes like these. Then he decided the looking itself needed a redesign.
Krapcho is the co-founder and CEO of Cohesion, a three-person New York company in Y Combinator’s Spring 2026 batch. Its product is aimed at a very specific species of professional: the fundamental public-equity analyst, surrounded by information and still anxious that the important thing is hiding in the unread pile. Cohesion deploys AI agents to monitor earnings, news, podcasts and social feeds, then brings forward developments that may alter an investment thesis.
The proposition sounds technical. The irritation underneath it is wonderfully ordinary. Too much time disappears into searching. Krapcho spent more than five years at Long Path Partners covering software companies. He knew the ritual of checking what changed, checking whether something changed and checking again because the market had moved and nobody knew why. His company begins with a blunt observation: research tools are good at answering questions, but the analyst must still know which question to ask.
“Cohesion research agents are constantly scouring the web, answering thesis-defining questions for hedge fund investors.”Devon Krapcho, describing the product
A founder trained on the other side of the screen
There is a neat circularity to an investor in software companies becoming a software founder for investors. Krapcho has crossed the table without leaving the argument. He used to judge whether products could become durable businesses. Now he must persuade customers that his own product belongs inside a guarded research process where false confidence is expensive and habit is a formidable incumbent.
His public trail suggests that markets and products have long occupied the same mental neighborhood. Before Notre Dame, he was the youngest member of a three-person team developing Word Dash, a word-game app, and held the CEO title. A college friend later recalled that the two of them sketched a Bluetooth bike lock after late-night Introduction to Psychology study sessions. The lock never escaped the sketchbook. Their Madden rivalry was more operational: after roughly 50 one-dollar defeats, the friend settled up with a large bag of quarters.
At Notre Dame, Krapcho made the interests official. He became vice president of the Investment Club for the 2017-2018 academic year. In 2016, he joined Grant Ebenger and Alyssa Loffredo at the Cornell Undergraduate Stock Pitch Challenge. Their subject was Popeyes Louisiana Kitchen. Their recommendation was sell. It is a deliciously unfashionable artifact now, less because of whether the call worked than because it shows an undergraduate willing to put a crisp verb beside a messy company.
There was also Cryptalpha, a student venture that proposed automatically balancing money across ten major digital currencies. Krapcho led the project with Nikhil Garg, and it reached the semifinalist group in Notre Dame’s 2018 McCloskey New Venture Competition. The project belongs to its crypto moment, but the design instinct feels current: take a research-heavy financial choice, make the rules legible and let software carry part of the load.
Krapcho graduated cum laude from Notre Dame’s Mendoza College of Business in 2018. His full name, Devon Alexander Krapcho, sits in the commencement program between the ritual Latin honors and hometown, Alpharetta, Georgia. Soon the student projects gave way to professional investing. Five-plus years at Long Path supplied what founder biographies like to call domain expertise. A less polished phrase is probably better: he accumulated grievances.
The search box has a timing problem
Cohesion’s bet is not merely that artificial intelligence can summarize a filing. That trick has become table stakes. The more consequential wager is temporal. An agent can begin before the query. It can watch sources continuously, compare today’s language with last quarter’s and push a relevant change toward the analyst. Search retrieves what someone requests. Monitoring tries to notice what someone should have requested.
The distinction matters because professional research is full of negative work. An analyst may spend an hour establishing that a transcript contains no meaningful change. Necessary, yes. Memorable, rarely. Krapcho is trying to delegate that vigilance without pretending to delegate conviction. The machine can scan. The investor remains responsible for deciding whether the clue is signal, noise or a particularly persuasive coincidence wearing a tie.
The founding team is arranged around that boundary. Krapcho brings the buy-side workflow and software-sector context. Matthew McBrien worked in engineering and security at Amazon Web Services. Matt Munns previously built AI for investors at T. Rowe Price. Together, their backgrounds cover the customer’s habits, the infrastructure’s demands and the awkward work of making machine intelligence useful inside an investment process.
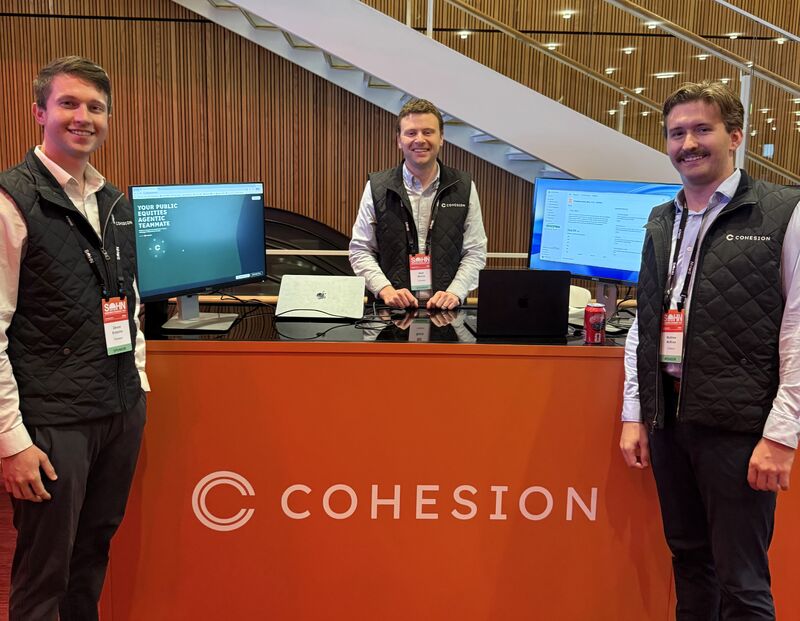
In April 2026, Krapcho announced that Cohesion had joined Y Combinator and was already live with more than ten long-short and long-only fundamental equity funds managing a combined $10 billion-plus. Early access came with a practical invitation: send twenty tickers and let the agents set up coverage. The narrowness is revealing. Grand claims about reinventing finance were translated into a watchlist an analyst could assemble before coffee cooled.
The moat walks into the pitch
A month later, Krapcho was one of three CEOs asked to pitch a venture capitalist live in front of his Y Combinator batch. The first question was the startup catechism: “What’s your moat?” The timing gave him a tidy demonstration. Sundar Pichai had recently been asked the same thing on a podcast, and Cohesion’s agents had found it. The product’s argument arrived inside the conversation about the product.
Krapcho framed the use case with questions an investor might ask about a company leader: Is the chief executive wavering? Has the podcast-circuit pitch changed since the last earnings call? These are not database fields. They are patterns made from tone, repetition, absence and context. They also carry the risk of overreading. The useful agent will need to present evidence cleanly enough that a skeptical analyst can disagree with it.
That may be the deeper product challenge. Information is abundant; trust is scarce. A financial analyst will tolerate a slow tool more readily than a confident fabrication. Cohesion must therefore sell two speeds at once: the speed of continuous software and the deliberateness of an investment memo. If it works, the prize is not simply quicker reading. It is a research desk with a wider field of view.
The next research interface may begin before the analyst knows there is a question.
The old habit inside the new company
Krapcho’s story resists a cinematic founding moment. There is no single napkin on which Cohesion appears fully formed. There are instead several small attempts to turn curiosity into a system: a word game, an unbuilt bike lock, a crypto-balancing tool, an investment-club role, a stock pitch and years of covering software. Each left behind a different reflex. Build something. State the thesis. Invite the rebuttal. Watch for what changed.
Even the lighter anecdotes fit. The friend with the quarters remembered Krapcho as someone who could turn study sessions into a business idea and competition into an absurdly literal settlement. Earlier teachers and coaches described him as modest, demanding of himself, caring toward others and willing to adapt positions for a younger soccer team. Those are old observations, not personality software frozen at version one. Still, they sketch a useful contradiction for a founder: competitive enough to keep score, sociable enough to make the score funny.
Today the scoreboard is harder to read. Cohesion has three people, institutional customers and an accelerator badge. It also has the usual early-company questions waiting just offstage. Can its agents catch signals that matter consistently? Can they show their work? Will investors place a new layer between themselves and the original material? Can a tool built around attention avoid becoming another place demanding attention?
Krapcho’s advantage is not that he can answer every question now. It is that he knows which failures would feel intolerable to the customer because he used to be the customer. The founder-market fit here is less a romance than a scar tissue map. Every manual search points to a feature. Every missed podcast remark becomes an argument for monitoring. Every dubious summary becomes a demand for evidence.
Cohesion calls itself modern intelligence for finance. The phrase has the polish of a homepage, but Krapcho’s actual project is earthier. He wants to rescue the analyst from the digital equivalent of checking every cupboard before leaving the house. Let the agents keep watch. Let people spend their finite attention on interpretation, debate and the occasional uncomfortable sell recommendation.
For someone who once imagined a lock that opened by Bluetooth, the new ambition has a pleasing inversion. Cohesion is not trying to lock information away. It is trying to unlock the hours buried inside finding it. The product will be judged by what its agents notice. Krapcho will be judged by whether investors learn to trust the knock at the door.