At Maintera, the customer and the vendor were living in different months. Clients could take 60 to 120 days to pay. Vendors wanted their money within 30 days, sometimes sooner. Somewhere between those calendars sat a facilities-management company sending roughly 200 invoices a day. Growth supplied more work, and also more waiting.
- The job: connect receivables data, organize collections and forecast incoming cash.
- The twist: financing sits alongside the software, so an invoice can become cash before it becomes payment.
- The useful lesson: give every overdue account a next step, and give exceptions a human owner.
The customer’s clock, the vendor’s clock
Maintera had no formal collections process. Its finance director, Aaron Lynch, flagged overdue accounts from his own inbox. In Daylit’s account, the company was also carrying payment-term risk into new contracts without being able to quantify it. A sale could look perfectly respectable until somebody asked when the money would arrive.
Daylit helped establish reminders before an invoice fell due, on its due date and after it became overdue. Older accounts received their own follow-up schedule; multiple invoices were batched into one customer message. The company reports approximately 80% current receivables within weeks. Lynch subsequently used payment data to inform new contract pricing. The first failure here was mundane: follow-up had been left to chance.
A lender learns to listen
Daylit began as Lendica. Founded in 2020, the company dates its operating launch to January 2022. Its early proposition was embedded finance: put access to capital inside the software where a business already makes decisions. Partnerships with CSG Forte and EBizCharge brought that approach to payment platforms and their business customers in 2024.
That distribution model matters. A small business need not abandon its everyday software to approach a lender. The lender, meanwhile, can work with business data already present in those systems. CSG Forte’s partnership announcement described software vendors receiving a portion of financing fees, giving the channel a reason to participate.
In September 2025, Lendica became Daylit and announced $110 million in equity and debt, led by Companyon Ventures, with NextView and SixThirty participating and a Viola Credit facility. Those are different pockets of money: capital to build the business, and borrowing capacity to help finance customers. Treating the whole sum as venture equity would make a handsome headline and a poor explanation.
The financing history gives its AR software a particular angle. Daylit connects customer communications with accounting data, recommends collection actions and offers a 13-week cash forecast. Its financing tools can address a cash shortage while the collections process addresses the unpaid bill. The September announcement said the business had financed hundreds of millions of dollars in invoices.
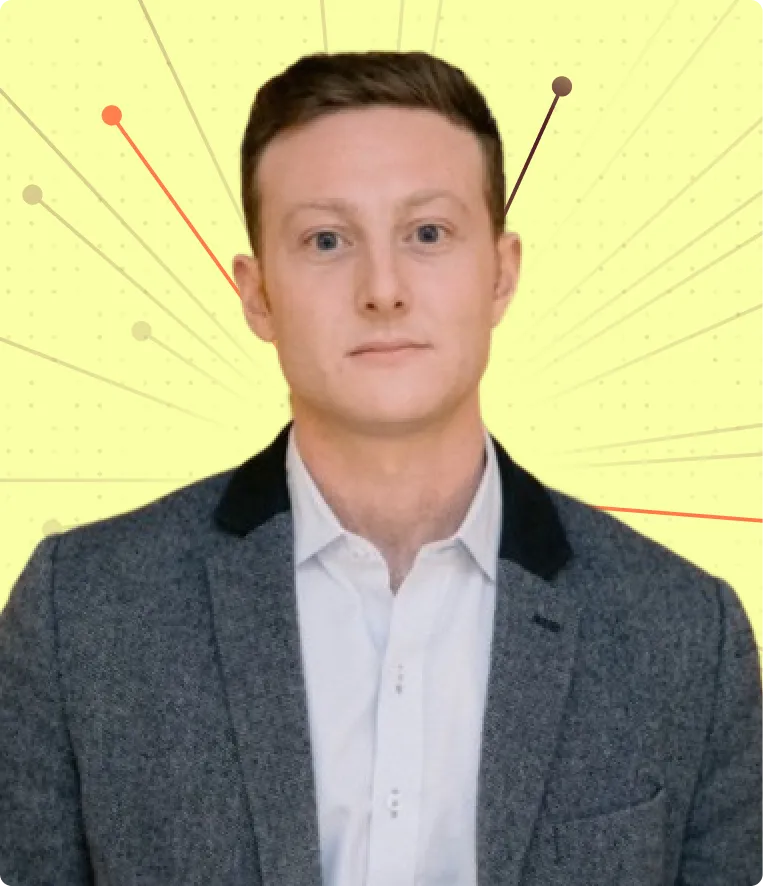
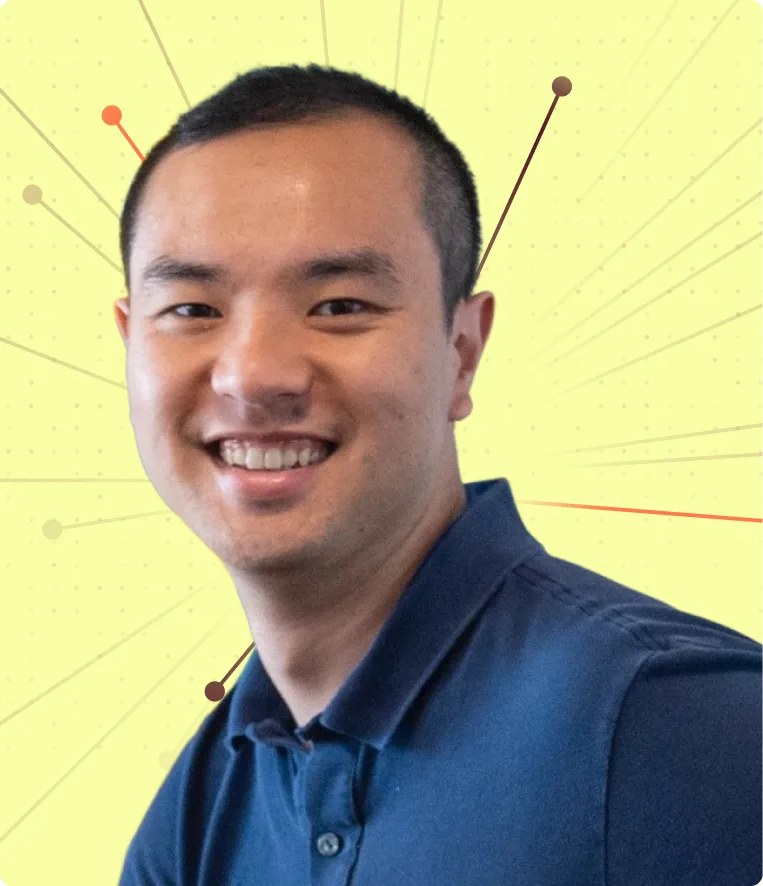
Shulman’s background includes private-credit trading and risk systems; Shu worked on quantitative research at J.P. Morgan. Their company describes a progression from underwriting agents to receivables and communication agents. The technical continuity is sensible: both jobs require understanding a business through scattered financial evidence.
Its intended users are CFOs, controllers and collections teams, with named customers spanning chemicals, staffing and consumer products. Maintera considered another platform and custom NetSuite scripting before choosing Daylit. Its account credits simplicity, value and quick responses to feature requests. That is a practical buying argument: the person responsible for collecting money also has to live with the system collecting the information.
The inbox needs manners
An overdue balance is easy to spot. The reason it remains overdue is harder. A customer might need payment instructions, dispute the work or promise a transfer without specifying a date. Collections software has to distinguish these situations before deciding what to say. Otherwise, automation merely distributes irritation faster.
Daylit’s September 2026 explanation makes the controls unusually concrete. Teams choose Off, Create draft or Auto-send separately for each supported reply type. Responses use company templates. Optional AI wording can alter greetings and acknowledgements; checks reject changes to protected facts. Immediately before sending, the system checks frozen cases, blocked or bounced addresses, opt-outs and sending limits.
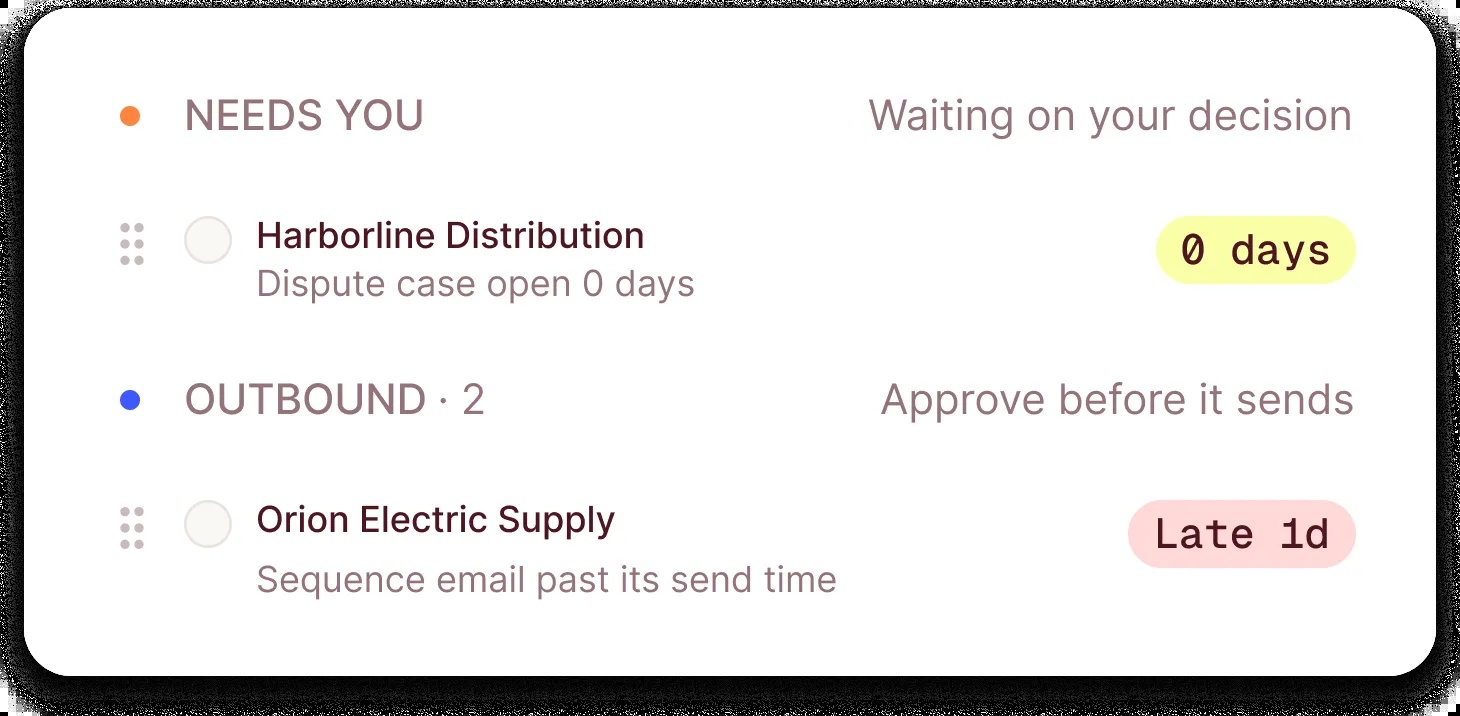
There are useful boundaries. The described replies do not attach invoice PDFs; they provide information in the message body. They do not answer every conceivable email. Recorded opt-outs are checked, but the system does not infer an opt-out from a reply’s wording. Sensitive negotiations and unfamiliar requests still need people.
“What’s going on with that account?”Jared Shulman, describing the question Daylit aims to answer
Uptime Health Services illustrates the appeal for a stretched team. Daylit’s case study describes nearly a dozen business units and essentially one collections person. Different units received different outreach rules, including exclusions for card-on-file customers. The reported result was nearly 50% more current AR without another collector. It is a customer account published by the vendor, rather than a promise for every buyer.
Cash now, with a price tag
FundNow advances money against invoices. Current PayLater and OfferTerms pages describe customer payment plans and flexible terms, with the seller paid upfront. DrawDown supplies a working-capital credit line and says it charges fees on amounts drawn, without early repayment penalties. Software and financing meet around the same commercial problem, but they solve different parts of it.
The price deserves arithmetic. Daylit’s FAQ lists a 1% processing charge and roughly 1% monthly financing, depending on risk. Its example is a $10,000 receivable financed for 60 days: approximately $200 financing plus $100 processing. Earlier cash therefore costs about $300 in that example. A finance team can compare that with the value of keeping operations moving; approval and actual terms still matter.
Illustrative pricing, dependent on risk. Financing charges are separate from software costs.
The useful thing you can steal
Daylit competes with AR platforms, including Monk and Stuut, and with the familiar combination of ERP reminders, spreadsheets and human collectors. Its distinguishing proposition is the proximity of payment intelligence to capital access. For teams with reliable data and recurring collection work, that combination merits a look. It cannot make disputed work acceptable or an insolvent customer solvent.
The portable lesson costs less than a software contract: consolidate account context, establish a follow-up cadence, batch messages and test routine replies in draft mode. Daylit also offers free AI Skills lessons on invoice validation, bank matching and routing collection emails. The invoice may be where a sale ends. It is also where a rather revealing conversation about the business begins.
Follow the money
Explore Daylit, its AR product and free AI Skills lessons. Read the company’s latest writing and funding announcement.