A cereal box is an unlikely place to look for a theory of international finance. Davis Parakal has found one there. In October 2026, the Remitly executive proposed giving money transfers the equivalent of a nutrition label: a compact account of the price, the timing and what arrives at the other end. Breakfast, apparently, has a few things to teach the payments business.
The comparison has a useful sting. A transfer can advertise a fee while leaving the customer to consider the exchange rate separately. Speed can occupy the headline while the amount received waits elsewhere on the screen. Parakal wants the essential information brought together. Someone sending money should be able to compare the whole transaction before committing to it.
For Remitly’s UAE CEO and general manager for the GCC, this is familiar territory viewed from a different angle. His working life has included the code behind telecom services, banking apps in India, consumer remittance products, salary wallets and travel cards. The labels have changed. The recurring problem is how to make a complex financial service usable by the person holding the phone.
A career that began behind the screen
Parakal studied computer science at the University of Calicut between 2005 and 2009. His early career included co-founding Dot point software, where the project was an enterprise resource planning product for education. By the end of 2009, he was working in telecom software at MobME Wireless Solutions, with tools including Asterisk, PHP, MySQL and Ruby.
Those are the sorts of names that rarely trouble the customer. They belong to the machinery underneath a service. Parakal’s subsequent roles would take him progressively closer to decisions about what the service should do, how teams should build it and how a business should put it into customers’ hands.
Postgraduate study at Coventry University in 2010-2011 added project management to that technical background. His project examined using lean-startup methodology as a project-management tool in small and medium-sized technology businesses. It was a practical subject: how an organisation can learn while making something, rather than treating every initial assumption as settled wisdom.
The bank moves into the pocket
Back at MobME, Parakal moved into engineering project management and then digital banking leadership. His account of the Digital Banking Labs years includes building a team of 60. Product and engineering came under his responsibility, alongside work with financial institutions. The job combined deciding what to build with the less glamorous business of getting it delivered.
The projects listed on his professional profile make the shift tangible. In 2015, they included Federal Bank’s FedMobile, an account-opening mobile application, and mobile passbooks for Union Bank of India and Bank of Baroda. Account access, transfers and transaction histories were becoming tasks a customer could carry around, rather than activities tied to a visit.
There is a particular discipline in that work. A bank may have many systems and departments; the customer has one task in mind. Making a balance visible or a transaction understandable requires those separate pieces to present a coherent answer. Parakal’s career was moving from maintaining the machinery to shaping the encounter with it.
- MobMEEngineering & banking
- Lulu MoneyConsumer products
- BFC PaymentsWallets & cards
- RemitlyUAE & GCC leadership
Selected roles, rather than a complete chronology.
The people who worked with him add another dimension. Vishnu Gopal, who managed him for a period at MobME, recalls an engineer interested early in how the business worked and what customers wanted. Linson Alfred remembers a leader who helped resolve technical challenges and supported his team. These are colleagues’ assessments, but they give the progression from engineering to management a more personal texture.
There is also a small surviving trace of the team-building work: his public code-sharing account contains recruitment descriptions from 2015 for banking-software roles. Mobile developers, backend developers and a client relationship manager appear in the collection. Building a banking service required a group with different skills, including someone responsible for carrying questions between clients and the technical team.
Payday is a product question
In December 2018, Parakal took up a digital-products role at Lulu International Exchange. His remit covered Lulu Money’s consumer services across mobile, web and cards. That brought the cross-border transaction into the foreground: money being managed in one place, often with a purpose somewhere else.
At BFC Payments in Bahrain, the problem widened again. A 2021 app announcement identified him as head of business development, strategic partnerships and innovation. The new BFC Pay app combined international transfers, local bill payments and wallet-to-wallet payments. One of its central uses was a digital salary account for people outside conventional banking.
Employers could disburse wages directly into customers’ mobile wallets through the payroll system. That connected the moment money arrived with the things someone needed to do next. A salary could become a bill payment or a transfer without first requiring an entirely separate route into digital finance.
By 2022, Parakal was being identified publicly as general manager. BFC’s card introductions that year linked the wallet with physical spending and access through branches. The product had to accommodate more than a tidy demonstration on a phone. People needed usable ways to receive, move and spend their earnings.
The holiday-money test
Then came a different customer question: what happens when the money in your pocket and the price on the menu use different currencies? In early 2023, Parakal was explaining BFC Pay’s Travel Buddy, a multi-currency prepaid Visa card. Customers could manage currency balances through the app, with a rate-lock feature for money converted ahead of spending.
To explain it, he offered a hypothetical trip to London. A traveller planning ahead could buy sterling before departure and hold that balance for later purchases. The example was deliberately ordinary. Foreign exchange becomes easier to discuss when it is attached to a holiday budget rather than a wall of market terminology.
“The customer gets complete control to manage their own money”
Davis Parakal, discussing Travel Buddy, February 2023
The line captures the emphasis of those interviews: applying for the card, adding funds and managing balances through the same app. In January 2024, a partnership with financial marketplace Daleel added another way to apply for Travel Buddy, with a first-year annual-fee offer. Distribution had become part of the product problem, too.
Three Gulf milestones, three different jobs
By 2026, Parakal’s public role was at Remitly, leading the UAE business and holding wider GCC responsibility. The year brought a sequence of announcements that might look similar in a list of corporate milestones. Look more closely and each involved a different piece of the work.
In May, Remitly announced an Abu Dhabi office. Parakal described the preceding 18 months as time spent building locally, learning what communities needed and developing trust. His explanation connected a permanent office with the relationships around it: customers, partners and regulators, all with a reason to care whether the business would stay and deliver.
A separate regulatory record puts a precise date on another responsibility. From 13 May 2026, the Dubai Financial Services Authority lists Davis Dominic Parakal as a licensed director and senior executive officer of Remitly (DIFC) Limited. The public register gives a formal counterpart to the work described in his regional title.
In July, Remitly announced a Stored Value Facilities licence with Exchange Business Category IV from the Central Bank of the UAE. The company presented the authorisation as a basis for developing products for UAE customers. Parakal thanked the regulator for its engagement. Growing a payments service involves both the customer-facing promise and the permissions that let a business fulfil it.
Abu Dhabi office announced
CBUAE licence announced
D360 Bank MoU announced
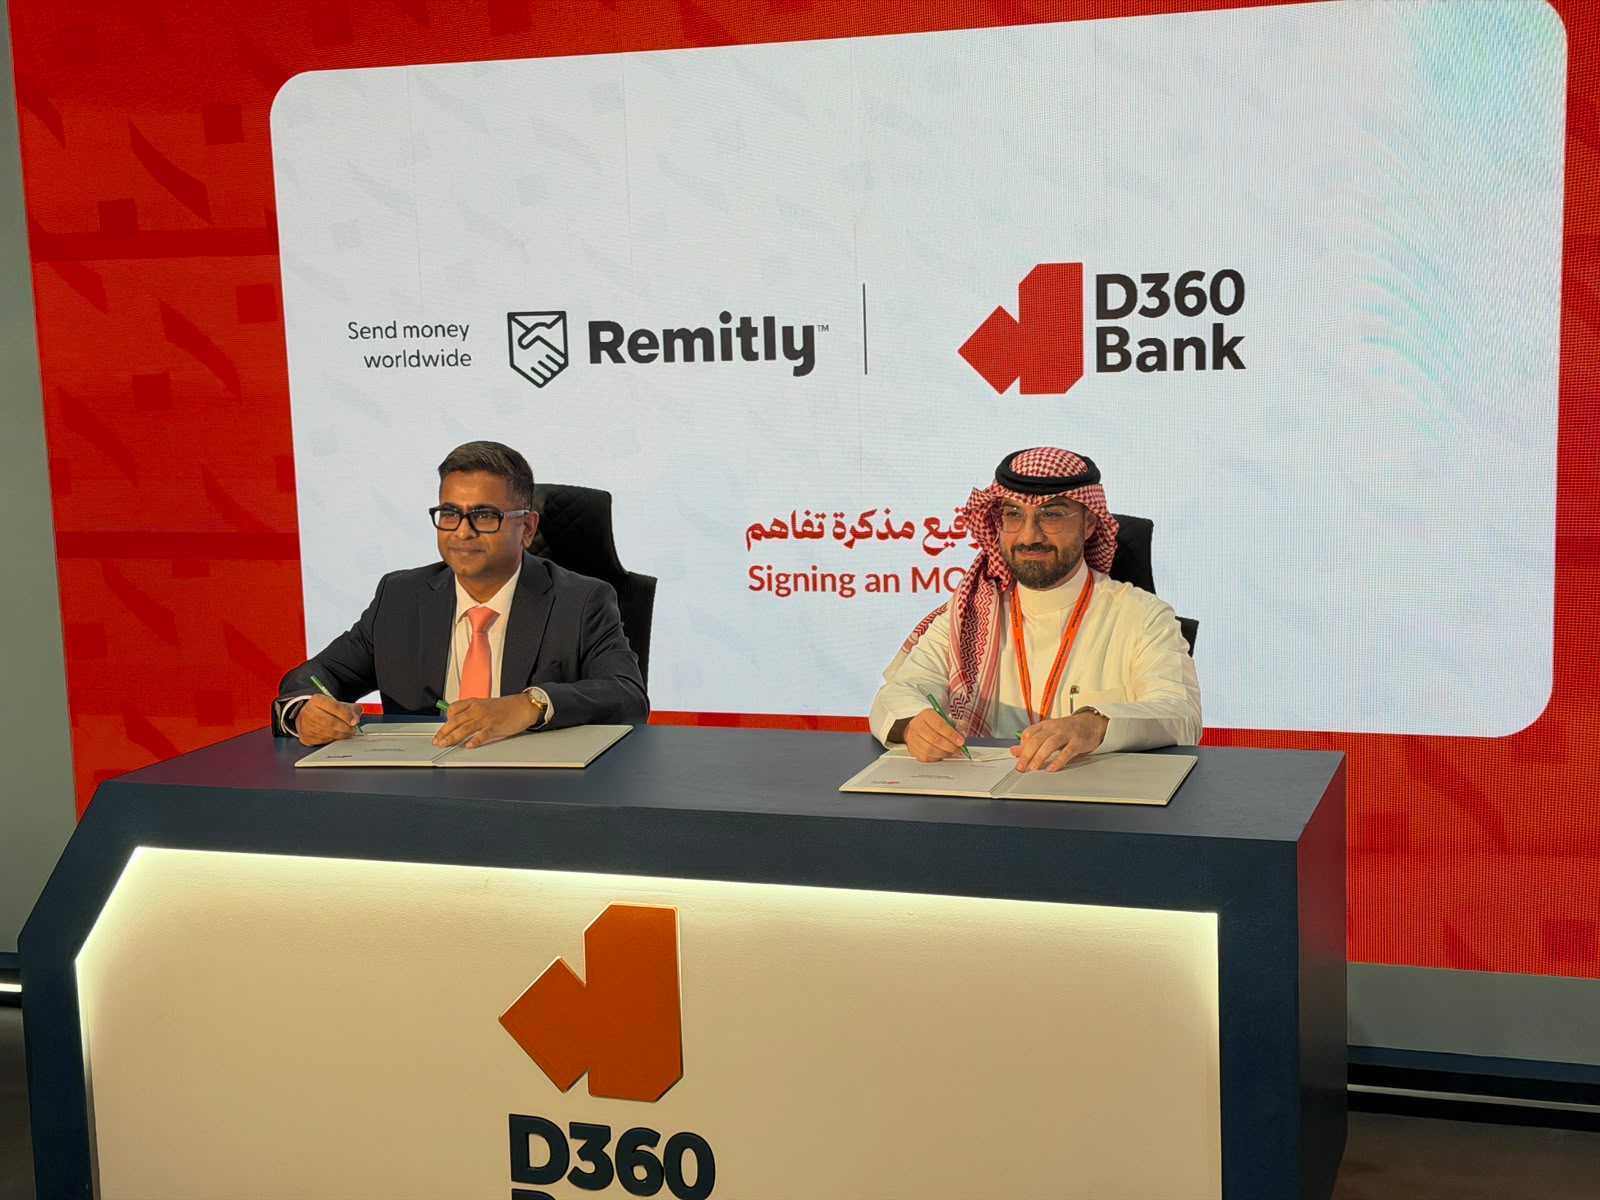
September brought an agreement with Saudi Arabia’s D360 Bank, announced at Money20/20 Middle East. The proposed collaboration would combine Remitly’s network with D360’s local capabilities, exploring bank-account payouts to recipients in the Kingdom from more than 30 Remitly send countries.
The wording matters. This was a memorandum of understanding, with regulatory and stakeholder work preceding any commercial launch. A signing photograph records an intention. Turning that intention into a dependable transfer requires further decisions and connections. For an executive whose career began in software delivery, the distance between an announcement and a functioning service is familiar working ground.
Five facts before the button
Parakal’s October proposal returns to the screen the customer sees. He wants remittance providers to pilot a shared label, agree on its form and invite customer feedback. A successful pilot could inform a wider standard. The argument gives providers a first move rather than asking them simply to wait for a rule.
Before you send
- 01 Exchange rate
- 02 Applicable fees
- 03 Transfer timeline
- 04 Amount sent
- 05 Amount received
Five proposed disclosures. An editorial illustration, not a live quote or an existing industry standard.
There is commercial substance in such a modest-looking object. Put all five facts together and customers gain a common basis for comparison. A provider can still compete on price, service or delivery time. It must also make the relationship between those things legible.
That ambition fits the career. Banking apps made accounts easier to reach. Salary wallets connected earnings with payments. Travel cards made foreign-currency balances manageable. The proposed label concerns understanding the transaction before it begins. Each asks something of the institution so that the customer has a clearer next step.
Parakal’s work now spans the formal responsibilities of a regulated executive and the practical concerns of someone sending part of a salary across a border. The cereal-box comparison brings those worlds surprisingly close together. Before pressing send, a person should be able to read what they are buying. Breakfast has had enough of a head start.