A bouquet can survive a little rain. An online flower order has a harder time surviving a failed payment. At FNP, the Indian gifting retailer formerly known as Ferns N Petals, a growing collection of payment gateways had become an operational headache: unreliable routing, dropped transactions and reconciliation delays. The customer saw a checkout problem. Somewhere behind that screen, several systems were failing to agree.
Comviva was hired to untangle them. Its mobiquity One platform put a common routing and management layer between the retailer and its payment providers. FNP could keep its choice of gateways while making the checkout behave like one service. The partnership, announced in December 2024, is a useful introduction to a company whose work frequently appears under somebody else’s name.
Based in Gurugram and owned by Tech Mahindra, Comviva sells the software that helps telecom operators, financial institutions and enterprises collect money, manage customers and introduce services. Its current corporate materials report more than 200 business customers across over 100 countries. The breadth matters less than the position: Comviva works where a business’s promise to a customer must become an actual transaction.
The flowers were fine. The routing needed work.
FNP’s difficulty began with fragmentation. Adding payment choices had also added connections to maintain and failures to investigate. Comviva’s response was orchestration: one layer that could direct transactions across providers, expose performance information and centralize operations. UPI, cards, wallets and net banking remained available to the shopper.
Why choose this approach? In the published case study, FNP product head Chirantan Sharma pointed to Comviva’s neutrality and the freedom to integrate and route payments intelligently. The retailer wanted control over multiple providers. That is a specific purchasing reason, and a more useful one than a general enthusiasm for AI.
“allowing us the flexibility to integrate and route payments intelligently”
Chirantan Sharma, Product Head at FNP, on choosing Comviva
The case study reports a reduction of more than 60% in manual intervention, daily transaction value above ₹5 million and a transaction success rate above 80%. Those are vendor-published deployment results. The 80% figure is a reported success rate, not an 80% improvement; transaction value is money passing through the service, not Comviva’s sales.
One merchant’s outcome. A useful operational measure, not a promise for every deployment.
The practical lesson is to diagnose the handoffs before buying another gateway. A merchant with several providers and opaque failure reports has a plausible use for orchestration. A small shop whose single checkout already works may have little reason to introduce another system. Complexity needs to earn its keep.
A wallet that does not need your logo
Comviva’s better-established payments product, mobiquity Pay, provides the machinery for mobile money and digital wallets. A bank, telecom operator or other provider can use it to offer transfers, merchant payments and bill payments under its own brand. The software supports smartphone interfaces, QR payments and USSD, the text-menu channel that keeps services accessible beyond app-only users.
The company’s product page reports more than 500 million registered customers and annual transaction value above $500 billion. These are platform-scale claims spanning deployments, rather than a count of people who downloaded a Comviva-branded app. Registered accounts also should not be mistaken for monthly active users.
Conceptual view. mobiquity Pay and mobiquity One perform different jobs.
In Burkina Faso, Orange Money announced an upgrade to the next generation of mobiquity Pay in March 2025. The emphasis was on integrating services and bringing new products to market through an open architecture. It illustrates a recurring Comviva opportunity: improving a service that already has customers, rather than persuading those customers to adopt an unfamiliar brand.
Oman offers a different example. Global Money Exchange launched Global Pay in January 2026 using mobiquity Pay. The announced services included utility and education payments without a bank account, alongside QR acceptance interoperable with other providers in Oman. Customers could seek help at the exchange company’s branches. The app came with a human support network.
From prepaid top-ups to a ₹260 crore deal
The company began in 1999 as Bharti Telesoft. Its early world was telecom software: messaging, roaming, prepaid services and the extra features people bought for their phones. A 2002 combination with CellCloud added to that foundation; Comviva’s corporate history associates the period with PreTUPS, its electronic top-up offering.
Investors including WestBridge, Sequoia and Cisco backed the business in 2005. Contemporary reporting put the investment at $13.5 million. Management said the money would support acquisitions, product development and international expansion. This was funding for an operating software business with telecom customers, years before today’s fashion for calling almost everything a platform.
The mobiquity Money platform followed in 2007, and the Comviva name arrived in 2009. In September 2012, Tech Mahindra announced a ₹260 crore transaction for a 51% stake on a fully diluted basis. That number answers what control of the business cost in that deal. It is neither a current valuation nor a price list for its products. Comviva now describes itself as wholly owned by Tech Mahindra.
The phone bill has a backstage crew
Payments are only part of the business. BlueMarble handles business support systems, the unglamorous but consequential software behind product catalogues, orders, billing, customer records and retail operations. When an operator sells a bundle, the offer must survive the journey from a sales screen into fulfilment and billing. Every disconnected system is another place for the order to get stuck.
In February 2026, Comviva announced a unified distribution management system for Malaysia’s CelcomDigi, built on BlueMarble Retail. It consolidated legacy systems and supported sales across online, direct and indirect channels. The announcement described roughly 300-plus integration touchpoints and the onboarding of tens of thousands of partners, outlets and users.
That is a revealing measure of the work. A telecom transformation includes inventory, channel partners and people selling services far from headquarters. A polished consumer interface does not make those connections disappear. Comviva’s expertise includes fitting software into the operating arrangements a large customer already has.
MobiLytix addresses another question: once a customer is connected, what should the business offer them next? The marketing suite combines customer information, real-time decisions, campaign activation and loyalty management. Its current design includes control groups and holdouts to measure incremental impact. The useful question is whether an offer changed behaviour, rather than whether a dashboard recorded another interaction.
Selling the connection behind the connection
Comviva’s network API push extends its position between operators and enterprises. APIs let software request particular capabilities from a network. Through NGAGE.ai and a partnership announced with Aduna in November 2025, Comviva aims to make those capabilities easier for enterprises to consume across operators.
The proposed uses include identity verification, fraud checks and easier login. Aduna contributes its operator federation; Comviva contributes its communications platform and enterprise onboarding. In March 2026, Comviva also launched NGAGE for Enterprises, bringing messaging channels, network-based identity and conversational AI into a common engagement offering.
Here, the condition for success is practical. An enterprise needs the relevant network capability to be available in its markets and useful inside its existing customer journey. Standardized access can reduce integration work, but an API does not create demand by itself. The fraud team still needs a signal worth acting on.
What buyers are actually paying for
Comviva’s business model spans enterprise software deployments and services, with SaaS offerings in newer parts of the portfolio. Its published cloud material describes both capital-expenditure and revenue-sharing arrangements for mobiquity Pay. The appropriate comparison is the cost of implementing and operating a service over time, including integration, support and infrastructure.
There is a clear distinction within payments. FNP’s case study describes mobiquity One as a neutral orchestration layer, with no involvement in payment processing. In May 2026, Comviva added Unlimit as a selectable gateway within that product. The partnership gives merchants another provider option while leaving orchestration as the organizing layer.
The financial scale is more concrete than the payment-volume claims. For the year ended March 2026, Comviva reported consolidated sales of ₹16.72 billion, up 12.73%, and consolidated profit of ₹1.40 billion, up 33.27%. These are the company’s operating results, distinct from the value of customers’ transactions.
Consolidated sales. Fiscal years ended March 31. Values rounded from the FY2025-26 annual report.
Competition changes by job. Ericsson sells a carrier-grade wallet platform with overlapping mobile-money functions. Amdocs offers billing, charging and customer-management software relevant to BlueMarble’s market. Comviva’s distinguishing proposition is its combination of payments, telecom operations, marketing and communications experience. Buyers should judge that breadth against their actual integration needs, rather than assume that buying more modules produces a better result.
The next upgrade is organizational
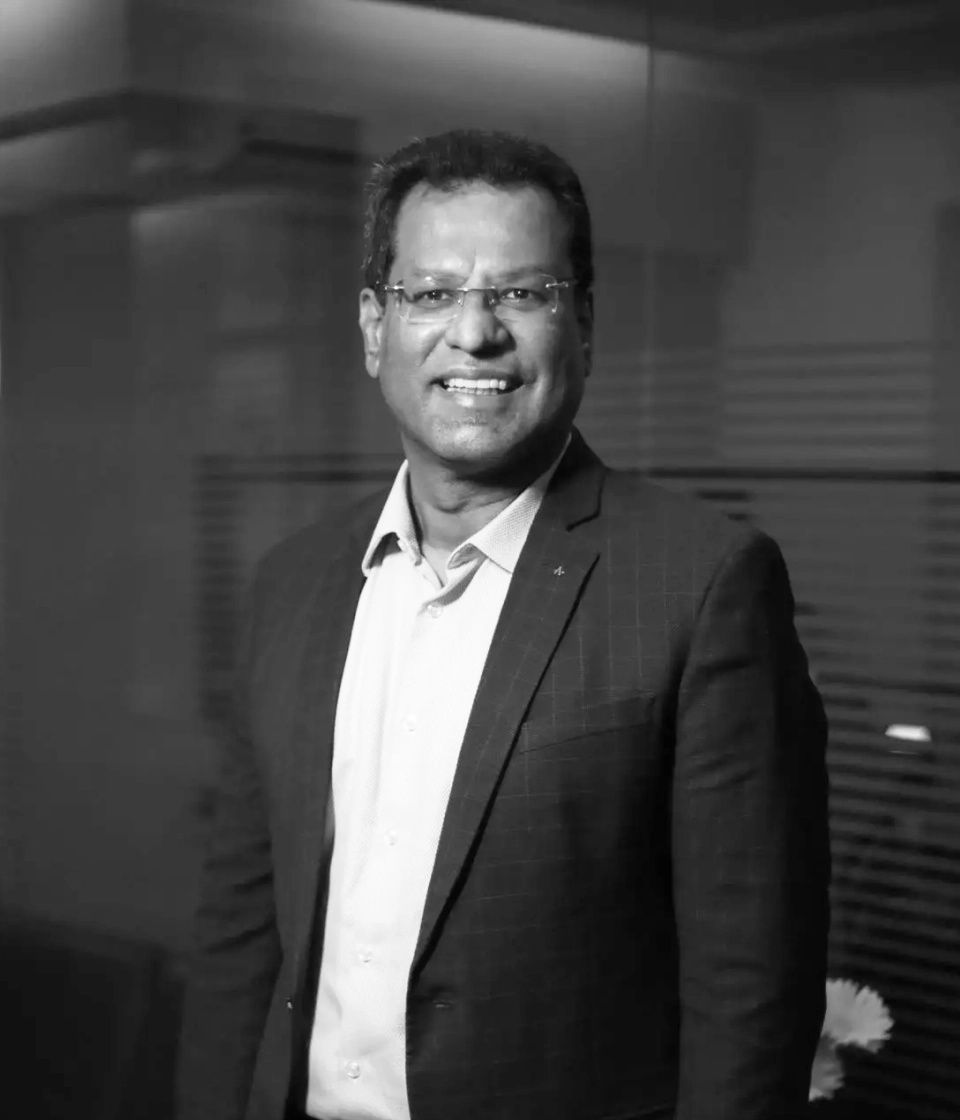
Chief executive Rajesh Chandiramani leads a workforce the company puts at more than 3,000. The careers pitch emphasizes growth and internal recognition, but the employee accounts are more revealing than the slogans. One describes an Oracle database migration executed during nights and holidays with zero data loss; another recalls building a design function from a technical documentation team. These are company-selected testimonials, with all the selection that implies.
They nevertheless describe the kind of work customers are buying: careful migration, operational ownership and the ability to make specialist systems usable. For software entrusted with payments and telecom services, the uneventful cutover is an achievement. Nobody wants their electricity bill to become an exciting technology story.
On September 8, 2026, Comviva appointed former Salesforce executive Kalyanasundaram Sivasubramaniam to lead DigiTech. His remit includes BlueMarble, expansion in North America and Europe, and further development of agentic AI capabilities. The appointment makes the direction explicit: turn accumulated telecom expertise into a broader enterprise platform business.
The FNP example supplies a sensible test for that ambition. Find a failure customers can feel. Give the business clearer control over the systems causing it. Measure the manual work, payment outcomes or delivery delays that change. The strongest argument for Comviva is the moment when the customer presses “pay” and can finally get on with choosing the card for the flowers.
Follow the transactions
Explore the products, company updates and conversations.