In suburban Michigan, Christopher Abate grew up with an expectation so ordinary that it hardly needed explaining: adulthood would eventually come with a house. Somewhere along the way, that apparently modest arrangement became a rather more ambitious proposition. The teenager became a mortgage finance executive. The house became harder to reach.
Abate recalled that childhood assumption in 2020, after he had become chief executive of Redwood Trust. Buying a house seemed like a rite of passage into adulthood.
By then he was living in California, where the price of admission could make the rite look suspiciously like an endurance event. He wrote about the rising cost of the first rung of the housing ladder, and the changing expectations of people trying to climb it.
That distance between an ordinary ambition and an increasingly expensive reality gives his work a human frame. Abate operates in a world of loan pools, capital requirements and securitizations. Its vocabulary can require a running start. The underlying question is more familiar: who supplies the money that allows somebody else to buy, improve or rent a home?
The accounting department was on the way
His route to the corner office passed through the accounts. Abate studied accounting and finance at Western Michigan University and earned an MBA from the University of California, Berkeley and Columbia University. Before Redwood, he worked at PricewaterhouseCoopers as an auditor and consultant. A 2016 company biography also identified him as a certified public accountant.
He joined Redwood in April 2006. The timing put him inside a mortgage business before the financial crisis, rather than arriving afterward with a tidy theory of what everyone should have done. He became controller in January 2009, chief financial officer in March 2012 and president in July 2016. For part of that climb, the jobs overlapped.
Those titles describe a progression from recording the business to financing it to directing it. They also explain why his professional biography reads differently from the familiar founder narrative. Redwood already existed. His task would become deciding how an established company should change when the market around it kept changing the terms.
In December 2017, Redwood announced that he would succeed Marty Hughes as CEO the following May. Abate joined the board that December. Dashiell Robinson was named in the succession announcement as the incoming president. Abate spoke of the pair sharing a strategy that would build on Hughes’s work while responding to shifts in housing.
The mortgage behind the mortgage
Understanding Abate requires a brief visit to the less visible end of the housing business. A borrower sees a lender, an application and a monthly payment. Behind that transaction sits another set of decisions: who will own the loan, who will finance it while it is held, and who will take its risks?
Redwood works in that second world. Its Sequoia business buys residential loans from originating lenders and distributes them through loan sales and mortgage-backed securities. Pooling loans into securities connects mortgage credit with investors willing to fund it. The process can free a lender’s capital for another round of lending. In an interview in 2023, Abate described this role as a private-sector counterpart to functions performed by government-sponsored mortgage enterprises.
The distinction matters when a mortgage falls outside the channels served by government programs. Redwood’s business is organized around those openings. Prime jumbo loans are one example. Loans for residential property investors are another. Different borrowers need different kinds of capital, and the investors supplying it have preferences of their own.
Abate has experienced how abruptly those connections can strain. Describing the March 2020 market disruption in a later interview, he drew a distinction between support for agency mortgage securities and the conditions facing jumbo and other non-agency products. Redwood subsequently returned to issuing securities. His account treated dependable access to loans and dependable access to investors as complementary parts of the same business.
There is an unromantic quality to that ambition. Reliable financing rarely receives applause when it works. People tend to notice the plumbing after the tap stops running.
A $490 million turn toward the landlord
In October 2019, a little over a year into Abate’s tenure as CEO, Redwood agreed to acquire CoreVest. The consideration was approximately $490 million, net of financing already in place on the assets. The transaction included the operating business and more than $900 million of related financial assets.
CoreVest brought a different customer into sharper focus: the residential real estate investor. Its lending served rental properties, bridge financing and smaller multifamily investments. Redwood was broadening the ways it could participate in housing, adding direct lending to property investors alongside its consumer mortgage activities.
The distinction between the individual homeowner and the property investor was one Abate addressed explicitly. In 2023, he explained that Redwood had historically preferred to avoid directly offering products to consumers, while being comfortable lending to investors operating businesses. He also said the company had become more open to considering consumer origination through acquisitions.
Read together, those decisions show the practical boundary work of running a finance company. Expansion changes the customer, the regulatory responsibilities and the risks. Buying a platform gives the chief executive more to operate, as well as more assets to own. Under Abate, that operating component has become central to Redwood’s strategy.
Banks can be partners, too
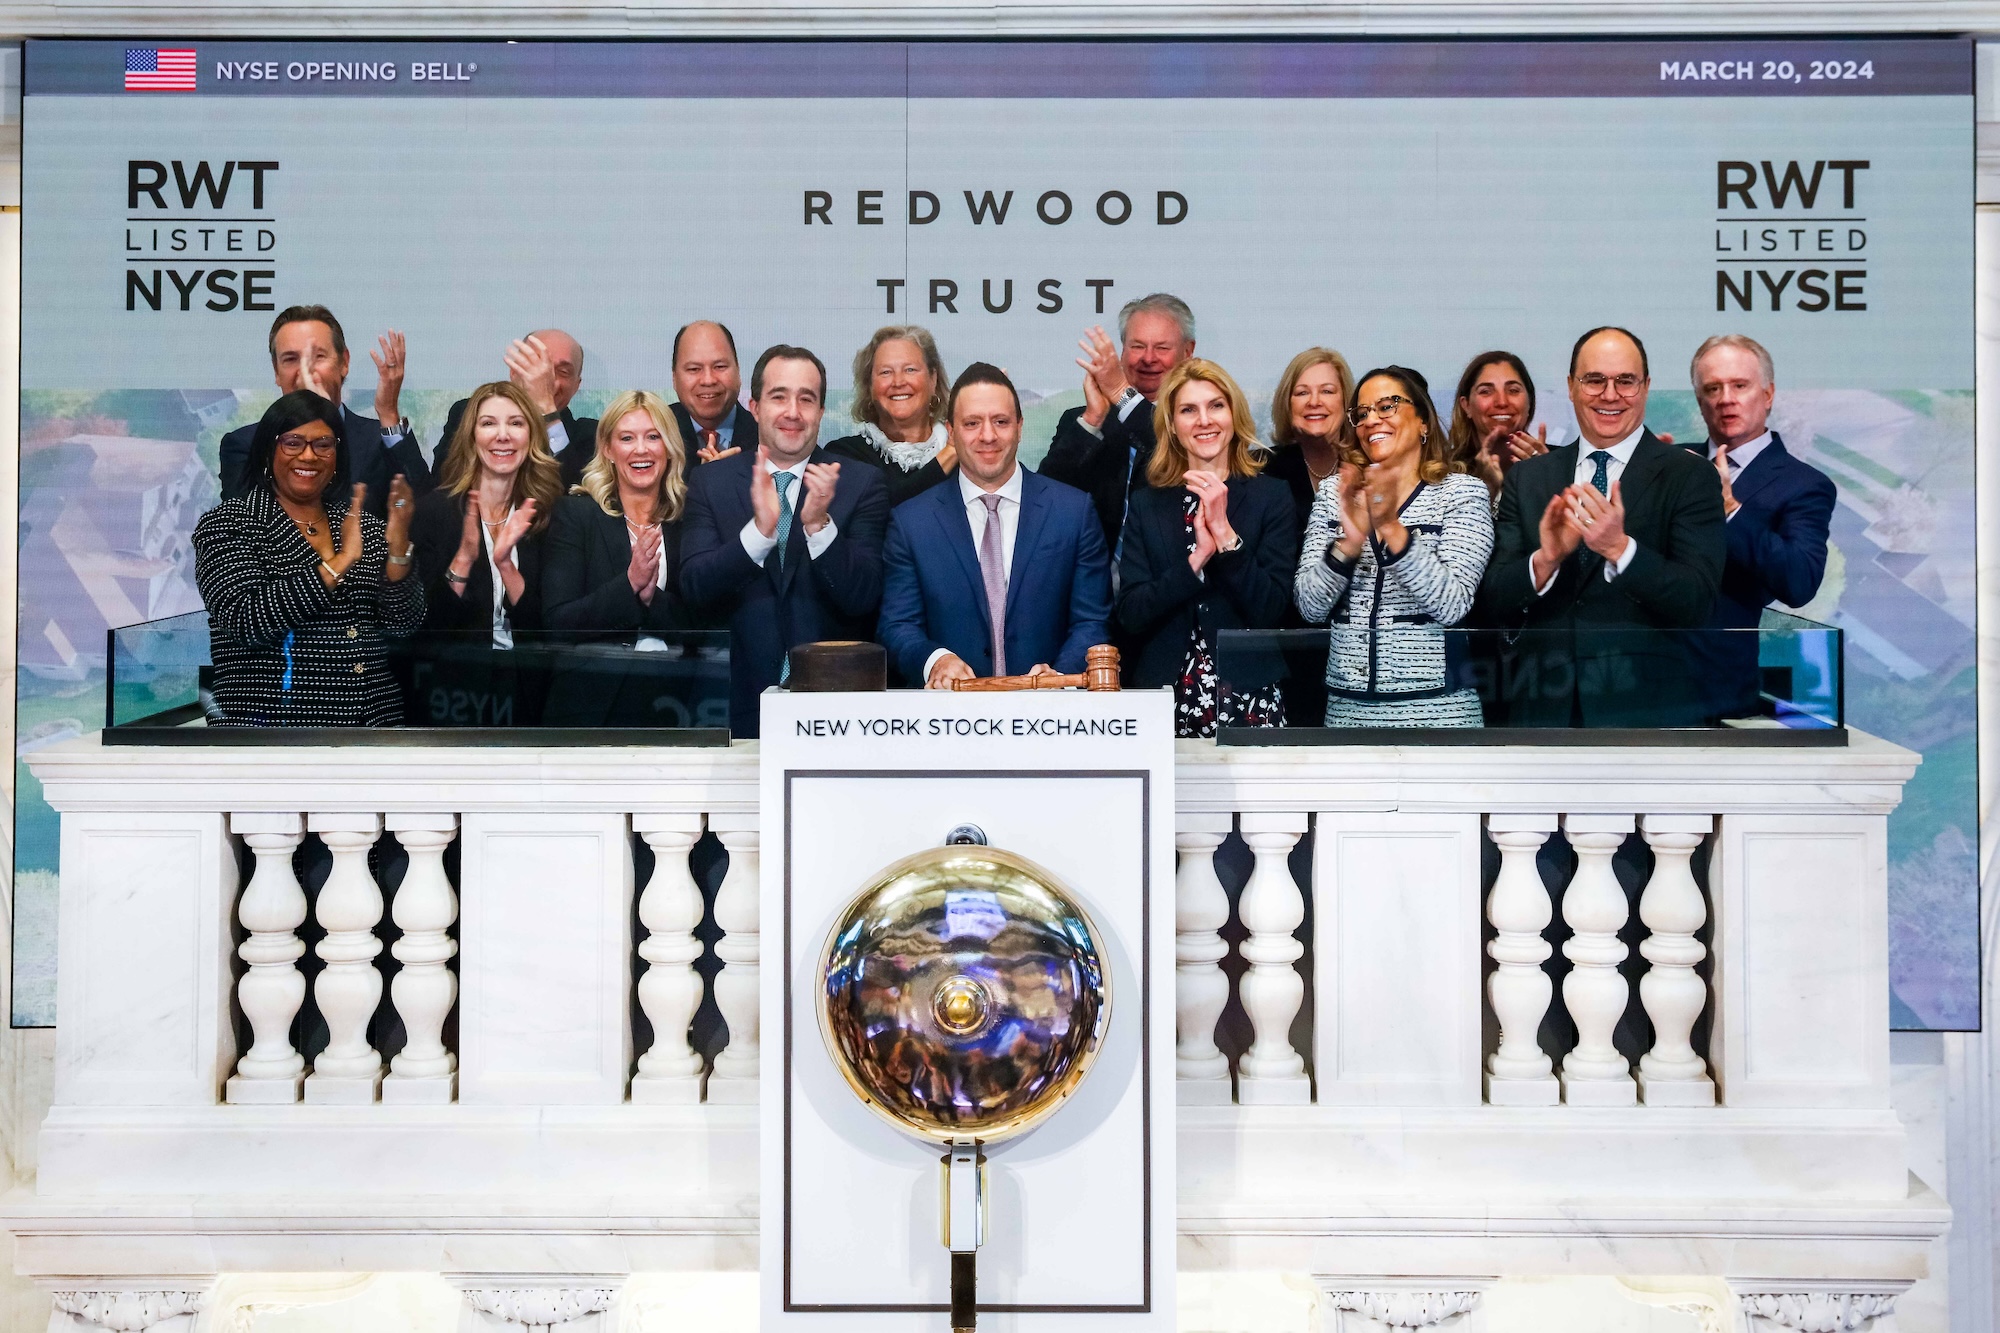
By 2024, Redwood’s investor-day agenda was giving bank capital needs and private credit partnerships prominent billing. Abate opened the March event with a presentation called To Own RWT. The next day, he rang the opening bell at the New York Stock Exchange with colleagues celebrating the company’s 30th anniversary.
The celebration came with a substantive financing announcement. Redwood and CPP Investments established a $750 million strategic capital partnership, comprising a $500 million asset joint venture and a $250 million financing facility. The venture focused on residential investor loans from CoreVest. Redwood could earn fees from administering the assets as well as participate in the investment.
Bank regulation also drew Abate into direct policy discussions. In October 2024, he and Redwood director Armando Falcon met Federal Reserve staff to discuss proposed credit risk capital requirements. His public arguments about mortgages were accompanied by meetings about the rules governing who could economically hold them.
His position allows room for banks as well as private capital. In a 2026 interview, he welcomed banks’ participation in mortgage lending, including the consumer relationships and local branches they bring. He described rationalizing capital charges as the starting gun rather than the finish line.
Lenders, he argued, also need confidence that the rules will remain sufficiently predictable to build businesses around them.
That is a useful complication in the story of a nonbank executive. A bank can originate a loan that Redwood buys. It can also buy a loan Redwood distributes. A counterparty need not spend its entire life on one side of the table.
More loans, more exits
In April 2026, Redwood announced another route for its loans: a Castlelake joint venture contemplating purchases of up to $8 billion of prime jumbo mortgages through Sequoia. The figure described intended purchasing capacity, rather than completed purchases. Sequoia would source, aggregate and review loans against agreed eligibility criteria.
Aspire, meanwhile, had expanded into non-QM correspondent lending in 2025. In a LinkedIn post celebrating its inaugural securitization in 2026, Abate emphasized responsible growth and credit quality. By July, Redwood was describing proprietary AI tools for pricing and comparing underwriting guidelines. These were specific applications inside the process of evaluating and distributing loans.
The partnership announcements and the software address different constraints. External capital can support more business without requiring Redwood to supply every dollar itself. Better processing can help staff handle that business. Both support the move toward earning more from operating platforms, a strategy Abate has repeatedly put before shareholders.
“We generated more than $8 billion of mortgage banking production while continuing to prioritize profitability over headline volume.”
Christopher Abate, July 2026
The accountant still has to count
Growth leaves an obvious temptation: select the largest number and let it do the talking. Redwood’s second-quarter 2026 results require a longer look. Its mortgage banking platforms generated $40.1 million of GAAP net income. The consolidated result was a loss of $0.03 per common share, and book value per common share fell from $7.12 to $6.90.
Redwood also reported $0.15 per share in non-GAAP earnings available for distribution and $0.25 for its core segments on that measure. Those figures cover different scopes and adjustments. They cannot be exchanged casually for consolidated accounting earnings. The operating business can improve while other holdings and costs continue to weigh on the total.
Different scopes, same quarter. Platform earnings do not equal the consolidated result.
This is the unresolved part of Abate’s project. He is seeking a company whose operating platforms generate a larger share of earnings, while managing the investments and obligations accumulated along the way. The qualification belongs beside the ambition. A faster production line does not settle every item on the balance sheet.
The next house is still the point
On October 13, 2026, Abate said Redwood had distributed more than $8 billion of mortgage loans during the third quarter and ended September with approximately $190 million in cash and equivalents. Full quarterly results were scheduled for November 3. Distribution, in this update, was the completed activity being described; it was not a claim about final quarterly profit.
Twenty years after joining Redwood, his work still involves moving between household expectations and institutional arithmetic. The Michigan teenager’s assumption supplies the purpose. The accountant’s training supplies a demanding test of the means. Between them sits a business that must persuade lenders, investors and shareholders that the next home can be financed on terms worth accepting.