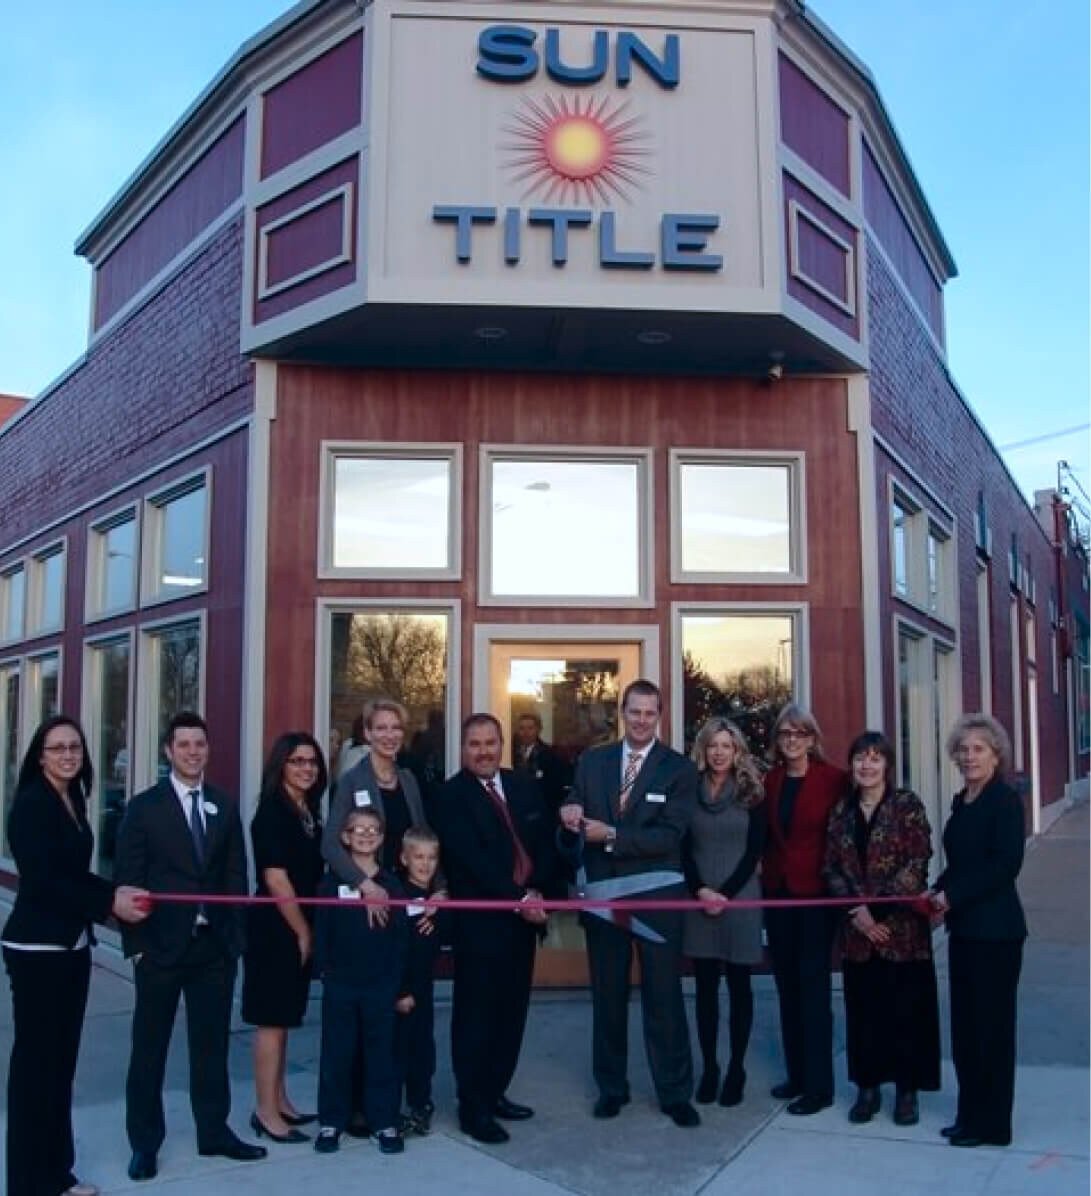
The wire looked ordinary. That was the problem. In 2015, an employee at Sun Title, a title agency in Grand Rapids, Michigan, sent $180,000 to a fraudulent account. The money had been steered away by a social-engineering scheme elaborate enough to play out over weeks. For owners Tom Cronkright and Lawrence Duthler, it was not a suspicious login on a dashboard. It was payroll, reputation and the possible end of the company they had spent a decade building.
They discovered the second failure immediately: there was no red emergency box to break. Banks, state authorities and federal agencies offered no simple recovery path. Cronkright and Duthler spent two years pursuing the crime through civil litigation. Cronkright eventually testified before the U.S. Department of Justice. They recovered 78 percent of the money, an impressive result that still left a punishing bill in time, legal work and nerves.
The expensive callback
The old defense against a changed wire instruction was reassuringly human: call a known phone number and confirm it. Then criminals learned to compromise inboxes, spoof numbers and impersonate the calm voice on the other end. Sun Title saw more attempts and a couple of near misses. The founders began building an internal app, then recruited Tyler Adams, a product builder who had worked at BCG Digital Ventures, to turn that defense into enterprise software. The three incorporated CertifID in 2017.
The product attacks a narrow, expensive moment. Before money moves, CertifID checks identity, device, geography and bank-account information. Its risk analysis uses more than 150 fraud markers. Buyers can receive protected wire instructions; sellers and other payees can submit bank details; title teams can validate mortgage payoff destinations. The workflows sit inside title-production systems including SoftPro, ResWare and RamQuest, where a closer is already working.
That sequence is the useful difference. A generic identity vendor may return a score. A cyber policy may reimburse a covered loss after an investigation. A bank may try to recall a wire. CertifID bundles the decision, the financial backstop and the humans who know which calls to make when minutes matter. Its insurance is direct and first-party, meaning the customer is the insured party rather than a hopeful beneficiary of the vendor's own policy.
“There was no clear process for recovering this kind of loss.”Tom Cronkright, co-founder and executive chairman
A score with consequences
This is not a consumer password app. CertifID sells B2B software to title companies, law firms, lenders and underwriters, while buyers and sellers experience it through a closing. Core pricing is not posted; it is generally per file, based on transaction volume, with custom enterprise plans. The insurance is included with qualifying verified transactions. One newer product does carry a public number: Cash to Close costs the buyer a flat $48 and promises an insured payment arriving the next business morning when submitted before the cutoff.
The customer list ranges from local settlement shops to Stewart Title and Independence Title. The pitch is easy to understand after a close call: replace scattered callbacks and emailed instructions with a recorded workflow, then reduce the argument about who bears the loss. In 2024, CertifID said 65 percent of its customers encountered at least one transaction flagged as suspected fraud. Once a title company sees the first red alert, the security budget tends to become less theoretical.
The market around it is awkwardly split. Email-security vendors defend the inbox. Identity companies check the person. Payment companies move the money. Title-production software manages the file. Insurers price the residual risk. CertifID sits at the seam and argues that a closing fails when those responsibilities are treated as separate errands. That positioning is attractive to an enterprise buyer that wants one accountable vendor, but it also sets a demanding standard: the platform has to make several specialists work like one service without slowing a deadline-driven transaction.
The reported scale is substantial, but the numbers deserve their proper label: they come from CertifID's own transaction analysis and recovery operation, not audited financial statements. The company says it safeguards billions of dollars each month. It also says PayoffProtect has passed one million protected mortgage payoffs, covers more than 5,000 lenders and verifies 97 percent of payoff instructions, with a team handling the leftovers.
The payoff is the painful one
Average losses reported to CertifID in 2024The fraud checkpoint wants the whole closing
CertifID's first wedge was certainty at the instant of a wire. Its newer moves reach earlier and later. A $12.5 million Series A in 2022 funded payoff protection and recovery hiring. A $20 million Series B followed in 2023. In January 2025, CertifID acquired Paymints.io, adding digital payments. Six months later, Centana Growth Partners led a $47.5 million Series C, with Arthur Ventures participating again. The money was earmarked for identity, transaction monitoring, payments, partnerships and staff.
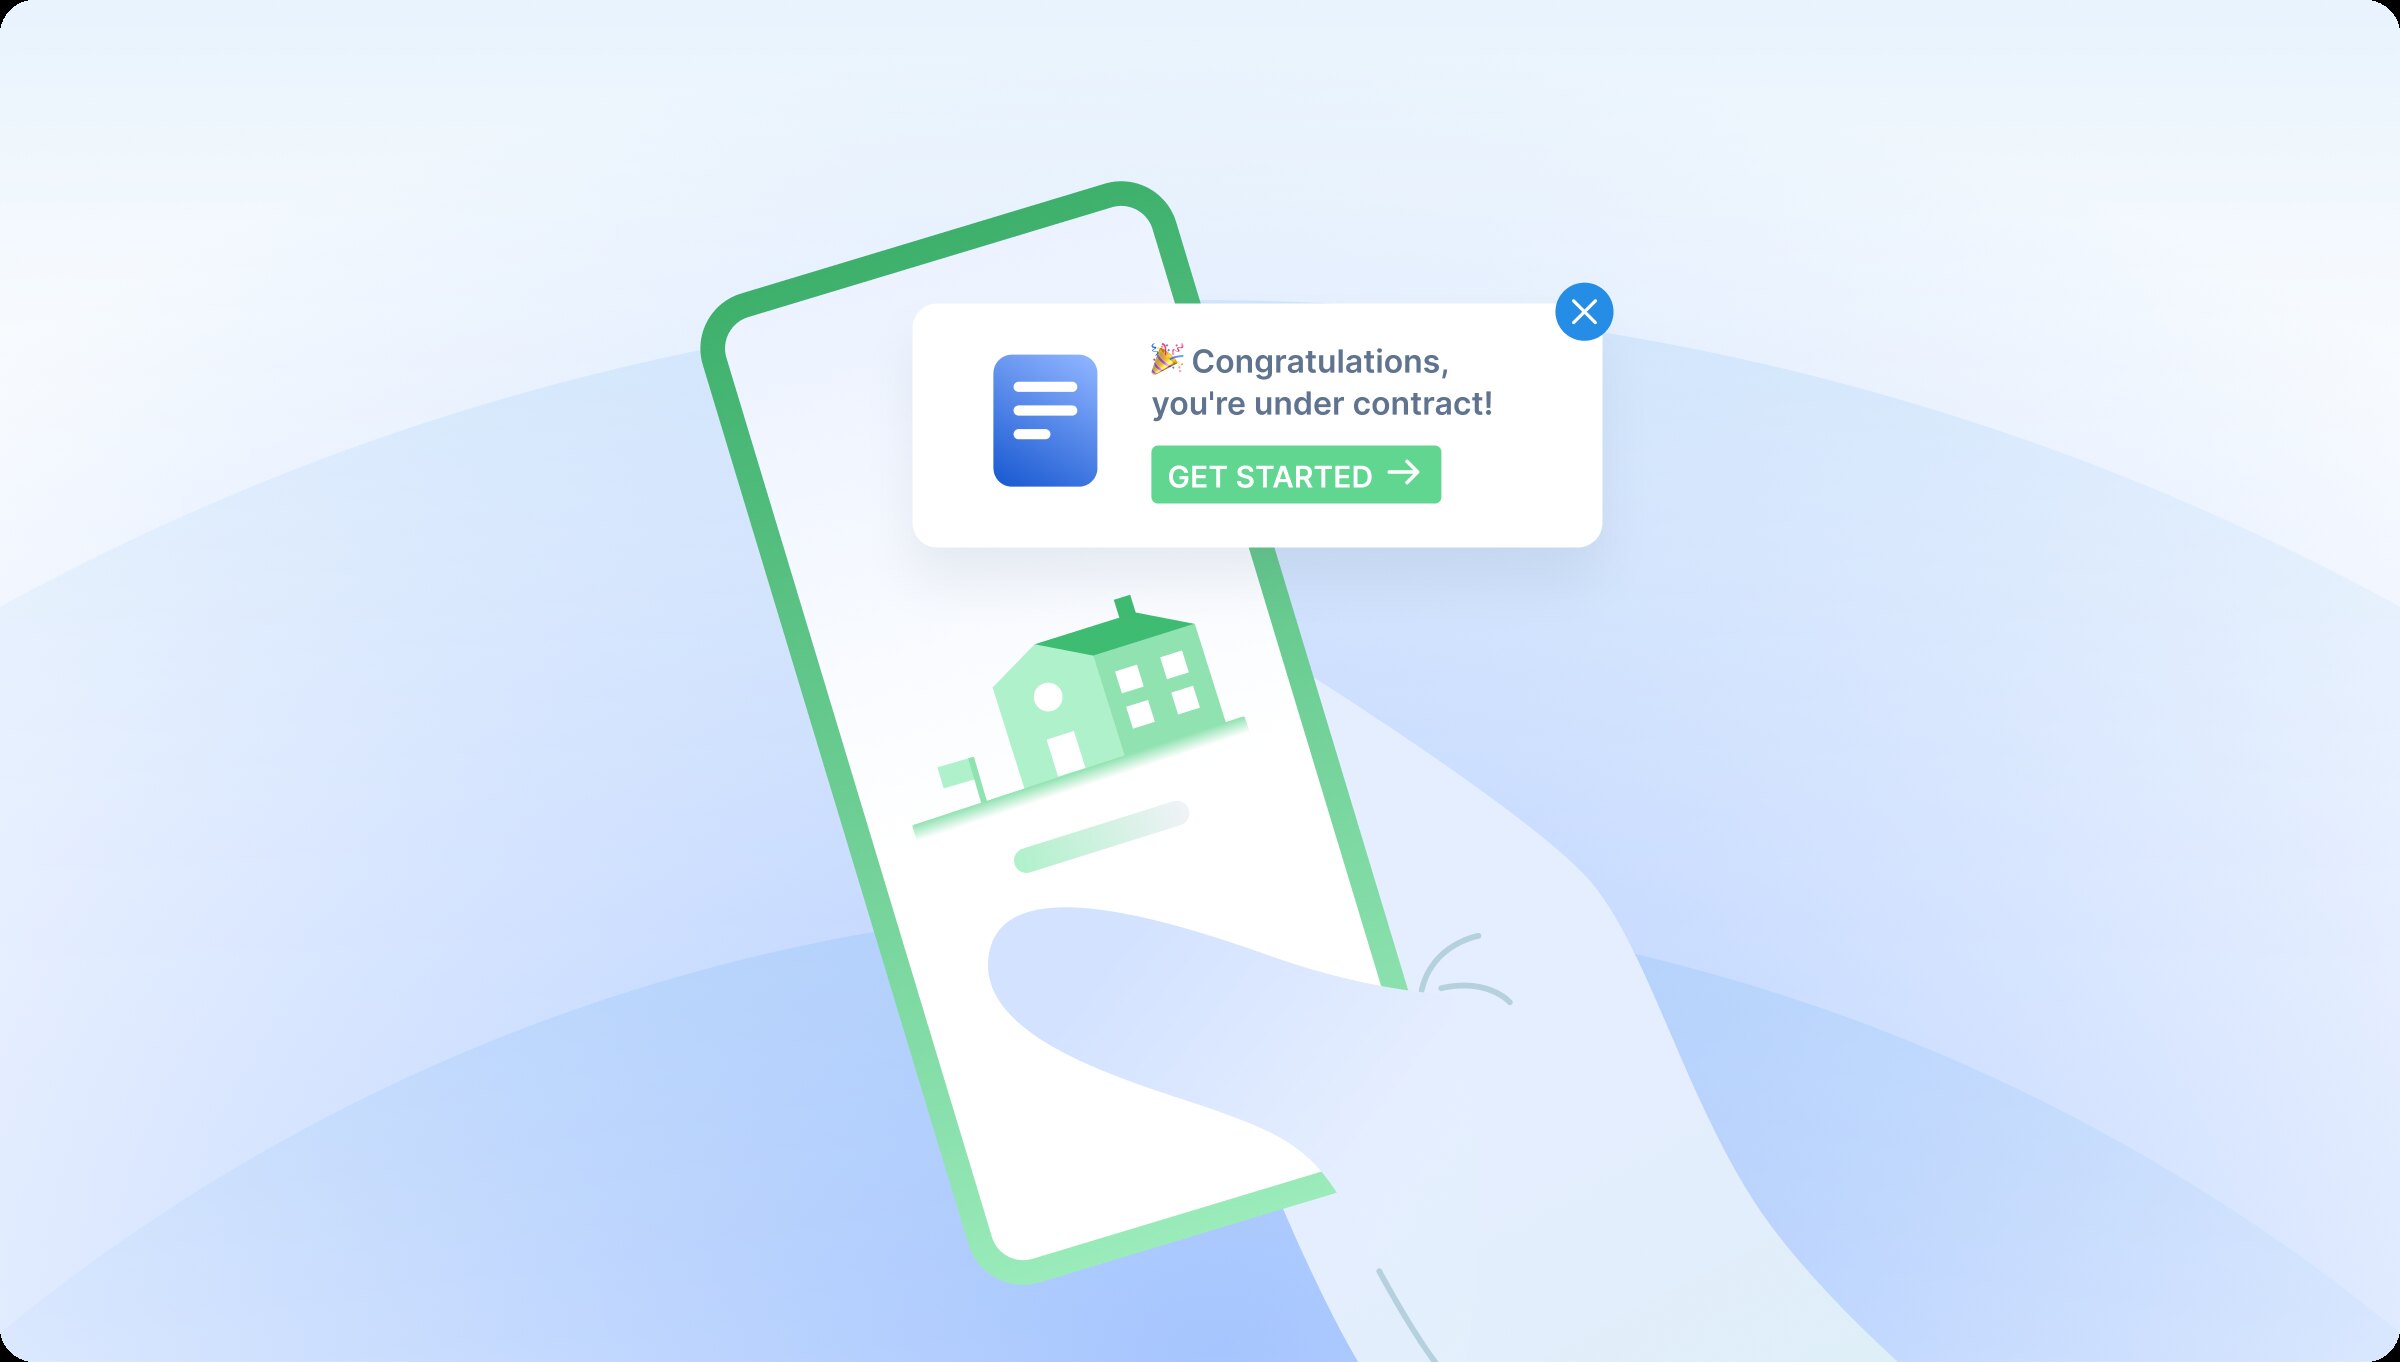
In 2026, the company launched a client experience that puts identity checks, documents, signatures, payment and progress in one guided workspace. There is no app to install; participants enter by one-time code or magic link. Title teams get a view of incomplete tasks. A paid white-label version lets firms use their own branding. Then CertifID acquired CloseSimple, whose specialty is automated closing communication and branded client portals. CloseSimple remained a separate platform in the near term, but the strategy was plain: make the secure path the whole path.
That expansion changes CertifID's market position. It still competes with focused fraud products such as ClosingLock, FundingShield and Qualia Shield. But it increasingly overlaps with payment tools, closing portals and workflow software. The risk is familiar to every focused SaaS company that broadens: more surface area can make a product more useful, or make the original sharp edge harder to see. The CloseSimple integration will be an early test.
What a title shop can copy
The easiest lesson is not “buy more AI.” It is to remove discretion from the dangerous step. CertifID's integrations matter because a verification rule inside the file is harder to skip than a policy in a binder. Separate the source of wire instructions from ordinary email. Verify both the human and the destination. Keep a documented result. Decide who calls the bank and law enforcement before a crisis. Know the insurance terms before assuming that a vendor's coverage protects you.
The founders also copied their own scar tissue. The first product was not invented in a workshop; it was used internally against repeated attacks. The recovery service exists because their first loss revealed that prevention eventually fails. The insurance exists because a green check without financial accountability is only advice. Each layer answers a specific thing that broke.
Where the model stops
- CertifID does not stop the phishing email that begins a business-email compromise. It tries to stop the intruder from redirecting funds.
- Protection depends on the transaction using the platform and meeting the insurance policy's terms. An off-platform wire is still an off-platform wire.
- The fit is strongest in high-value U.S. real-estate closings. Low-value person-to-person payments and unsupported international workflows need a different tool.
- Some flows require both a phone number and email, and quote-based pricing adds a sales step. Small firms must weigh that friction against their volume and exposure.
Grit, with a claims process
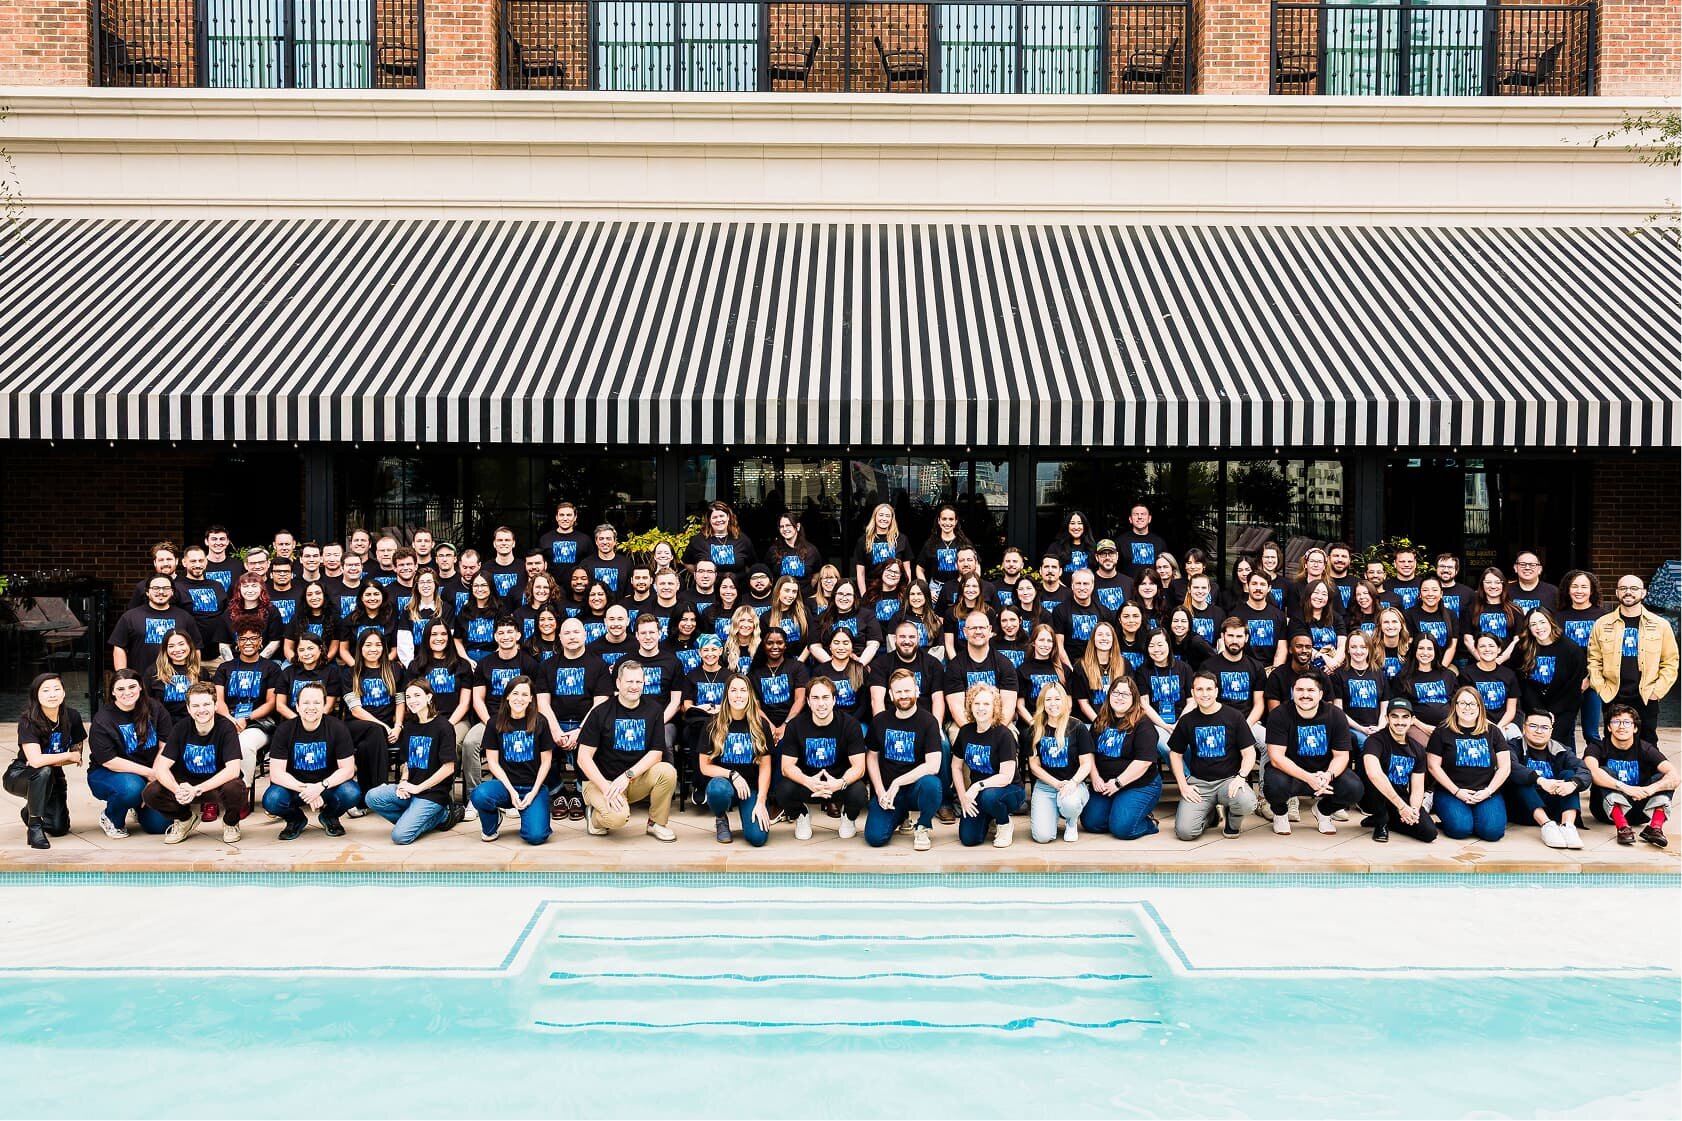
CertifID packages its culture as GRIT: guard the customer, raise the bar, influence outcomes and teamwork wins. It earned Inc. Best Workplace recognition and appeared on the Inc. 5000 in 2023, 2024 and 2025, ranking No. 1,911 in 2025 with 228 percent three-year growth. The slogans are less interesting than the operating demand underneath them. Fraud recovery is not a feature that can close a ticket at five o'clock. The customer on the phone may have lost the proceeds from a house.
The company now has roughly 150 employees and offices in Austin and Grand Rapids. Its stated vision is “a world without wire fraud,” which reads grandly beside a threat that mutates for a living. A more concrete measure is whether title workers stop sending anxious callbacks, buyers stop wondering which email to trust, and fewer life-changing payments reach the wrong account.
CertifID began because an ordinary process failed in an extraordinary way. Nine years later, it is trying to turn the closing itself into the control: one place, known participants, verified instructions, insured movement and a recovery number that somebody answers. The most useful part of the story is not that pain created a company. It is that the founders kept asking what failed next.