A house can make its case in seconds. There is a window, a kitchen, perhaps a patch of garden large enough to justify buying an unnecessarily ambitious lawn mower. A mortgage makes its case rather less elegantly. There are terms to decipher, numbers to reconcile and an application that can turn a promising Saturday into an administrative occupation. Brian Faux built part of his career around the distance between those two experiences.
Faux is Morty's co-founder and founding CEO, a mortgage industry veteran who brought lending and public policy experience into a company built to make financing easier to compare. His story runs through traditional lending, the aftermath of the housing crisis, a New York startup and, more recently, federal housing policy again. The setting changes. The underlying transaction remains stubbornly consequential.
The interesting part is his vantage point. Faux had worked with borrowers, held an operating role at a national lender and served as a senior adviser at the Federal Housing Administration. He approached the mortgage process with experience of the institutions responsible for making it work. That gives his founding story a different texture from the familiar tale of a newcomer discovering an industry's irritating habits.
An insider learns where the friction lives
Before Morty, Faux was chief operating officer at 1st Alliance Lending. His professional background also includes Wells Fargo and Freddie Mac. Those names place him in several parts of the housing finance business, from a lending operation to an institution central to the mortgage market. They help explain the breadth of the experience he brought to the founding team, without turning a résumé into a claim that any one person understands every borrower.
His earlier HUD work came in the period following the 2008 housing crisis. By October 2012, his official portrait identified him as a senior adviser at FHA. In February 2013, consumer advocates addressed him in that capacity about the agency's single-family loan sales. Their questions concerned what happened to loans after a sale and whether investors' incentives would keep homeowners in their homes.
That correspondence captures the unglamorous seriousness of housing policy. A program has a name and a rationale; families experience its consequences. The letter does not supply a tidy success story. It shows Faux working where policy needed explanation, evidence and continued discussion. Long before a borrower could click through a Morty application, he was involved in conversations about what the mortgage system did after things went wrong.
The engineers meet the mortgage veteran
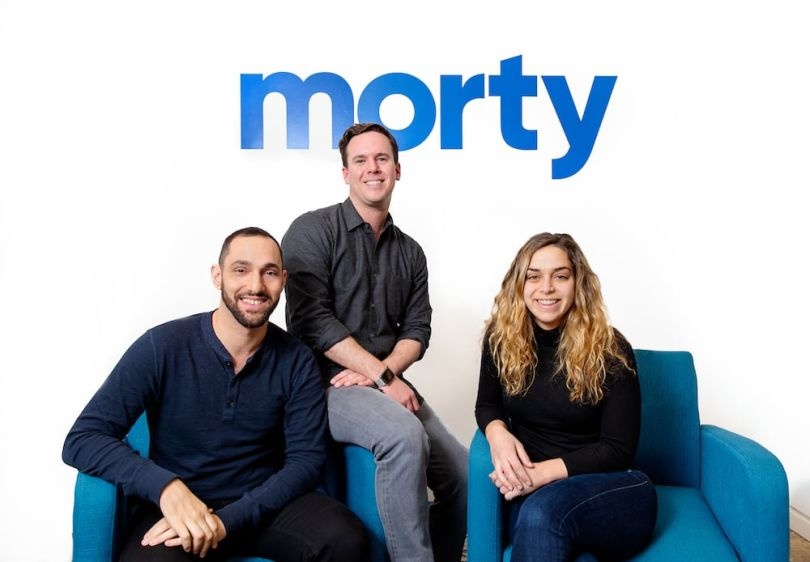
Morty's founding brought together people with different professional languages. Nora Apsel came from software engineering. Adam Rothblatt had worked in algorithmic trading at Goldman Sachs. Early reporting also identifies Sarah Thomas among the co-founders. Faux supplied experience of lending and housing policy. This was a collaboration between people who could build software and someone who had spent his working life around the transaction it would have to support.
The company appeared on the industry stage before its public launch. In 2016, Faux was listed as Morty's CEO and co-founder on an Urban Institute and CoreLogic symposium panel. Alongside him were Quicken Loans CEO Bill Emerson, CoreLogic's Jordan Petkovski and lawyer Larry Platt. The session considered how technological convenience could coexist with safety, soundness and a borrower's understanding of a long-term commitment.
That is a useful scene for understanding his place in the story. Morty was a young entrant, but the discussion was already about the constraints around the screen: regulation, execution and the practical work of making a loan. The browser could be friendly. The machinery behind it still had to function. A mortgage does not become simple merely because its buttons have acquired rounded corners.
A marketplace, with the banks still in the picture
At its public launch in 2017, Morty had raised a $3 million seed round led by Thrive Capital. Participants included SV Angel, FJ Labs, Corigin Ventures, MetaProp and Techstars. Launch coverage described ten major lenders participating across ten US markets. The proposed change was in how buyers reached and compared their financing options.
Faux used travel comparison as an analogy. Consumers had become accustomed to shopping across options online; arranging a mortgage still involved a less convenient process. Morty aimed to bring a similar ability to compare to home financing. The comparison was easy to grasp, though an airline ticket and a mortgage plainly ask different things of their buyers.
The company worked with lenders rather than requiring every part of the lending system to be recreated. Faith Schwartz, who moderated the 2016 symposium, described the importance of lenders' funding capacity even as technology companies changed the customer experience. Her account placed Morty within that evolving relationship.
For Faux, the entrepreneurial move meant applying industry experience to the point where a buyer encountered it. Institutions could continue to supply the capital. A different interface and workflow could change how a household navigated the choice. That is a more practical proposition than imagining that a website alone can abolish complexity.
The introduction that followed a rejected deal
One small story about Morty's financing has little to do with mortgage rates. Investor David Goldberg described how his team had considered another startup, Datavore, and ultimately passed. Its founder, Jake, nevertheless appreciated the process and introduced the investors to Faux, seeing a fit between Morty and their investment thesis.
Goldberg presented the introduction as evidence that how investors treat founders matters even when they do not invest. For a profile of Faux, it also supplies a glimpse of the social plumbing behind a funding announcement. The eventual meeting began with someone else's unsuccessful pitch.
The anecdote is modest enough to be believable and specific enough to be memorable. Startup accounts tend to compress fundraising into a sum, a date and a roll call of firms. Here, a relationship survived a rejection and produced a connection for a different company. There is no need to invent an extraordinary networking talent for Faux. The observable fact is more interesting: an introduction reached him because another founder thought there was a useful match.
A number on a screen is still a question
Faux's consumer advice in 2019 was notably attentive to the limits of comparison. He encouraged buyers to understand their financial situation and the loan types they qualified for before comparing offers. He also pointed to the fees that could make a low interest rate less attractive than it first appeared. A tidy ranking can conceal an untidy difference.
His warning about online rates was equally direct. A rate displayed on a search page could be mistaken for an offer that the borrower was guaranteed to receive. The distinction matters to his founding thesis: making information visible is only part of making it useful. The buyer also needs to understand what that information represents.
“Each site offers something a little different,”
Brian Faux, 2019
There is a restrained quality to that advice. The person building a comparison business was asking people to do some homework before comparing. It is an acknowledgement that software cannot supply every piece of judgment a transaction requires. The challenge for a product like Morty was to reduce unnecessary effort while leaving the meaningful decisions legible. A borrower should not need an honorary degree in acronyms simply to ask a sensible question.
Growing the map, keeping the question
By August 2019, Morty's announcement described service across 34 states and Washington, D.C., thousands of homebuyers helped and more than $11 million raised since its public launch. An $8.5 million Series A backed the expansion, led by Prudence Holdings with investment from Thrive Capital and Lerer Hippeau.
The new platform focused on questions people asked before they could confidently bid: how much house could they afford, and would they be able to get a mortgage? Those are less glamorous than the final exchange of keys, but they shape everything that comes before it. The company said its platform could support closings in as little as two weeks. That was a stated capability, rather than a promise that every buyer would finish on that timetable.
“We started Morty to build transparency,” Faux said at the time.
As a description of purpose, it is admirably concrete. Transparency can sound abstract until a buyer needs to know whether an attractive house is actually within reach. Morty's expansion made the same questions available to more people. The figures describe the company's progress during Faux's founding leadership; they are not a measure of his personal wealth or a substitute for the experience of an individual borrower.
Speed is only one part of the job
At a 2017 fintech panel, Faux spoke about efficiency extending beyond the time it took to close. “The actual process of getting a mortgage is much more efficient,” he said. His point concerned the work involved in producing a loan as well as the experience at the consumer end.
A year earlier, he had joined a discussion in which appraisal delays were a central concern. Faster technology at one stage could still encounter a bottleneck at another. That is an operational view of innovation: the final result depends on several participants, and a gain at the beginning does not automatically move the whole transaction at the same pace.
His public appearances also included a February 2019 personal finance podcast on choosing a mortgage, with discussion topics spanning preparation, the mortgage process and the earlier crisis. In June that year, he was advertised on a panel about choosing and integrating marketing technology. Together, these appearances show the range of subjects a founding mortgage executive had to address. There was the buyer's understanding, the lender's workflow and the company's ability to reach people who needed its service. Even an elegant product requires someone to explain where it fits.
- LendingCOO, 1st Alliance Lending
- 2012-2013Senior adviser, FHA / HUD
- 2016-2019Morty's founding CEO in public appearances and launch coverage
- 2024-2026Director, Single-Family Program Development, HUD
Back among the rules
The subsequent career chapter brings Faux back to government. A 2024 federal notice identified him as director of HUD's Office of Single-Family Program Development. A September 2024 housing counseling conference listed him in a discussion of affordability and emerging housing models, including the financing of accessory dwelling units. The questions had widened from how to compare a loan to how housing policy could accommodate different ways of providing homes.
In May 2026, he was named as the contact on an FHA request for information about minimum property requirements. The agency was seeking market feedback to inform policy modernization. The subject was again the practical relationship between a rule, a property and a mortgage. His role placed him inside the system's current policy work.
Morty, meanwhile, now names Nora Apsel as CEO and describes its evolution into a platform powering independent mortgage businesses. Faux's founding title belongs to a particular chapter. Keeping that chronology clear makes his story more interesting: lending experience, federal policy, company building and further policy work form a career with several vantage points.
The question under all of them remains plain enough for a kitchen table. Can a person understand the transaction that will help them buy a home? Faux's career offers several attempts to make the answer easier. The kitchen may sell the house. Someone still has to make sense of the paperwork.