A bank has at least two front doors. One has opening hours, a handle and somebody on the other side. The other fits in a pocket. Brent Tischler’s career has repeatedly brought him to the space between them, where a convenient transaction can become a complicated conversation and a customer expects the bank to keep up.
In 2016, Associated Bank put its retail operation in the hands of an executive who had been working on the routes customers used to reach it. Six years later, Old National appointed him CEO of Community Banking. The progression is worth a closer look. A specialist in channels had become responsible for much of what came through them.
Tischler is based in Milwaukee. His remit at Old National includes consumer and business banking, home and consumer lending, payments, product management and banking centers. Those responsibilities bring the screen, the product and the person into the same management conversation. Somewhere in that conversation, a customer would quite reasonably like to get on with the rest of the day.
Before the bigger title, the smaller frictions
His education took him through Indiana University’s Kelley School of Business and an MBA at the University of Chicago Booth School of Business. Earlier in his career, he was a senior manager at Deloitte in Chicago. Consulting and banking appear together in his background, a useful combination for a career that would increasingly concern how an organization works across its internal boundaries.
He joined Associated in 2010. By April 2011, he was senior vice president and director of channel optimization. In February 2014, he became executive vice president and head of payments and direct channels. The titles are dry enough to require a glass of water. The subject underneath them is familiar: the paths money takes, and the paths people take to manage it.
Channel optimization belongs to the institutional vocabulary. From the customer’s side, the questions are shorter. Can I do this online? Will somebody explain it? Must I start again when I visit a branch? Tischler’s sequence of jobs placed those different forms of access within an expanding set of responsibilities. In June 2016, that set became retail banking.
- 2011Channel optimizationAssociated Bank
- 2014Payments & direct channelsAssociated Bank
- 2016Retail bankingAssociated Bank
- 2022Community Banking CEOOld National Bank
The branch still had a part to play
The promotion covered consumers and small businesses, retail branches and remote channels. David Stein, then Associated’s head of consumer and commercial banking, credited Tischler with shaping the bank’s non-branch strategy. Putting that executive in charge of retail gave the assignment an interesting symmetry: the person working on alternatives to the branch would also oversee the branch experience.
By 2018, Tischler was describing digital adoption rising while visits to Associated’s branches declined modestly. He also described investment in branches, including tools and employees to help customers use digital services. There was an ordinary practical logic to it. A branch could teach customers how to do something they might later complete without entering the building.
A short observation about the human touch became a demanding operating brief. Availability means little if the person who answers cannot help. Convenience means less if a customer gets stuck. His comments placed staff and digital tools alongside each other, with the customer’s problem providing the reason for both.
“That human touch is something you can’t replace.”
Brent Tischler · 2018
Two forms of access within one retail banking brief. A conceptual diagram, not a measure of usage.
A loan application moves onto the website
In July 2021, Associated announced personal loans powered by Upstart’s digital lending platform. The partnership had begun that February. Customers could access the product through the bank’s website, bringing a specific borrowing task into the digital experience. Tischler, still leading retail banking, spoke about making the borrowing process faster and more convenient for the communities the bank served.
The announcement described an ambition to approve more borrowers while remaining within the bank’s risk parameters. That qualification belongs in the story. Access and credit judgment have to coexist. A simpler application is useful, but a bank still has to decide what it can responsibly lend. Tischler’s public comments connected the technology to that everyday consumer task.
Consider the difference between announcing a digital strategy and putting a particular product on a website. The second gives the strategy something concrete to answer for. An applicant has a sequence of steps to complete. A bank has a decision to make. The work can be examined at the point where those two processes meet, far from the comfortable generalities of a presentation.
The move to Old National
On August 15, 2022, Old National announced Tischler’s appointment as Community Banking CEO and a member of its executive leadership team. He arrived with 24 years of finance and consumer banking experience. The initial brief covered consumer and retail banking across the company’s Midwestern footprint, bringing his experience with digital delivery and small business customers into a different institution.
The title has a precise meaning. Old National’s chairman and chief executive is James C. Ryan III; Tischler leads community banking. That division of responsibility puts him close to the daily business of households and smaller enterprises. Checking accounts, borrowing and payments may be routine categories on an organization chart. For the customer, each can be the matter that needs sorting out today.
In 2023, he described increased demand for money-market accounts and certificates of deposit as interest rates rose. He also explained that customer and business deposits help fund loans in the communities the bank serves. It was a useful reminder of the mechanism beneath the customer experience: money coming in, credit going out, and a bank managing the connection between them.
Service has a line in the budget
Another part of Tischler’s Associated career concerned the people working inside the institution. He was executive sponsor of its Veterans Colleague Resource Group. In April 2021, the bank announced that he had received the Wisconsin ESGR Above and Beyond Award in recognition of support for employees serving in the National Guard and Reserve. Military employees had nominated Associated for the award.
That July, Associated was named a recipient of the Secretary of Defense Employer Support Freedom Award. It was one of 15 recipients selected from 3,382 nominations. The honor belonged to the employer, and Tischler spoke in his role as the veterans group’s sponsor. The distinction matters: an executive’s part in an organization’s work should be described at its actual size.
The support included leave, retained benefits and full pay for colleagues on training and active military leave. These are specific commitments with consequences for employees and the business. They make a more informative account of workplace culture than a collection of adjectives. A person leaving for military duty has practical arrangements to make; an employer’s policies become part of those arrangements.
Associated Bank was one of 15 employers selected from 3,382 nominations for the 2021 Secretary of Defense Employer Support Freedom Award. Tischler sponsored its veterans colleague group.
Milwaukee, beyond the banking day
Tischler’s civic work also has a financial dimension. The United Performing Arts Fund’s 2023 report lists him as treasurer, an executive committee member and chair of its audit and finance committee. The work sits behind the performances: oversight, money and the organizational foundations that allow an arts fund to keep supporting its community.
His LinkedIn profile dates his UPAF treasurer service from June 2019 to October 2025. That span is more revealing than a passing appearance on a donor list. Arts organizations need people willing to do recurring work, including the sort that seldom earns applause. A finance committee meeting has a rather different relationship with an audience from an opening night.
He is also listed on the board of Acts Housing, whose board brings together people from banking, law, real estate and other fields. Here, his connection to Milwaukee extends into an organization concerned with housing. It adds another local institution to a professional life spent working with consumer finance.
And there is a detail that refuses to fit neatly into a banking biography: his LinkedIn profile lists volunteer service with the National Ski Patrol beginning in November 2022. It gives the career chronology an unexpected second track. Within a few months of joining Old National, he had added a commitment whose setting was some distance from a banking center.
The people behind the second door
In April 2026, Old National brought leaders together in Minneapolis for its Community Leadership Summit. Tischler was among the leaders the bank thanked, alongside Jim Ryan, Timothy Burke and Minnesota Wild CEO Matt Majka. The event focused on conversations, learning and the work of leading people across the bank’s footprint. Even an institution with digital ambitions still gathers people in a room.
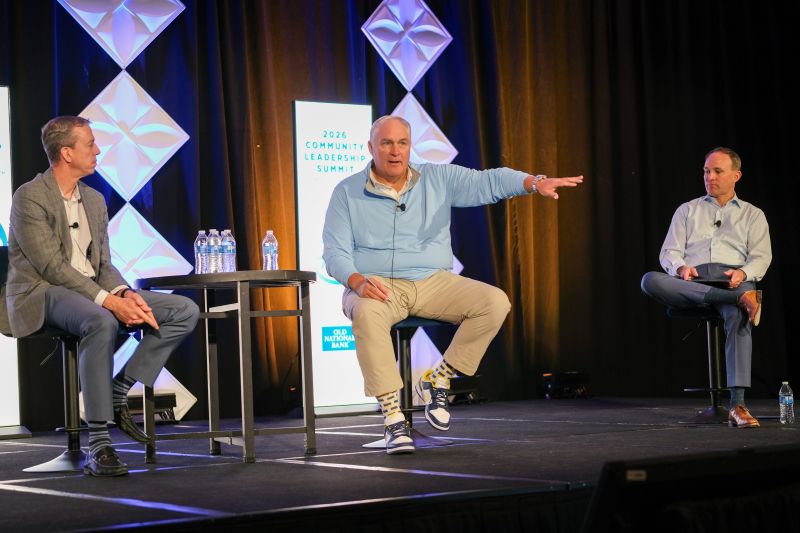
The following month, the agenda for Old National’s annual shareholder meeting assigned Tischler the ethics message. It was scheduled between the welcome and the formal call to order. An agenda cannot tell us what a speaker said, but it can show where the organization placed a responsibility. In this case, community banking’s leader had a role before the resolutions and votes began.
The connection running through his career is a practical one. Payments, digital channels, lending, banking centers and civic boards all involve arrangements that other people depend on. Much of that work happens behind the visible experience. The customer sees the application or the account; the executive’s responsibilities extend through the machinery needed to make it function.
Tischler’s story returns to those two front doors. The pocket-sized one makes access possible at an inconvenient hour. The physical one offers a place for a conversation. His career has repeatedly put both within reach of the same job. The interesting question is what happens when somebody comes through either door with something more complicated than a transaction.
Continue the conversation
Explore the organizations and episodes in this profile.
- Old National: Brent Tischler’s leadership biography
- Brent Tischler on LinkedIn
- Associated Bank: the 2016 retail banking promotion
- The 2021 digital personal loan announcement
- UPAF’s 2023 annual impact report
- Acts Housing’s board of directors
- Associated’s employer support recognition
- Old National’s 2026 leadership summit photographs
- The May 2026 shareholder meeting agenda