A mortgage quote arrives with enough numbers to look authoritative. There is a rate, a payment, a stack of fees and usually someone who sounds reassuring. The missing number is what another lender would charge. Bankrate has built a business around that absence. Its readers come looking for an answer to a deceptively small question: could I do better?
The company occupies the space between a financial newsroom and a shopping aisle. It publishes explanations, surveys and reviews, supplies calculators, and places competing financial offers within clicking distance. A visitor can investigate a savings account, model a home purchase or compare borrowing options without paying to read. The institutions hoping to acquire that visitor help finance the operation.
That arrangement makes Bankrate useful and worth examining. It can reduce the effort of shopping around, but its economics also require readers to understand the difference between editorial judgment and a commercial listing. The site is selling access to an informed decision on one side and access to a prospective customer on the other. Both sides have to keep showing up.
Annual users, according to Bankrate.
A company-reported reach figure.
01Before the browser, there was a newsletter
Bankrate’s origins lie in print rate reporting and journalist Robert K. Heady’s Bank Rate Monitor. Its current founder account places the newsletter’s beginning in 1982, amid banking deregulation; older corporate filings trace the print business to 1976. The consistent thread is the work itself: gathering bank pricing and making it legible beyond the institutions that already understood it.
“My goal was simple: give the little guy a break,” reads the Heady quotation on Bankrate’s founder page. The sentiment has aged better than the delivery system. Bankrate.com launched in 1996, moving rate information onto a medium where someone could investigate a loan after dinner rather than wait for the next printed table.
The important change was commercial as well as technological. A newspaper could tell readers what banks charged. A website could put the reader beside an advertiser at the moment of interest. Bankrate’s older filings describe online graphical and hyperlink advertising alongside its publishing activity. The table acquired a door handle.
02The calculator is the quiet attraction
For consumers, the experience starts with a task rather than a membership pitch. Mortgage and refinance tools let users test loan scenarios. Savings and CD comparisons organize accounts by their terms. Credit card coverage sorts through rewards and borrowing costs; loan and insurance coverage extends the same editorial-and-comparison approach to other household decisions.
A calculator is especially good at catching wishful thinking. Change a loan’s term or rate and the payment changes immediately. Bankrate’s refinance calculator also addresses the question that a lower advertised payment can obscure: how long will it take for savings to recover the costs of switching? A result depends on what goes into it. It is a scenario, not an approval.
Consider a deliberately simple example: a $300,000 fixed-rate mortgage repaid over 30 years. At 7 percent, monthly principal and interest are about $1,996. At 6.5 percent, they are about $1,896. That is roughly $100 a month before taxes, insurance or fees. Neither rate is a live offer here. The point is the sensitivity: a small-looking change can deserve a second conversation.
Savings comparisons provide another kind of translation. Bankrate’s account listings place yields beside minimum balances, fees and institutional reviews. The useful question becomes more precise than “Which bank is best?” It becomes “Which account has terms that fit the way I will actually use this money?” That is a more manageable shopping assignment.
A $300,000 loan. A 30-year term. Principal and interest only.
03Free for the reader. Valuable to the lender.
Bankrate’s advertiser disclosure says compensation can affect the placement and order of products, with exceptions where law prohibits it for mortgages, home equity and other home lending. It also says advertisers do not influence editorial recommendations. Those are different promises. Editorial independence does not make every commercial table a complete map of the market.
Its newer home-lending explanation is more specific: participating auction lenders are ordered by overall cost to the borrower, and Bankrate earns a fixed fee that does not vary with the rate. It says users choose a lender before their information is shared with that institution. These are Bankrate’s stated rules for that experience, not a description of every comparison website.
For advertisers, the attraction is intent. Someone experimenting with a mortgage payment may soon need a mortgage. Bankrate’s media kit describes mortgage leads and click-based arrangements in other categories. The company is therefore more than a publisher selling impressions. It helps providers reach people already doing the arithmetic of a purchase.
The 2017 Red Ventures acquisition put a price on the broader operation: $14 a share, at an announced enterprise value of approximately $1.4 billion. That transaction covered the then-public company’s portfolio, not merely the Bankrate.com address. Its 2016 revenue of $434.2 million likewise belongs to that historical corporate scope. Neither number is a current standalone valuation or sales figure.
- 01ExplainArticles and research
- 02CalculateA decision in dollars
- 03CompareOffers and terms
- 04ConnectA commercial referral
04A $3,343 headline needs its fine print
In June 2026, Bankrate published The Hidden Homeownership Tax, a study comparing 3.2 million mortgage originations from 2025 with its own marketplace benchmarks. It reported that 87 percent of borrowers in the analysis had higher modeled costs than the competitive comparison. The headline figure was $3,343 a year. For a company selling comparison, the research is an unusually direct statement of the problem it wants to solve.
Read the methodology before treating that number as money waiting in your mailbox. Bankrate defines the figure using an assumed eight-year loan duration, including points, fees and interest. The annual number spreads the modeled cost difference across those years and includes zero for borrowers who did not pay more. It is not a measurement of each household’s actual spending in a single year.
The analysis also involves estimated credit attributes and covers loans for which a comparable benchmark exists. Its comparison is Bankrate’s own, rather than an independent finding that every borrower could have secured a particular deal. The sensible inference is that price comparison deserves attention. A guaranteed personal saving does not follow from the headline.
Bankrate’s surveys give the newsroom another route into readers’ lives. Its February 2026 emergency-savings release found that 29 percent of Americans reported more credit card debt than emergency savings, while 44 percent reported the reverse. Those findings describe the tension behind the product tables: many households are choosing which financial problem to tackle first, not hunting for an extra decimal point for sport.
A guaranteed personal saving does not follow from the headline.ON READING THE MORTGAGE STUDY
05Trust has had two very different stress tests
The company’s record contains an expensive contradiction for a business devoted to financial clarity. In September 2015, Bankrate agreed to a $15 million SEC penalty to settle accounting-fraud charges concerning its second-quarter 2012 results. It settled without admitting or denying the findings. The regulator described revenue and expense manipulation intended to meet analyst expectations. This preceded the Red Ventures acquisition.
A later controversy concerned the words readers encountered. In February 2023, Futurism documented an error in a Bankrate AI-written explainer about 5/1 adjustable-rate mortgages. The article wrongly treated that label as specifying a 30-year mortgage. The publication reported that articles disappeared from the automated author’s profile after it asked questions. The visible failure was accuracy in an explanation intended to supply it.
Bankrate’s June 2026 AI policy says it does not publish material written and edited exclusively by AI. It describes human accountability and verification controls, while allowing AI assistance with research, drafting and other work. That establishes the current stated approach; it does not establish that one controversy caused every subsequent policy choice.
The organization also describes a financial review board that checks selected articles for misleading statements, omissions and other problems. Its published process moves from submission through expert review and editorial changes to publication. These mechanisms matter because a persuasive explanation can travel farther than its correction. Readers need the answer to be right before they need it to arrive faster.
06A newsroom with a checkout nearby
NerdWallet also combines personal-finance explanations with comparisons across cards, banking and loans. LendingTree operates a marketplace connecting borrowers with providers. Bankrate sits in the overlap. Its distinctive inheritance is decades of rate reporting, alongside tools that convert abstract borrowing costs into household-scale numbers. That history gives it a recognizable position; it does not make the comparison market an empty field.
Distribution has long extended beyond its own homepage. The acquisition announcement described tools, content and co-branded services supplied to more than 100 online partners, including Yahoo, CNBC and MarketWatch. Today, Red Ventures describes a network of more than 300 financial-institution partnerships. These are different measures from different periods, but together they show how Bankrate reaches both readers and the businesses seeking them.
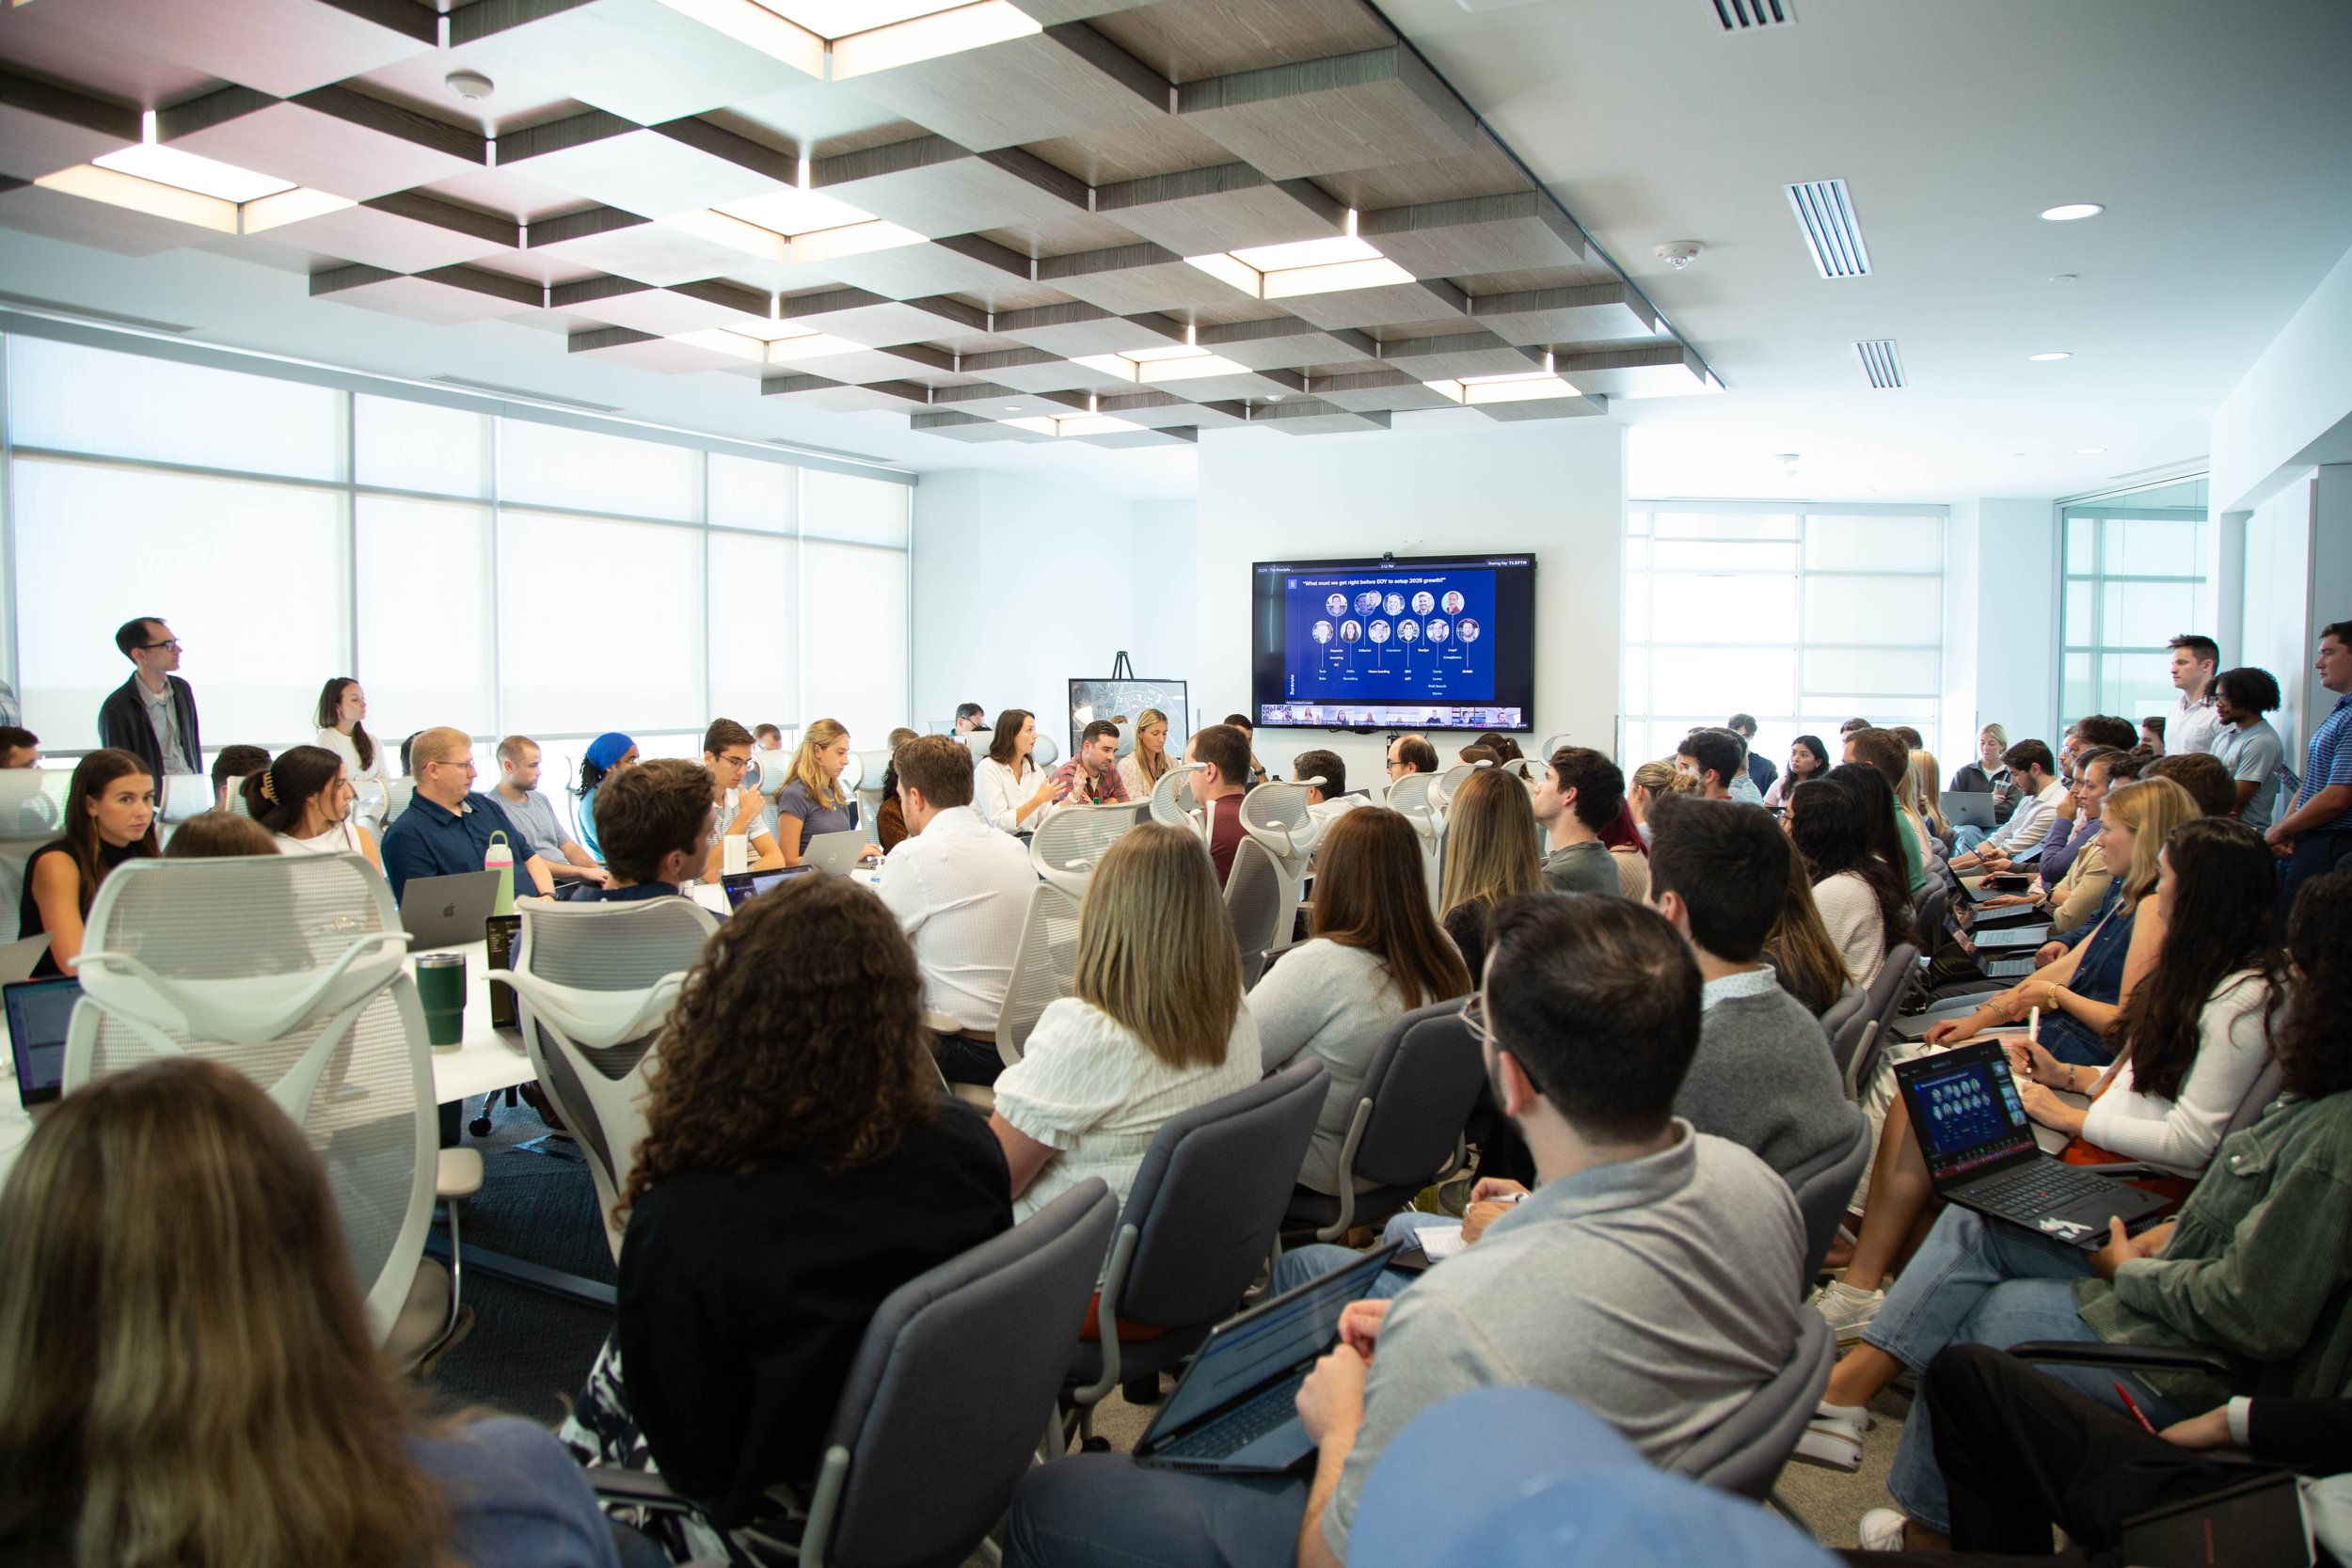
The people behind the pages span editorial and technical work. Red Ventures describes a team working across several U.S. cities, with some remote opportunities. Bankrate’s own recent community-day account describes employees volunteering in multiple locations. That is a glimpse of a distributed organization, not proof of what every working day feels like. The operational challenge is visible enough: keep financial explanations, data and shopping experiences consistent across a large body of work.
07Make the second quote a habit
There is a practical routine readers can take from Bankrate without adopting every recommendation on the site. Start with the decision, use a calculator to identify the variables that matter, and compare equivalent offers. For a mortgage, changing the term, points or assumptions between quotes can make the apparent winner misleading. Then check the provider’s actual terms before proceeding.
The approach has limits. Bankrate acknowledges that its listings do not include every product, its advice is general and the eventual offer may differ from what appeared online. A comparison also cannot make a loan affordable, supply missing income or ensure approval. Refinancing can lose its appeal if switching costs exceed the savings over the time a borrower expects to keep the loan.
For businesses studying the company, the copyable idea is to put an explanation beside a useful action. Answer a concrete question, let the reader test the numbers, then make comparison possible. The harder part is maintaining the data and making the incentives understandable. Bankrate’s own history shows why the publishing and commercial machinery both need scrutiny.
The second opinion remains the attraction. Bankrate turns a private conversation with a bank into something a consumer can question. Its best outcome is an ordinary one: a reader returns to an offer with a better question, a different number and less reason to accept the first answer.
Keep asking better questions
Explore Bankrate’s tools, reporting and public channels.