Before a lender can say yes, it has to pay for the question. An application must be gathered, checked and understood. A decision must follow. For Andy Thienkosol, now CEO of Siam Digital Lending, that expense has become part of the argument for changing how Thai consumers borrow. The loan has a price; so does the machinery that decides whether to make it.
Thienkosol has spent his career inside that machinery. His earlier roles at Genesis Capital and CoreVest concerned business strategy and analytics. At Dunmor, an American lender to property investors, his responsibilities extended to revenue and then operations. By April 2026, he was speaking for a Bangkok-based consumer lender that had announced $7.8 million in Series A equity funding.
The sequence makes an interesting professional story because the borrower changes along the way. A property investor seeking construction financing and a Thai consumer applying through a phone bring different circumstances to the desk. The executive still has to connect the same moving parts: information, a credit decision, funding and a business capable of handling the work.
“We are committed to deploying technology in service of lower costs and better outcomes for Thais nationwide.”
Andy Thienkosol · April 2026
There is a useful plainness to that ambition. Lower costs can be discussed in a meeting. Better outcomes have to reach the customer. Put the two together and the assignment becomes more demanding than adding an AI label to a lending app. It asks what each step costs, who performs it and what the applicant experiences at the end.
A career inside the machinery
Thienkosol’s education connects Thailand and the United States. He earned a BA in Business Management and Finance at Mahidol University and an MBA in Finance at Pepperdine University. The subjects are close to the work that followed: how a business organizes itself, how capital moves and how decisions can be assessed.
At Genesis Capital, he served as vice president of business strategy and analytics. At CoreVest, his title was head of business strategy and analytics. Those titles put the business itself under examination. Analytics supplies information; strategy asks what to do with it. Read as a career progression, they place him near the junction between understanding an operation and deciding how it should develop.
By June 2024, Thienkosol was Dunmor’s chief revenue officer. That month, the lender welcomed Tuan Pham as chief marketing officer and Steve Huff to lead asset management and servicing. Thienkosol had worked with Pham before and publicly welcomed the chance to do so again. It is a small detail with a familiar office truth inside it: a new leadership team sometimes includes an old colleague.
The following month widened his brief. On July 22, Dunmor announced Thienkosol’s appointment as chief operating officer, with responsibility for overseeing operations. Melissa Perez joined as senior vice president of operations. The appointment put him alongside an operations leader with experience at First Republic Bank and other mortgage businesses.
Dated entries show public milestones. April 2026 records CEO status, rather than a start date.
A revenue role and an operations role share a customer, but they view the business from different angles. One concerns bringing business in; the other concerns carrying it through. A borrower can admire the welcome and still judge the lender by what happens afterward. A title change of this kind brings the subsequent steps into the executive’s brief.
For Thienkosol, that promotion is a concrete turning point. The career moves from strategy and analytics to revenue responsibility, then to the running of an operation. The responsibilities grow more extensive at each of those milestones. The job descriptions give the progression its shape.
The borrower on the other side
Dunmor’s business supplied a particular lending context. Founded in 2021, it offered bridge loans, fix-and-flip financing and construction loans for residential and multifamily investment properties. Its customers could come directly or through brokers. Thienkosol’s work there belonged to a business organized around people investing in property.
His current company serves a different market. Siam Digital Lending offers personal lending and nano-finance in Thailand. The latter is a regulated category of lending for occupational purposes. The Bank of Thailand’s public register lists the company’s personal-loan and nano-finance permissions, both granted on February 3, 2022, as active.
That gives his present assignment a specific setting. The company operates in Thailand, within a licensing framework, and seeks to make credit accessible through digital processes. Technology sits inside a regulated lending business. An application still leads to a financial obligation; a faster route to a decision does not make that obligation disappear.
The contrast between his earlier and current markets makes the career worth following. The American property investor and the Thai personal-loan applicant need different products. Their applications contain different information. Yet both depend on an organization’s ability to carry a request from first contact to a usable answer. Thienkosol’s responsibilities now sit at the company level.
A business with more than one front door
Siam Digital Lending describes its origin as a response to a problem in financial referrals. The team had been sending customers from an online financial publishing and referral business to banks and other lenders. Those digital enquiries then entered offline processes, where applications could be delayed or lost along the way. Building a lender was the company’s response to that handoff.
The handoff is a useful place to look. An online form can feel modern while the work behind it remains laborious. The customer has changed channels, but the application may still have a long journey. Siam Digital Lending’s answer includes technology to read and interpret Thai bank statements, digital identity checks and an online loan application system.
Its company materials also describe QR-based payments and digital disbursement. Together, those components sketch an operation that extends beyond the moment of approval. Applying, identifying the applicant, assessing the information, transferring funds and receiving repayments are connected tasks. The app is the customer’s entrance to a sequence of work.
For a CEO, the connection between these tasks matters as much as the tasks themselves. A credit assessment can be technically capable while an application still encounters an awkward handoff elsewhere. Thinking about the whole journey is a way to read Thienkosol’s assignment through his previous operations role. His earlier work at Dunmor gave him responsibility for that broad operational view. The current job extends the responsibility to a company serving a different borrower.
The company’s January 26, 2026 customer breakdown gives that entrance a geography. The Central region accounted for 56.4 percent of customers. The North represented 15 percent, the Northeast 12.8 percent, the South 9.7 percent and the East 6.1 percent. These figures describe its customers at that date; they do not measure its share of Thailand’s lending market.
Bangkok is the office. Thailand is the assignment.
The distribution makes the CEO’s national ambition tangible. Most customers in this snapshot were in the Central region, with the remainder spread across four other regions. A company based in Bangkok can have a customer base that reaches beyond the city. A digital entrance gives that geographical separation a practical shape.
What the new money asks of him
On April 30, 2026, Siam Digital Lending announced an oversubscribed Series A of $7.8 million. The announced investors included a German fund manager, two German family offices and a Hong Kong-based investment house. The company said the equity would support the expansion of its AI-driven lending business. Thienkosol was identified as CEO alongside founder Maxwell Meyer.
By April 2026, SiamDL was reporting more than 300,000 organic app downloads and applications for more than 3 billion baht in loans. Downloads show interest in an app; applications record requests for money. Neither figure is a count of approved borrowers. For the CEO, that distinction separates the size of the audience from the lending decisions the company actually makes.
Series A equity funding for Siam Digital Lending
The company calls its underwriting platform AiTHENA. Its stated purpose is to use a wider set of information to construct customer credit profiles and improve access to credit. Thienkosol’s accompanying statement focused on the cost barrier facing people seeking credit online. That places an operating question inside the company’s expansion plans: how much work does each decision require?
Funding, software and a lending licence each supply something different. Funding provides resources. Software changes how tasks can be performed. A licence establishes permission to operate within a defined framework. Bringing them together is an executive assignment, and one that makes Thienkosol’s earlier progression through strategy, revenue and operations relevant.
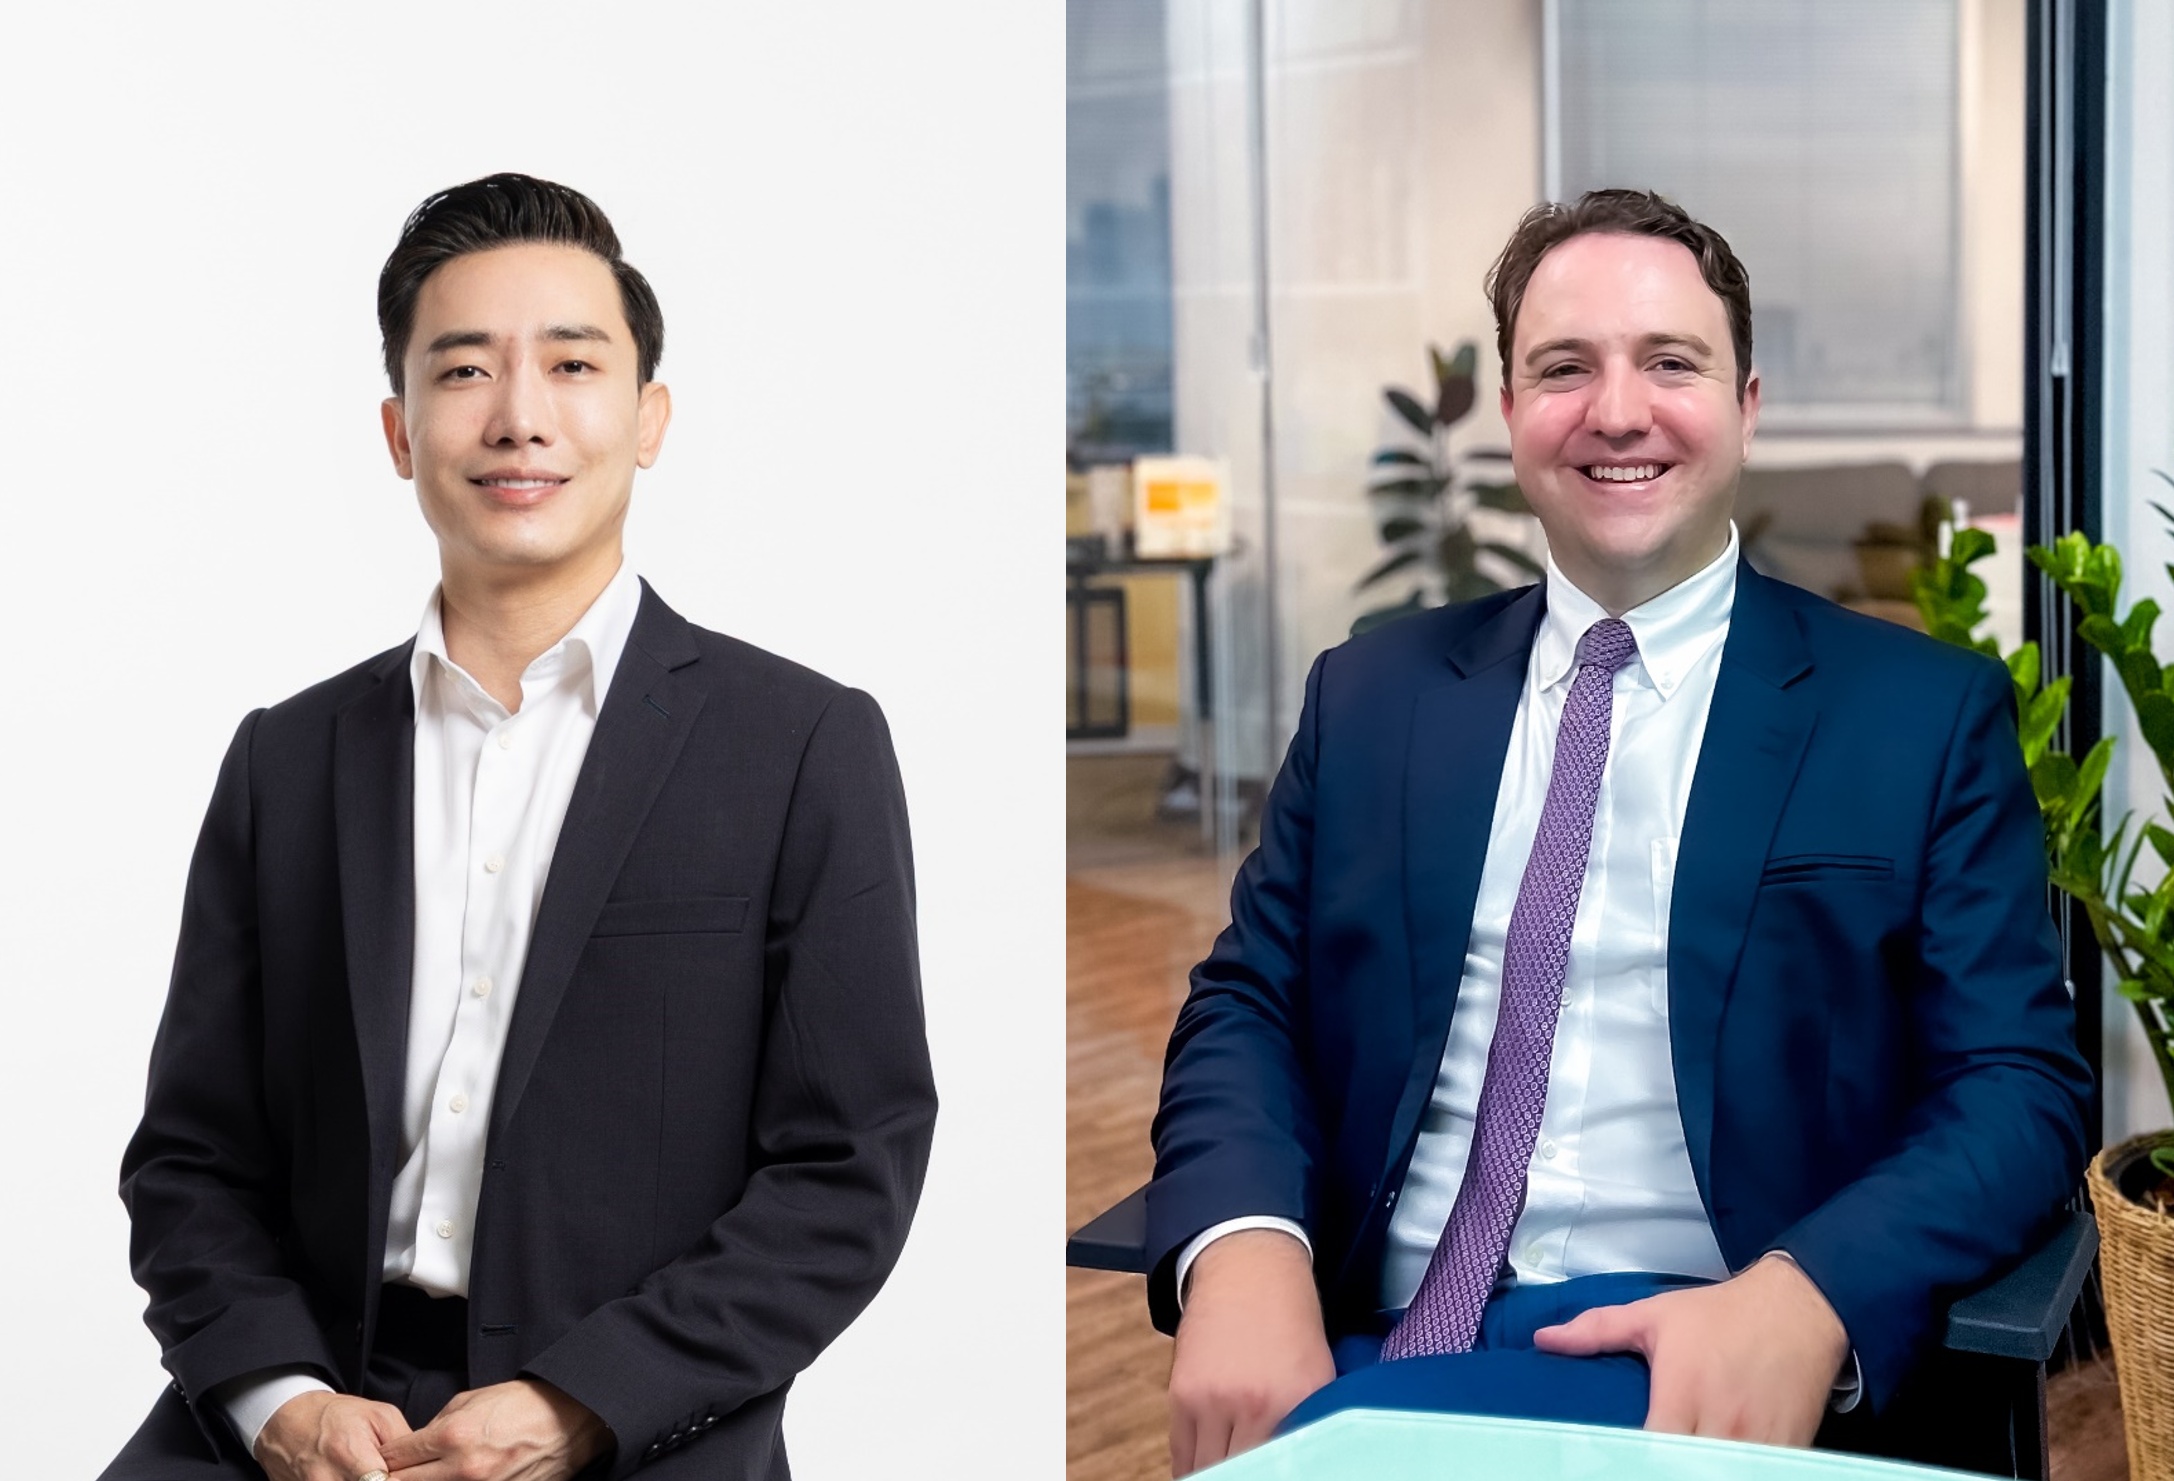
There is also a distinction between an investor’s experience and a borrower’s. The investor encounters a financing announcement and a plan for expansion. The applicant encounters a form, an assessment and a decision. Those are different views of the same company, and the CEO is responsible for a business that must function from both. The photograph of Thienkosol and Meyer accompanies the financing chapter; the company’s digital processes describe the customer chapter. Following both gives the executive title something more concrete than its place on an organization chart.
His career now reaches across two lending markets and several kinds of responsibility. The current chapter is specific enough to judge on its own terms: a Thai digital lender, an announced financing round and a CEO who has tied his ambition to costs and customer outcomes. The next credit decision is where those terms become practical.
Follow the lending trail
Siam Digital Lending website ↗Dunmor management biography ↗July 2024 Dunmor appointment ↗June 2024 Dunmor leadership additions ↗April 2026 funding announcement ↗e27’s SiamDL funding coverage ↗Company channels