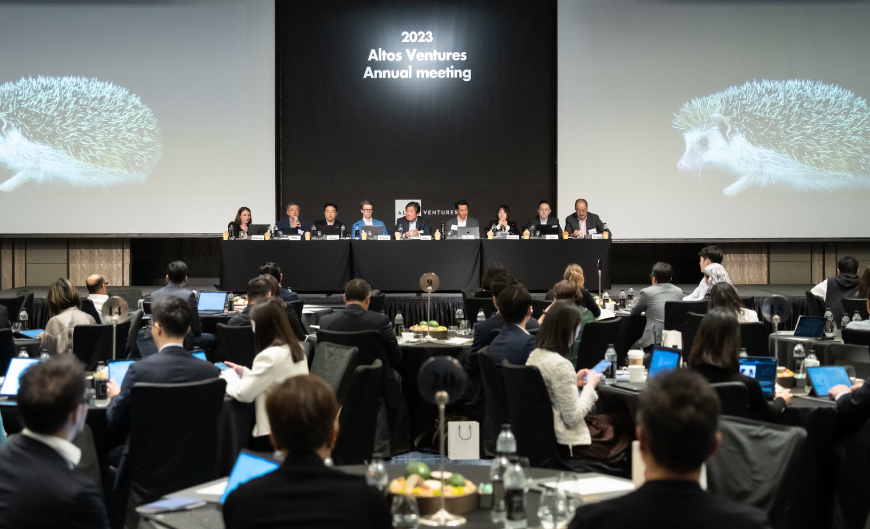
At Altos Ventures’ 2023 annual meeting, the screens beside the panel displayed a hedgehog. An odd mascot for a business associated with unicorns. But the little animal explains something about this firm: it admires founders who stay absorbed in one problem long enough to become unusually good at solving it. The prickles are almost incidental.
- Altos invests in consumer and enterprise technology, from early rounds through growth.
- Its preference: committed founders, sound economics, and room to learn.
- The lesson worth borrowing: budget for proven growth, experiments, and a cash reserve.
That preference becomes more interesting when you learn what came before it. Altos did not simply wake up patient. Its original model depended on other investors wanting what it had found. A market crash supplied a rather forceful reason to reconsider.
The first thing that broke was the handoff
Han Kim and Ho Nam started Altos in 1996. Partner Tae Yoon later described the early strategy as a feeder model: finance very young startups, then introduce them to established Silicon Valley venture firms. Bigger investors would lead the next round at a higher valuation. Each handoff seemed to confirm that the previous decision had been clever.
Then the dot-com bubble collapsed. In a 2025 interview, Yoon recalled those early companies losing their value. His account makes the failure plain: higher financing valuations had been mistaken for enduring business progress. The next investor’s enthusiasm could disappear while a company’s expenses remained very much alive.
With guidance from Stanford investment professor Jack McDonald, the firm turned toward operating fundamentals and the thinking of Warren Buffett and Charlie Munger. This was a change in what counted as evidence. Customer behavior, spending discipline, and a founder’s judgment deserved more attention than the prestige of the next financing partner.
A peculiar compliment: hedgehog
Ho Nam traces part of the idea to a question he asked Buffett and Munger at Berkshire Hathaway’s 2003 annual meeting. In his published recollection, the answer highlighted entrepreneurs who loved their businesses even after becoming wealthy. Money alone could not explain why they kept coming to work.
Altos’s hedgehog is that sort of founder. The firm’s essay describes someone who may have little appetite for networking but plenty to say about the unglamorous details of a product. This person measures, experiments, and learns. Focus leaves room for changing an opinion when the evidence changes.
The preference also shapes leadership decisions. In “Ousting the Founder,” Altos argues that people can acquire expertise by growing with a company. An impressive outside executive does not automatically understand the business better. For a founder considering investors, that is a useful subject to discuss before anyone signs a term sheet.
The customer on each side of the check
Altos serves two constituencies. Institutional limited partners supply capital to investment funds; entrepreneurs receive equity investment and advice. Founders are portfolio partners rather than ordinary customers buying a subscription. Their cost includes sharing ownership, making the terms and temperament of an investor consequential long after the money arrives.
The firm manages pooled funds. Its SEC filings disclose a management-fee entitlement for the general partner or an affiliate. Fund commitments are money for investment vehicles; they should not be read as the management company’s revenue. Altos Hybrid 6 reported $500 million sold in its October 2024 filing. Korea Opportunity Fund 7 reported $350 million in April 2026.
The portfolio crosses consumer and enterprise markets: Roblox, Coupang, Toss, PandaDoc, and Quizlet illustrate the range. Korea became an important part of the practice. In a 2024 Invest KOREA interview, the team recalled a 2006 introduction to Pandora TV and discovering entrepreneurs whose ambitions exceeded the capital available locally.
Its market position combines early entry with the ability to invest again as a business develops. The distinction matters when comparing financing options: ask how an investor handles the years between milestones, and whether its fund structure can support the relationship it proposes.
A big round can make a small problem expensive
The firm’s most practical writing concerns a familiar temptation: a growing company raises a large round and immediately hires to match its new valuation. In “The Series B Trap,” the trouble starts when spending accelerates before the sales process or product is ready. Acquiring customers becomes less efficient. Expectations become harder to meet.
The essay offers a spending heuristic: put half of new capital into things known to scale, a quarter into experiments, and retain a quarter as a cushion. This is an operating suggestion, not a description of Altos’s own fund allocations. Its appeal is that it makes uncertainty visible in the budget.
The same essay recommends watching retention, sales productivity, and customer economics alongside growth. These measures help distinguish an improving business from revenue purchased at an increasingly uncomfortable price. A larger bank balance can postpone that distinction; it cannot settle it.
“Companies built on solid fundamentals need less capital and more time.”Altos Ventures / Venture Lotto
Patient does not mean idle
There are conditions here. Waiting helps when a company keeps learning and its economics can improve. A business with persistent customer indifference will not become attractive merely by surviving longer. Altos’s own hedgehog essay acknowledges that focused founders can fail. Concentration magnifies the consequences of being wrong.
For founders, the useful preparation is concrete: explain what customers already demonstrate, where spending works, and which assumptions still need testing. Ask prospective investors how they respond to missed targets. Altos’s Korean pitch page accepts introductions without an existing connection. Its essays offer something immediately available to everyone else: questions worth answering before raising the next dollar.