Imagine a kitchen renovation paid for in stages. The deposit arrives first, then the cabinets, then the discovery behind the wall that nobody budgeted for. The house may contain plenty of equity. The contractor, however, would prefer money. Trovy has built a lending product around this awkward distinction between having wealth and being able to spend it.
- A home-equity line accessed through a Mastercard, cash transfer, or balance transfer.
- No mandatory upfront draw on lines up to $100,000; larger lines require the excess at closing.
- Lower-cost borrowing can come with fees, variable rates, and your home as collateral.
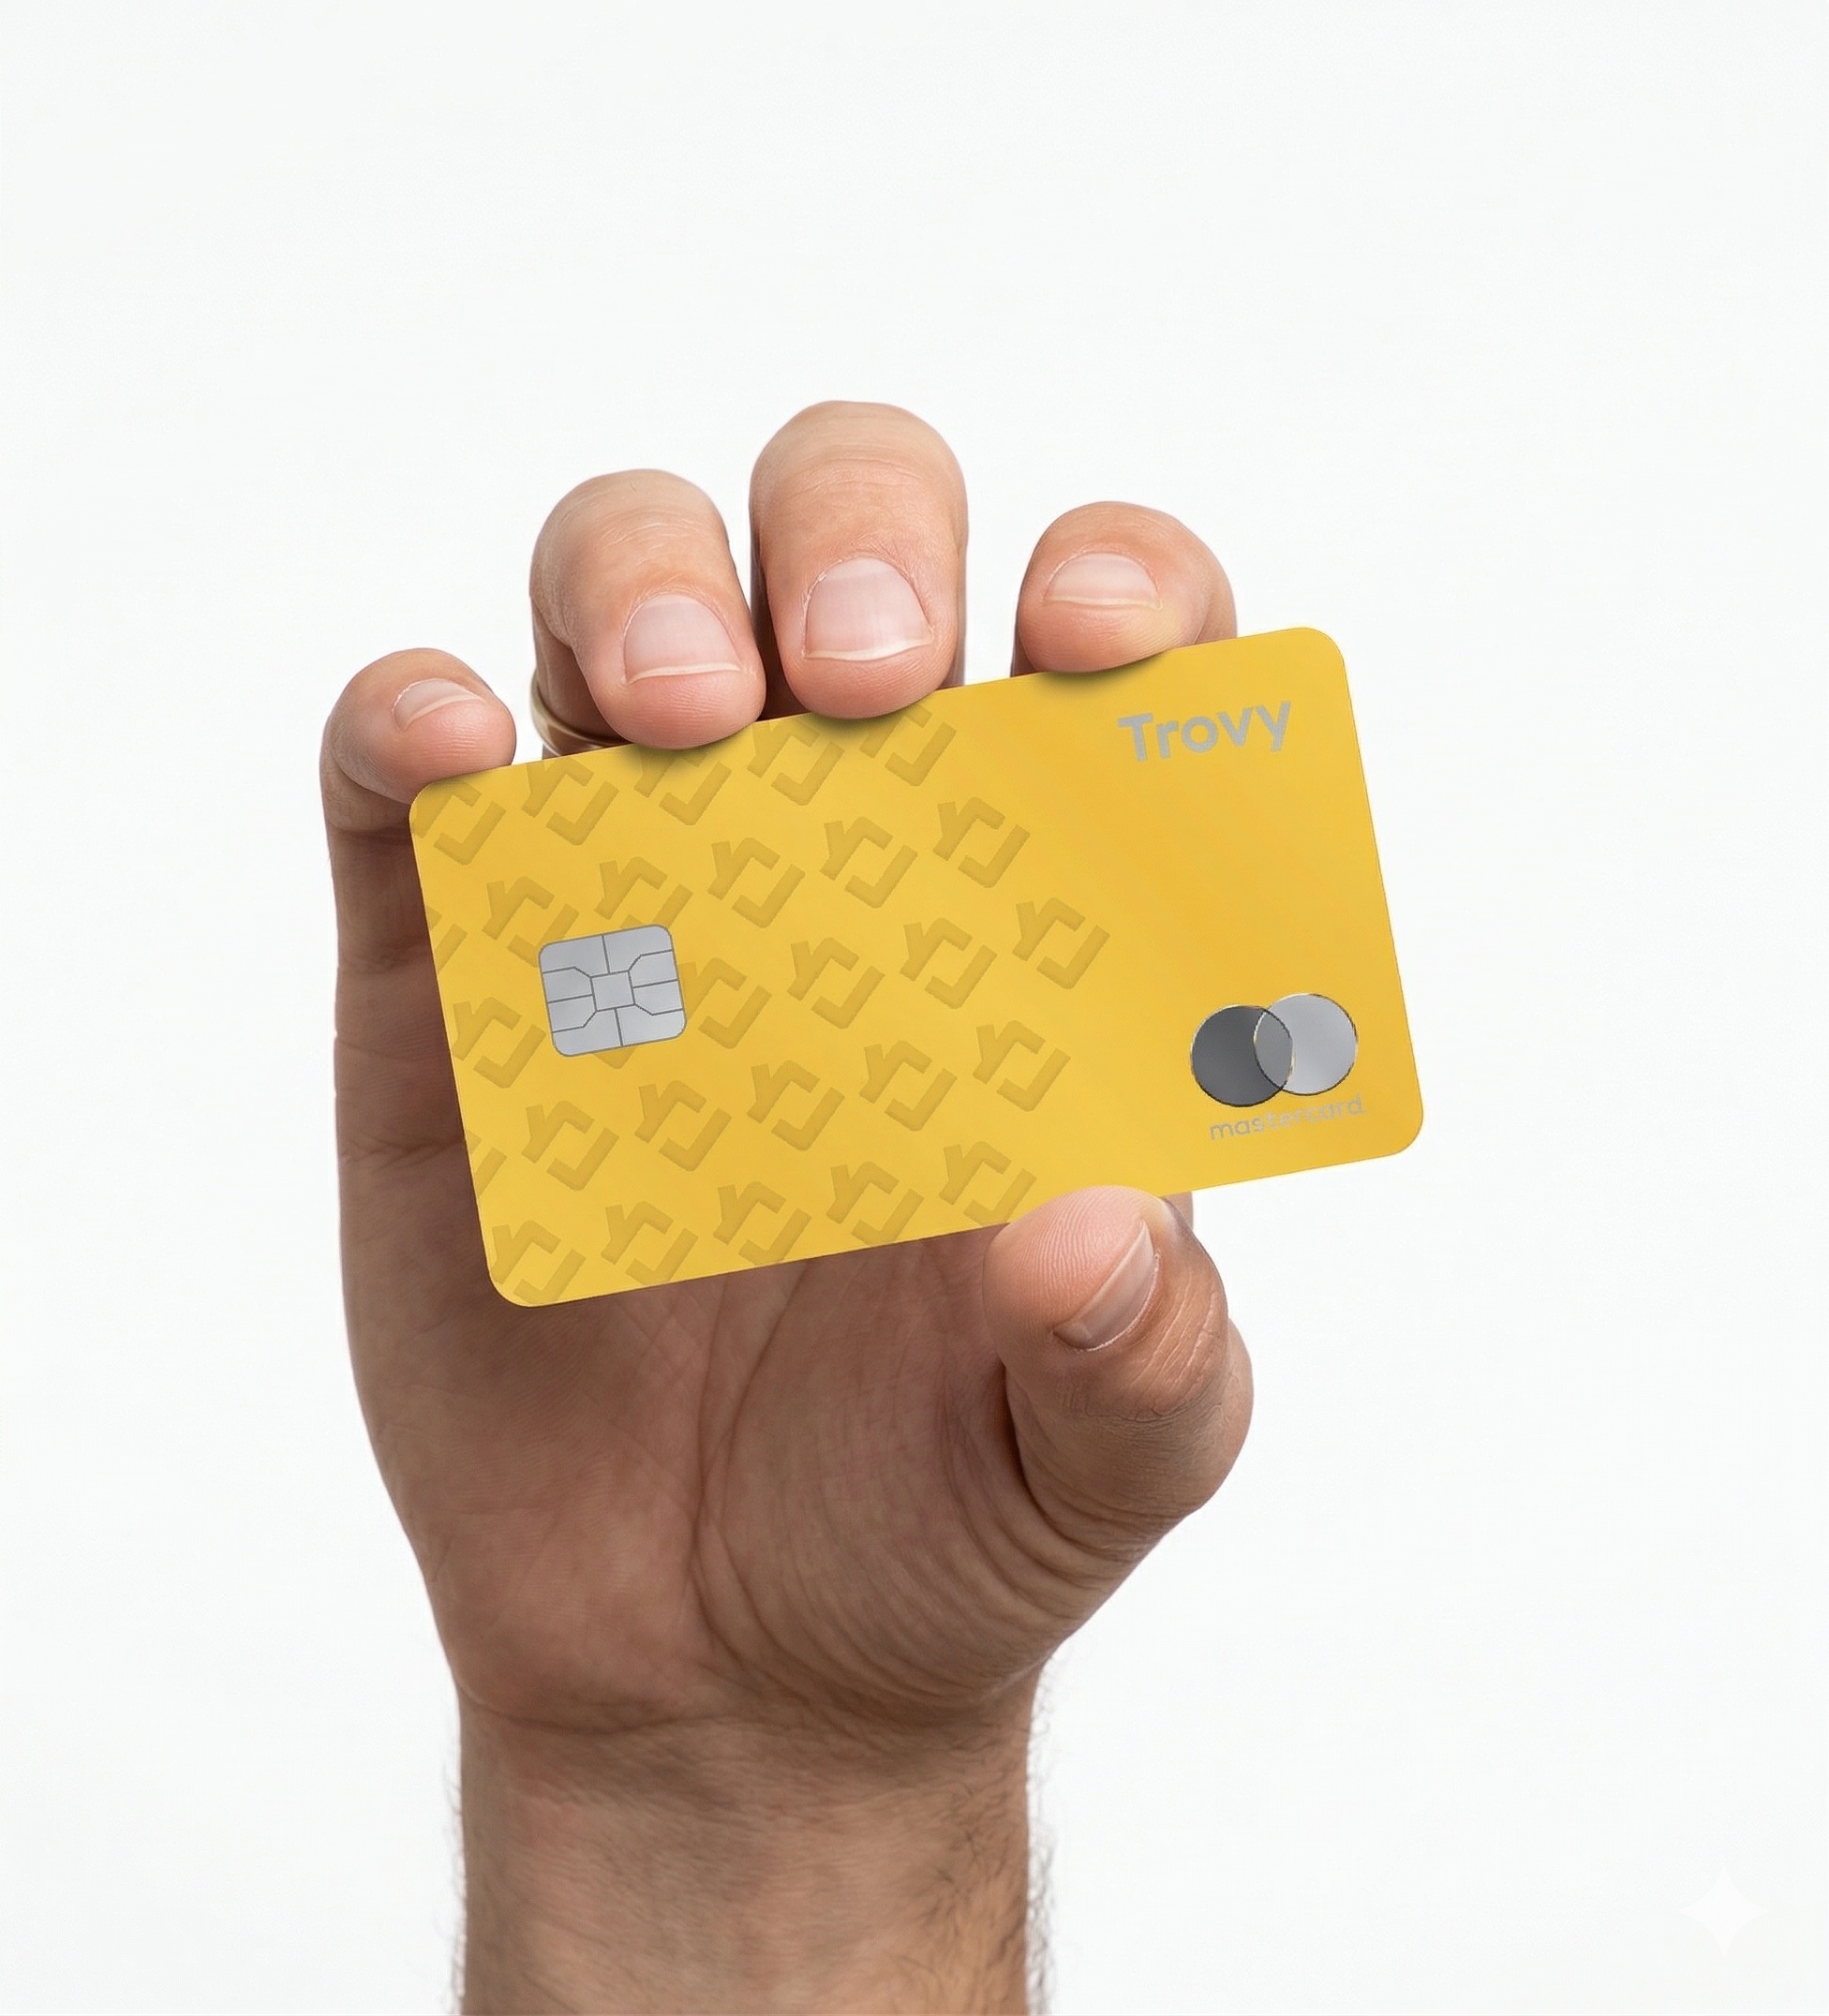
The card is gold. The idea underneath is older: borrow against a house. What Trovy changes is the interface and the timing. Its customers are eligible homeowners who want money for renovations, debt consolidation, or other expenses without turning every purchase into another lending application. A home-equity line of credit, or HELOC, becomes something that fits beside the supermarket loyalty card.
01 / The lesson before the gold card
Trovy was founded in 2024 by TJ Milani, its CEO, and Ashley Harris, its COO. Their background includes Figure, SoFi, and JPMorgan. Milani’s account of his earlier work at Figure offers a useful clue to the thinking behind Trovy. Banks liked the proposed blockchain technology, he recalled, but preferred to adopt it after somebody else had gone first.
The obstacle was adoption. Milani described a change of approach: build a lending business that gave banks a financial reason to participate. Digital HELOCs supplied a product that borrowers and investors could use. This was a lesson from Figure’s beginnings, before Trovy existed, but it explains an enduring concern: technology needs a customer with a reason to care.
Trovy launched its first product in June 2025. A year later, it announced a $15 million Series A led by Left Lane Capital, with Kleiner Perkins, DCM Ventures, and Camber Creek participating. Total funding reached $25 million. The stated uses were expansion, product development, and hiring. Venture backing buys development time; it does not establish that a borrower has found the cheapest loan.
02 / Permission to borrow nothing
One consequential feature is the permission to wait. Trovy requires no upfront draw for a credit line of $100,000 or less. A homeowner can arrange access before every invoice has arrived. Above that threshold, the amount exceeding $100,000 must be drawn at closing. A $150,000 line therefore requires a $50,000 initial draw. Flexibility has a boundary, conveniently expressed in arithmetic.
Illustration of the published draw rule. Yellow = required at closing. Blue = remaining capacity.
Trovy advertises lines up to $250,000, subject to underwriting. The initial draw period is five years, with extensions potentially taking it to twenty at Trovy’s discretion. Investment properties have a five-year draw period and a fifteen-year term. These distinctions matter for someone planning a sequence of projects rather than one glorious weekend of spending.
03 / The route changes the price
Card purchases have no draw fee. Cash transfers and balance transfers can carry one of up to 2.99%. Trovy also lists government recording charges of $60 to $800, potential recording taxes, and conditional mobile-notary costs. Its model is secured lending with interest and disclosed fees. The particular access method changes the bill.
Draw fee. Interest still applies.
Per-draw fee, subject to applicable limits.
For a simple illustration, a $20,000 cash draw at the maximum 2.99% fee would cost $598 before interest. A $20,000 card purchase has no draw fee. These are different transactions, even when both fund the same project. The practical habit to copy is to match the payment route to the invoice, then compare the total cost against another lender’s offer. A headline rate alone cannot do that comparison, and rewards do little to rescue an expensive repayment schedule.
As of September 22, 2026, advertised initial APRs ranged from 6.49% to 15.24% for variable card balances and 6.49% to 15.74% for fixed-rate draws, including an autopay discount. The bottom rate belongs to the most qualified applicants. FixedPay lets customers convert card balances into fixed-rate installment plans; longer repayment terms can add more to the rate.
Here the cheerful card analogy meets its limit. A HELOC is secured by a home. Moving unsecured debt onto it changes the consequences of default. A lower monthly payment can also reflect a longer repayment period. The product is less persuasive for someone who needs no borrowing, lacks sufficient equity, or values keeping everyday spending separate from the house.
04 / A lender behind the interface
Trovy operates through a licensed consumer lender, while Cross River Bank issues the card on Mastercard’s network. That arrangement gives Trovy responsibility for lending design and underwriting while using established card infrastructure. Automated qualification and property valuation support its digital process. Human support remains part of the proposition; a mortgage-sized decision can produce questions that a progress bar cannot answer.
Approval in as little as four minutes and funding in as few as four business days are conditional claims. Automated income verification and remote notarization help; local recording requirements can slow closing. Trovy lists credit-score, debt-to-income, and equity requirements, and operates in 27 listed states. The interface is national in ambition, geographically limited in practice.
Aven is a direct alternative in HELOC cards; Figure and bank HELOCs compete for the same borrowing need. Trovy’s distinguishing combination is the smaller-line draw flexibility, fixed-rate cash access, optional FixedPay, and ongoing card use. Its initial five-year draw period is another comparison point. The useful question is which arrangement fits the size and timing of the expense.
05 / The house becomes an account
“We want Trovy to be the home base for every homeowner.”Ashley Harris, co-founder and COO · June 2026
Trovy’s name borrows from the French trouver, to find, and the treasure trove. Its broader ambition is a homeowner platform with maintenance reminders, records, and rewards. The proposed 1Loan extends the idea into refinancing with redraw capability. Despite the earlier summer-launch announcement, its public page still presents a waitlist and “Coming in 2026.” Ambition and availability occupy different boxes.
The live product keeps acquiring familiar conveniences. Release notes list Google Pay in July, Apple Pay in September, and more detailed FixedPay progress views at September’s end. Rewards currently favor home-related spending. The design lesson is portable: start with an asset customers already have, remove the steps that make using it cumbersome, and make the cost visible at the moment of choice.
Website ↗ · Rates · Fee schedule · Product notes · Articles · Newsroom
LinkedIn · X · Instagram · Facebook · YouTube channel · TikTok