The banks liked the idea. That was the problem. In TJ Milani’s recollection of Figure’s early days, the proposed blockchain technology attracted interest without producing much appetite for being its first customer. Each institution could see the attraction of a new system for financial assets. Each preferred the reassuring sight of somebody else using it.
“They all wanted to be the 10th bank to use the technology not the 1st.”
TJ Milani, recalling Figure’s beginnings
There is a whole committee meeting tucked inside that sentence. The enthusiasm is sincere; the calendar remains untroubled. For a young company, approval without adoption can become a very expensive form of politeness. Figure’s team responded by building a lending business, giving institutions a commercial reason to engage with the machinery underneath.
Milani is now the co-founder and CEO of Trovy, working with co-founder and COO Ashley Harris on home-equity financing. Their starting point is a card that accesses a home equity line of credit. The ambition reaches further, toward a financial home base for homeowners. Between those early bank conversations and this new company lies a career spent moving among the desks where financial products are conceived, funded and operated.
An education in both sides of a loan
Milani studied at Villanova University from 2007 to 2011, with a focus on business administration, finance and real estate. His early professional stops included BMO Capital Markets, Sandler O’Neill & Partners and Apollo Global Management. He then worked on new products and strategy at SoFi. Before becoming a startup founder, he had already worked inside several varieties of financial institution.
That sequence matters to the story. A consumer sees an application, a rate and a payment. Behind those apparently simple objects are decisions about funding, valuation, distribution and what happens after the money leaves the lender. Milani’s jobs have put him on several sides of that transaction. His later moves into product and operations brought the customer’s experience into the same working life as the economics supporting it.
At Figure, the responsibilities kept changing. He joined the founding team in 2018 and worked across product, finance and operations, eventually serving as CFO and COO. A March 2022 filing also carries his signature as chief financial officer of Figure Acquisition Corp. I, the separate acquisition company. The distinction is worth keeping: several related businesses can share a name while requiring different work.
- 2011Villanova
Finance & real estate - SoFiNew products
& strategy - 2018Figure
Founding team - 2024Trovy
Co-founder & CEO
One of his Figure assignments concerned equity of another kind. In December 2021, he was general manager of Figure Equity Solutions when it publicly launched a platform for private companies to raise capital, manage ownership records and trade shares. The platform connected primary and secondary transactions with cap-table updates. Its debut demonstration included a completed secondary offering through a registered trading platform.
The appeal was practical. A company raising money could otherwise find itself moving between providers for different pieces of the process. Putting those activities together offered a way to reduce the handoffs. In that assignment, as in his later homeowner work, the product question involved the distance between owning an asset and being able to do something useful with it.
A house is a rather awkward wallet
By April 2019, Milani was already speaking about the difficulty of accessing residential wealth. At a San Francisco fintech conference, he discussed Figure’s Home Lease Back product, under which a homeowner sold a property and rented it back. The structure was quite different from a HELOC. Both, however, addressed people whose homes held value they wanted to access.
He described looking at problems in existing financial products and considering whether an arrangement familiar in commercial property could work in residential property. Commercial sale-leasebacks supplied a reference point. It was a specific example of product development by borrowing an existing structure and reconsidering the customer it might serve.
“We always look at financial products and ask, ‘What is the problem in the market?’”
TJ Milani, 2019
By 2023, the market had supplied a different complication. Higher interest rates had changed the economics of a cash-out refinance. A homeowner could want additional money while having good reason to preserve an existing first mortgage. Milani, then Figure Technologies’ COO and Figure Lending’s CFO, discussed the opening for home-equity lending as those choices changed.
He also pointed to potential constraints on credit from smaller and regional banks. His argument combined the rate environment, banks’ liquidity positions and technology in lending. It showed the operating executive’s view of a market: consumer demand on one side, institutions’ willingness and ability to supply credit on the other. A convenient application alone could not account for all of it.
This is the recurring puzzle in Milani’s career. Property can be valuable and still be inconvenient when a bill arrives. The roof does not accept instructions to become a bank transfer. Financial products provide the mechanism, and their rules determine whether that mechanism suits the person using it.
A new company, an old acquaintance
Trovy began in 2024. Harris brought her own Figure experience, including service as general counsel, to the partnership. Milani became CEO; Harris became COO. Their company’s official founder page presents the pair together. The shared professional history gives the venture a beginning more specific than the usual encounter between an idea and a pitch deck.
The name reaches for something less technical than a lien. Trovy draws on the French trouver, meaning to find, and the treasure trove. The treasure in question is the equity in a home. It is a cheerful name for an undertaking that still requires underwriting, licenses and repayment schedules. Consumer finance rarely permits the paperwork to be entirely charmed away.
Trovy launched its first product in June 2025, roughly eight months after formation. A year later, it announced a $15 million Series A led by Left Lane Capital, with participation from Kleiner Perkins, DCM Ventures and Camber Creek. The June 24, 2026 announcement put total funding at $25 million. Those are company funding figures, rather than a measure of Milani’s personal wealth.
June 2026
that announcement
June 2026 snapshot
Trovy’s structure also reflects the founders’ operating background. It is a licensed consumer lender with control over underwriting and its borrower experience. The card itself is issued by Cross River Bank under a Mastercard license. The company and the issuing bank perform distinct jobs inside the same customer-facing product.
Harris explained the premise in a September 2026 interview: traditional home-equity borrowing can involve paperwork, appraisals and a separate process for accessing funds after approval. A familiar card removes some of that distance at the moment of purchase. Trovy’s underwriting considers verified income, credit history, property information and existing liens, together with an automated home valuation.
The familiar shape carries a consequential distinction. The credit is secured against the home. Making access easier does not remove the obligation to repay or change the collateral into something less substantial. That tension belongs inside the product’s story: convenience is immediately visible, while the underlying loan requires attention beyond the checkout.
The people in the next chapter
Milani’s connection to Figure continued after his operating role ended. In September 2025, he shared photographs while congratulating Mike Cagney, June Ou and Michael B. Tannenbaum on Figure’s next chapter. The pictures show him alongside Cagney and Tannenbaum at the Nasdaq celebration. One event screen supplies the date: September 11, 2025.
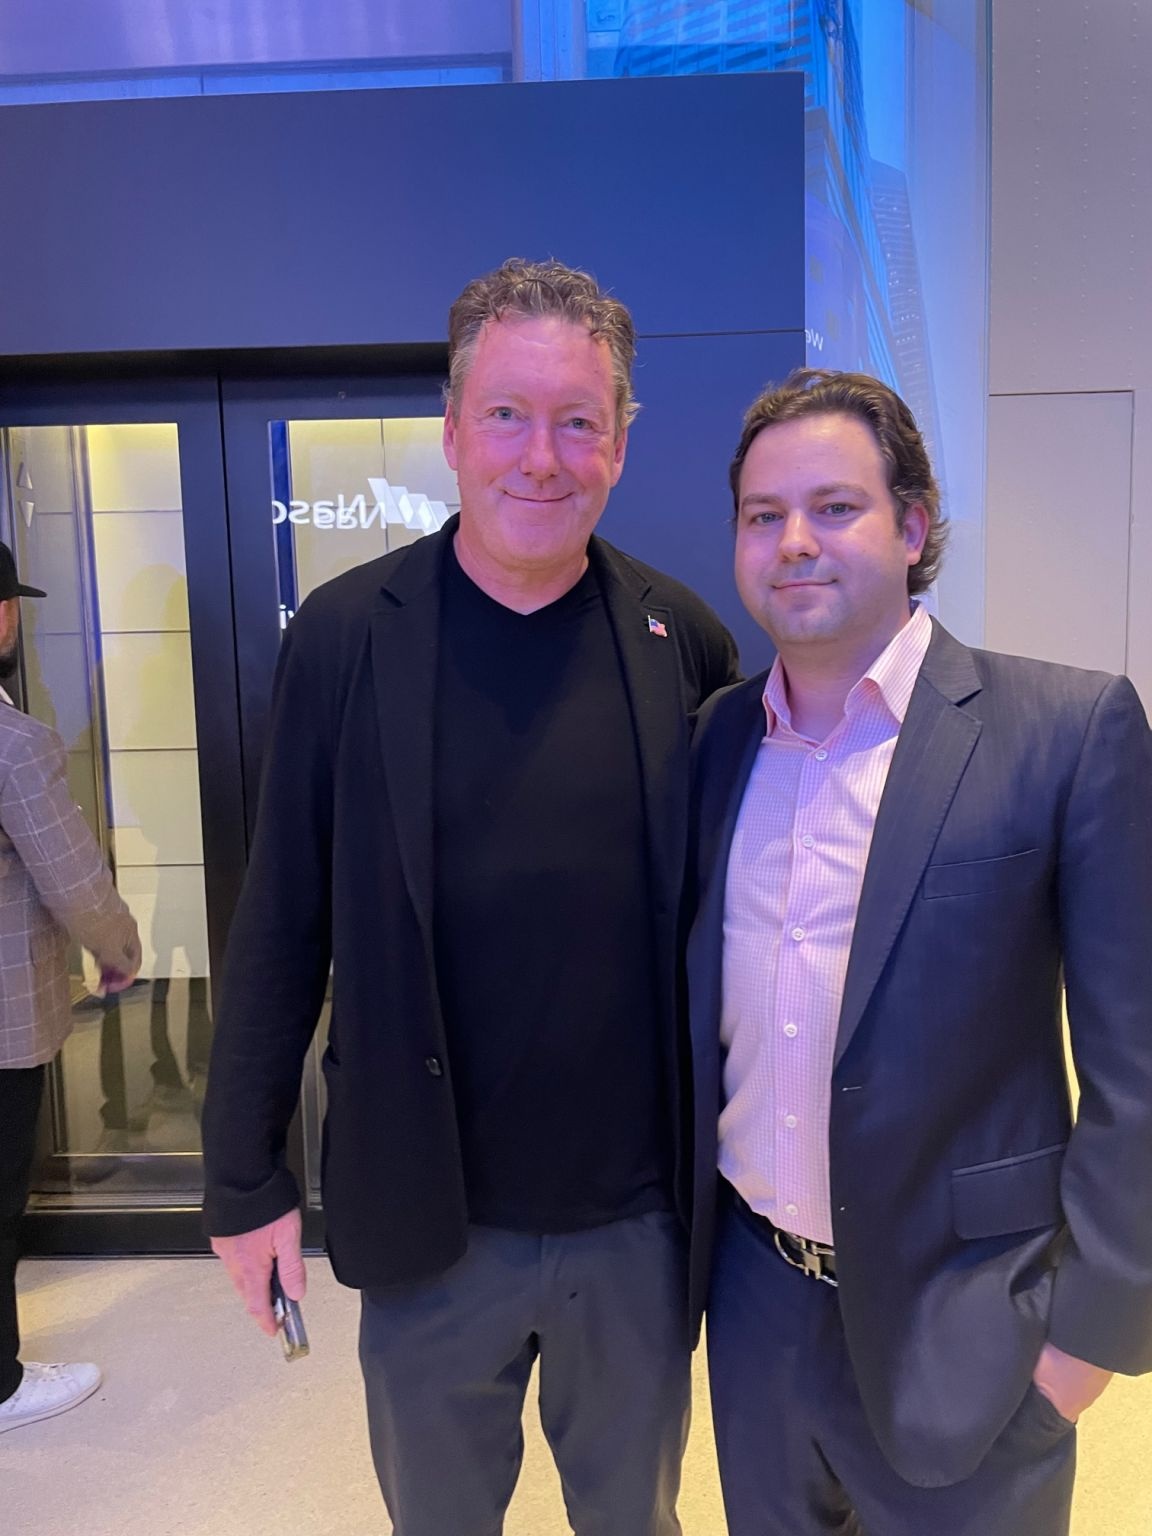
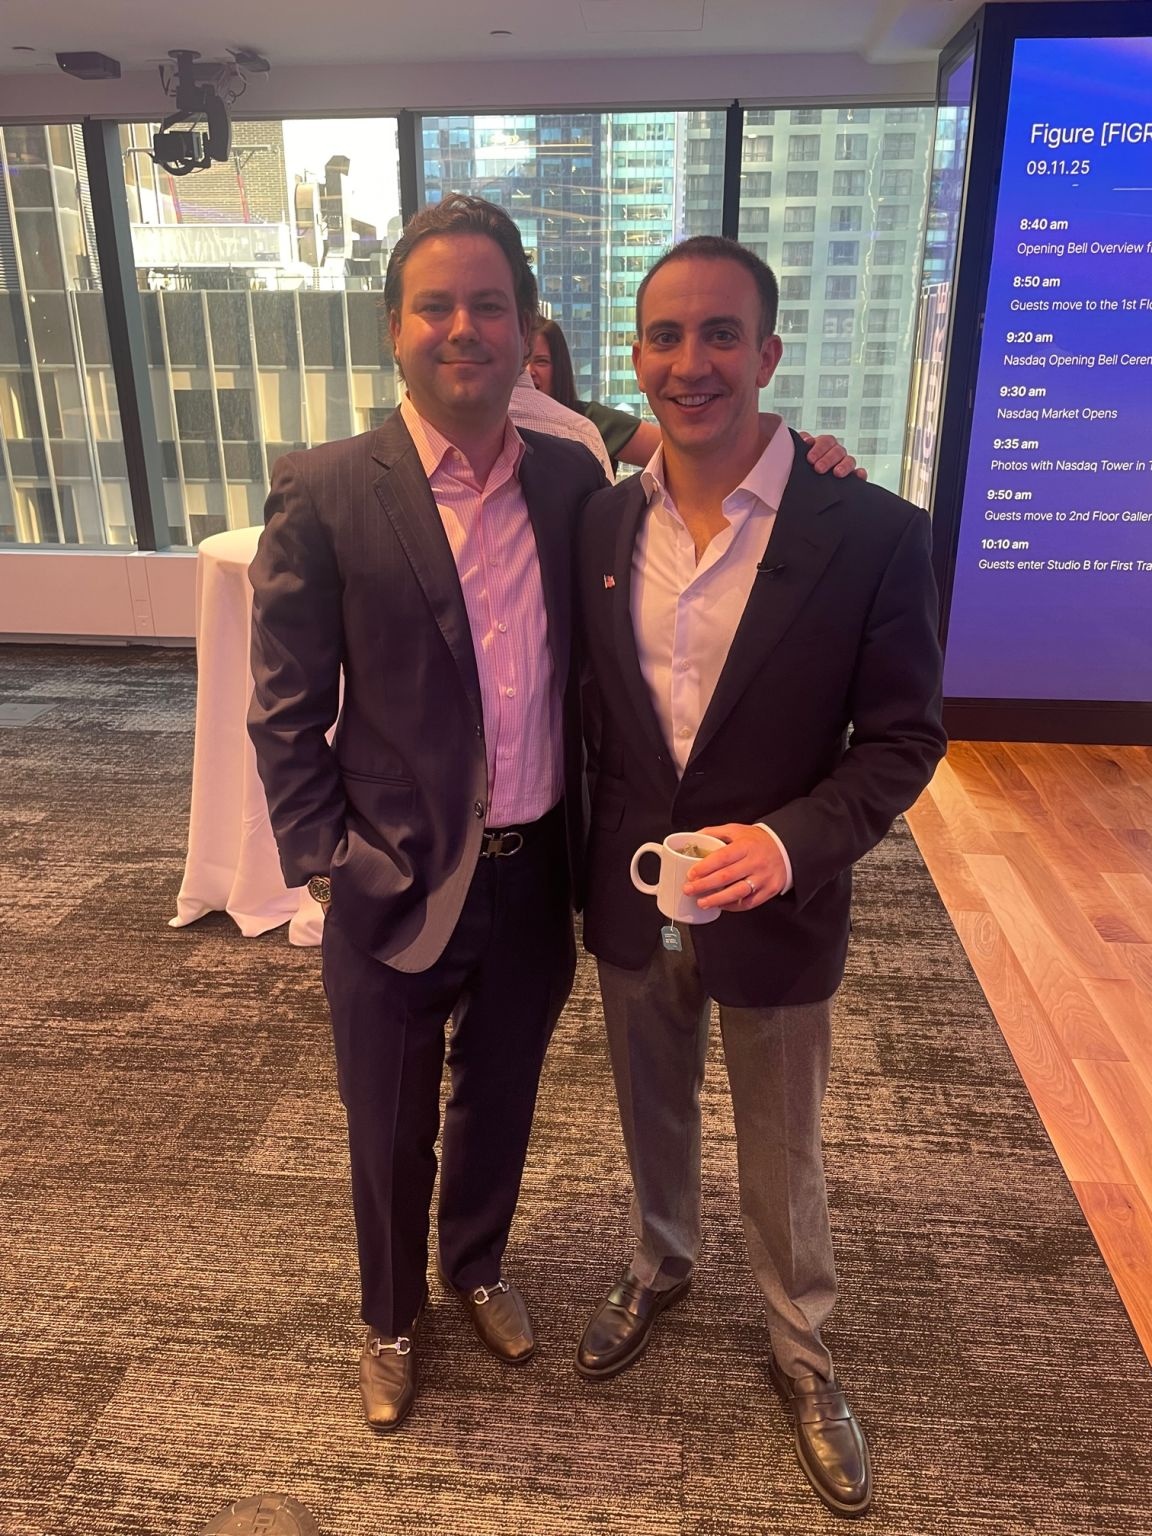
There is something pleasingly ordinary about the photographs. Suits, a cup, people standing close enough to fit in the frame. A career that appears as a sequence of company names is also a set of continuing relationships. Milani had moved on to building Trovy, and he was still there to mark what his former colleagues had built.
His next company’s wider ambition extends beyond borrowing. The homeowner platform described by Trovy and its investors includes maintenance reminders, home records, document storage and rewards. Those are the unglamorous accompaniments of owning a place: warranties, policies and the recurring discovery that a house has another thing requiring attention.
The small things after the big announcement
The live product has been acquiring everyday conveniences. Trovy’s release notes record Google Pay support in July 2026 and Apple Pay in September. On September 30, the company described more detailed FixedPay views, showing repayment progress, fixed rates, time remaining and the balance transfers covered by each plan. These are small pieces of the experience, with direct consequences for someone trying to understand an account.
Another proposed product, 1Loan, would bring redraw flexibility to refinancing. As of this profile’s October 2026 research, its public page invites people to join a waitlist. It belongs to the company’s next-product plans. The card and its ongoing improvements provide the more immediate view of what the team has already put in customers’ hands.
Milani’s story returns, finally, to the hesitant banks. A useful financial product needs people willing to make it part of an ordinary day. At Figure, that meant finding a commercial reason for institutions to participate. At Trovy, the invitation sits in a homeowner’s wallet. His work now is to make the financing, the explanation and the experience worthy of the same small, repeated act: deciding to use it.