In 1988, Béla Szigethy started an investment firm in his apartment on Riverside Drive. The name was wonderfully literal: The Riverside Company. It described where he worked, without pretending there was a financial institution behind the door. Limited capital steered him toward smaller transactions. What began as a constraint became the business.
- Riverside buys and finances smaller businesses, then helps them expand.
- Its operating specialists and acquisition sourcing are central to the offer.
- Founders can pursue a sale of control, minority investment or software growth lending.
That origin explains something consequential about Riverside. An investment firm can grow by pursuing progressively larger targets. Riverside built a global organization while retaining its focus on the smaller end of the middle market. Its history records the first platform investment, aerospace supplier Future Metals, in 1989. Stewart Kohl joined as an equal partner in 1993 and established the Cleveland office.
The space between a good business and a bigger one
Consider the owner of a successful specialist company. Customers like the product. Orders arrive. But entering another country requires unfamiliar distribution, hiring and systems. Buying a competitor requires finding one, examining its accounts and financing the deal. The company’s opportunity has outgrown the machinery available to pursue it.
This is the gap Riverside aims to occupy. Its published criteria distinguish North American Micro-Cap investments, generally up to $10 million in EBITDA, from Capital Appreciation targets with $10 million to $35 million. EBITDA measures earnings before interest, taxes, depreciation and amortization. It describes operating scale; it is not the acquisition price.
The firm works across business services, healthcare, software, consumer brands, education, franchising and specialty manufacturing. Its expertise has to connect financial analysis to practical execution. A cleanroom distributor and a candy brand may both need better sales processes. They are unlikely to need identical advice about products or customers.
What happens after the signature
Riverside’s operating team works with companies from screening through exit. Its consultant toolkit covers pricing, sales and marketing, lean manufacturing, supply chains, customer relationship software and cybersecurity. These are specific interventions. The useful question for an owner is which intervention addresses a measurable constraint in their business.
Acquisitions provide another route. Riverside says more than half its portfolio companies have involved at least one add-on. Its sourcing team helps identify targets; the firm also supports due diligence, financing and documentation. That can let managers pursue a transaction while continuing to run their existing business.
October 2026 offered two illustrations. Swiss cleanroom consumables distributor Abovo became Dastex Group’s seventh add-on. Riverside had backed Dastex in May 2023. Abovo brought local customer relationships and multilingual service. In Pennsylvania, Northeast Inspection Consultants became SAFEbuilt’s nineteenth add-on, extending a platform serving local governments with building reviews and inspections.
These deals make the mechanism visible: acquire an established operation, then add complementary businesses. My reading is that the distinction worth testing against another buyer is the availability of people and processes to execute that plan. A list of completed transactions alone cannot tell an owner how integration will feel.
The cookie test
Tate’s Bake Shop gives the model a more familiar face. Riverside invested in September 2014 and exited in June 2018. Mondelēz announced an agreement to buy the company from Riverside and other shareholders, including founder Kathleen King, for approximately $500 million.
The buyer reported that Tate’s sales had quadrupled over the preceding five years. That period began before Riverside’s investment, so the figure cannot all be assigned to its ownership. The distinction matters. A transaction price establishes what a buyer agreed to pay; it does not establish Riverside’s profit or the return earned by its fund investors.
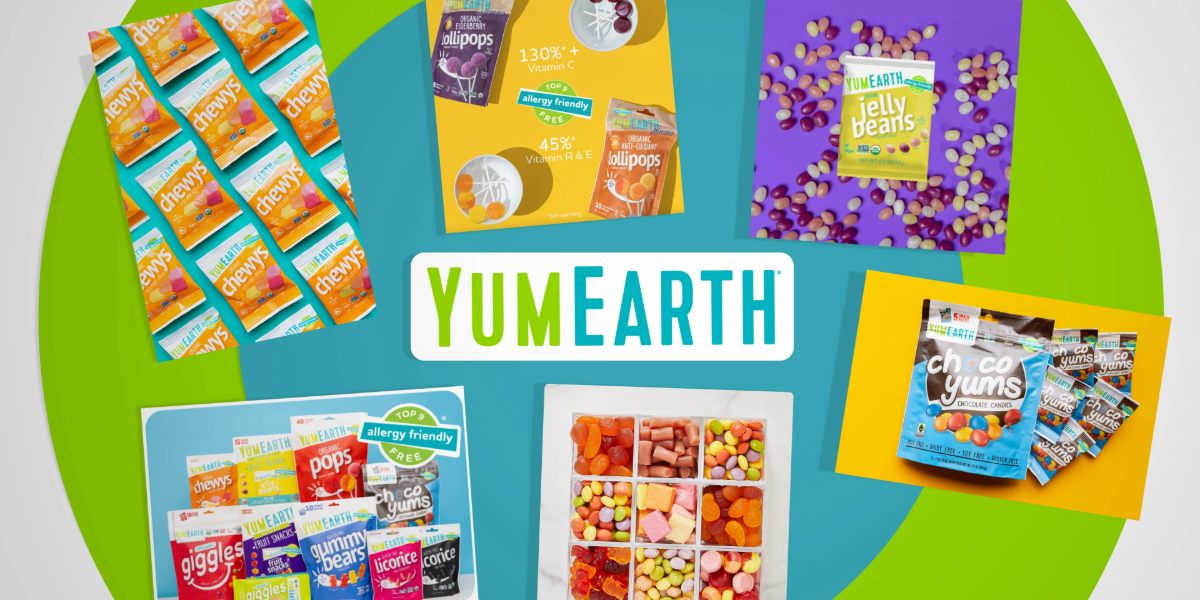
A later consumer exit came in June 2026, when Riverside sold YumEarth to ACON Investments. Riverside described work on product launches, retail distribution, new markets and leadership. Those are the seller’s account of its contribution. They nevertheless identify what a founder should examine when assessing an investment partner: what changed inside the company?
“Riverside was a great partner”
Steve Van Tassel, YumEarth CEO, June 2026
Capital has more than one shape
A sale of control is only one transaction Riverside offers. Strategic Capital makes minority investments. Acceleration Capital provides software growth lending and non-control growth equity. The investment criteria page places its software targets at $3 million to $15 million in recurring revenue.
In February 2026, RAC Growth Lending Fund III closed at $200 million. This was capital committed to a lending fund, not a financing round that valued Riverside. Similarly, the $750 million Value Fund II close in July 2025 measured the size of an investment vehicle.
Fund commitments in U.S. dollars. These figures do not measure revenue, valuation or investment performance.
What does access cost? A July 2021 public pension recommendation for Micro-Cap Fund VI described a 2% management fee and 20% carried interest, with an 8% preferred return. Those historical terms concern one fund and its investors. They are not a price list for owners seeking financing across Riverside’s strategies.
Borrow the method before the money
Riverside also runs an executive education program, Riverside University. Its leadership summit brings together more than 300 executives and Riverside participants. The school even has a mascot, Sammy the Salamander. The charming detail sits alongside a practical idea: managers can learn from people confronting similar problems elsewhere in the portfolio.
There is a method here that other owners can copy. Name the bottleneck. Decide whether it needs money, expertise or both. Before proposing an acquisition, explain the capability it adds and who will integrate it.
My inference is that this approach depends on management capacity and a credible growth opportunity. Additional businesses create integration work; borrowing creates repayment obligations. Neither fixes weak demand by itself. Riverside’s apartment origin suggests a useful discipline: understand the limits you are working within before choosing how to grow.