Silk flowers are an unlikely place to look for a lesson in liquidity. They require no watering, tolerate neglect and have the commercial advantage of refusing to wilt. Petals Decorative Accents, however, failed. Stephen Hicks had been its president, and he later described committing too much money to the business before it went under. A product can be immortal while the company selling it runs out of time.
For Hicks, the episode became a reason to favor cash over a handsome return on paper. That preference gives his career a useful starting point. Money available today, money promised tomorrow and money assigned a value in an account can produce very different experiences. His work at Southridge has occupied those differences for decades. So, with far more serious consequences, did the federal securities case brought against him and two of the firm’s advisory entities.
Hicks is Southridge’s CEO and founding principal, based in Ridgefield, Connecticut. His story includes an entrepreneurial opening in 1996, a family charitable foundation, financing for smaller businesses and commercial office space. It also includes a court finding of liability, financial judgments and an industry association bar. These events belong in the same biography. A career becomes easier to understand when its difficult chapters retain their dates and their weight.
A departure opened the door
Southridge began while Hicks was working at a small New York hedge fund. The principal planned to return to Australia and expected the winding-down process to take a year. Hicks saw an opportunity to begin a fund of his own; his employer permitted him to start Southridge while still working there. The founding year was 1996.
The detail gives the origin story an everyday texture. One person was leaving. Another wanted to try running the business himself. The interval between those decisions provided room to begin. Founding stories often acquire a polished inevitability in retrospect. This one has a timetable and an employer’s permission, two useful ingredients that rarely receive equal billing with ambition.
Hicks’s education included a bachelor’s degree in business administration from King’s College in Briarcliff Manor, New York, and an MBA from Fordham University. His published corporate biographies describe experience in derivatives, financial structuring, risk arbitrage and investment banking. Those fields concern the terms of a transaction as much as the attractiveness of a business. Timing, obligations and the route back to cash matter alongside a company’s prospects.
The small-company end of the table
Southridge’s stated territory is the small and middle market company. Its business developed around structured financing, with arrangements that could include debt, equity purchases and convertible securities. In its current description, the firm calls itself a family office offering direct investment and consultation. The emphasis remains on shaping a transaction around a company rather than simply placing every prospective borrower in the same queue.
That work can bring a financier into the operating life of a business. A 2008 corporate filing identified Hicks as president of Petals, a catalog and online seller of silk flowers, artificial plants and decorative accessories. It also identified him as principal of Double Alpha Group, a statistical arbitrage fund. Retail merchandise and trading strategies make an unusual pair, but both appeared among his responsibilities.
The financing announcements supply another view of the work. In February 2010, a Southridge-affiliated fund announced an agreement offering Covenant Group of China up to $20 million in equity financing. Covenant’s strategy involved investing in growth companies headquartered in China and supporting them with capital and business services. The arrangement connected a Connecticut-based financier with a company looking across the Pacific.
The words “up to” deserve their space. They describe a ceiling on an arrangement. They do not establish that the entire amount changed hands, or that the financing delivered a particular outcome. Finance announcements are full of impressive numerals; the qualifications beside them frequently do more explanatory work. The number attracts the eye. The terms determine what the number means.
Years are easier to count than outcomes
In August 2015, Southridge announced a redesigned website and said it had invested more than $1.8 billion in growth companies globally since its founding. Its May 2021 anniversary announcement put the cumulative figure above $1.9 billion. The firm celebrated twenty-five years in business on May 8 that year.
These are company-reported totals for activity over time. They describe the scale Southridge claimed for its financing history. They provide no personal wealth estimate for Hicks, and they should not be read as investment performance. A dollar passing through a transaction has a different meaning from a dollar earned. A quarter-century milestone likewise marks duration; assessing the work done during those years requires a closer look.
Southridge’s stated investment total since its 1996 founding.
The anniversary account described relationships with public and private companies, entrepreneurs and family businesses. It also referred to an expanded origination team and underwriting capabilities. The language concerns the business of finding opportunities and evaluating them, a continuing process rather than a single celebrated deal. In Hicks’s career, the firm is the recurring institution through which those different responsibilities meet.
The case that changed the account
In October 2010, the Securities and Exchange Commission sued Hicks, Southridge Capital Management LLC and Southridge Advisors LLC. The litigation concerned the management of private investment funds. In September 2016, a federal court granted partial summary judgment to the SEC on its claim involving the misappropriation of investor funds for expenses.
The conduct involved newer funds paying legal expenses incurred by older funds, followed by compensation using illiquid securities. For the investors concerned, the difference between a security and accessible cash was consequential. A holding can appear as an asset while remaining difficult to sell. Expenses, meanwhile, require payment. The case made that mismatch a question of fiduciary conduct and legal responsibility.
Final judgments followed in 2018. The original monetary terms included approximately $7.86 million in disgorgement and prejudgment interest and a $5 million civil penalty against Hicks. Additional allegations involved investment valuations and representations about liquidity. Those claims were resolved by consent, without admission or denial. The earlier court finding on the expense claim remains distinct from the allegations settled on that basis.
On February 23, 2018, the SEC also issued an order barring Hicks from association with an investment adviser, broker or dealer. The order followed a settlement offer he submitted. An executive title and an association bar describe different things; the former cannot supply an answer about the scope of permitted regulated activity. The bar is a substantive part of his professional history.
A later judgment, with different arithmetic
The financial terms changed in an amended judgment filed on April 5, 2022. It set a total obligation of $9 million. Within that total, the disgorgement and prejudgment interest remained approximately $7.86 million, while Hicks’s individual penalty became approximately $1.136 million. A $640,000 payment credit left $8.36 million due under the amended terms at that point.
The payment plan called for $2 million held in escrow and fifteen quarterly payments of $424,000 toward the remaining balance. Earlier injunctions stayed in effect. The amended total, the payment credit and the scheduled installments each answer a different question. Together they explain the terms entered in 2022; a calendar alone cannot establish subsequent compliance.
This chapter complicates any easy treatment of Hicks’s advice about liquidity. Cash was a practical concern in his account of an unsuccessful investment. It was also central to a case involving responsibilities to fund investors. The connection warrants attention without turning separate events into a single explanation of his motives.
A foundation, and a local racing connection
In 1998, Hicks and his wife Mary established the Daystar Foundation. Southridge describes the foundation as a vehicle for charitable giving, including support for nonprofit and faith-based organizations. Among the beneficiaries listed on the firm’s philanthropy page are Keeler Tavern Museum, Young Life Ridgefield and the Association of Religious Communities.
These associations locate part of Hicks’s life at a scale smaller than an international financing agreement. A museum and a local youth organization have identifiable places in a community. Support for them belongs in the portrait, alongside the professional record. Giving and financial conduct have their own consequences; neither can be used as a receipt that cancels the other.
A 2012 company blog added an unexpected connection: support for Andrew “Drew” Manna, an amateur race-car driver from Ridgefield. Manna described balancing jobs with the cost of maintaining his car and said Hicks and friends at Southridge were racing fans. The announcement concerned a local driver hoping to pursue a professional ambition. It offers a specific glimpse of the interests around Hicks, without pretending to report what happened to the racing career afterward.
“I hope to have built things that ‘mattered.’”Stephen M. Hicks · 2012
The office with actual doors
In January 2023, Hicks used LinkedIn to invite visitors to Southridge Holdings in Ridgefield. His posts promoted office suites, individual offices and shared space. The offering included administrative support and access to technology services. It placed a familiar entrepreneurial need, somewhere to work and meet clients, beside the financing work associated with the Southridge name.
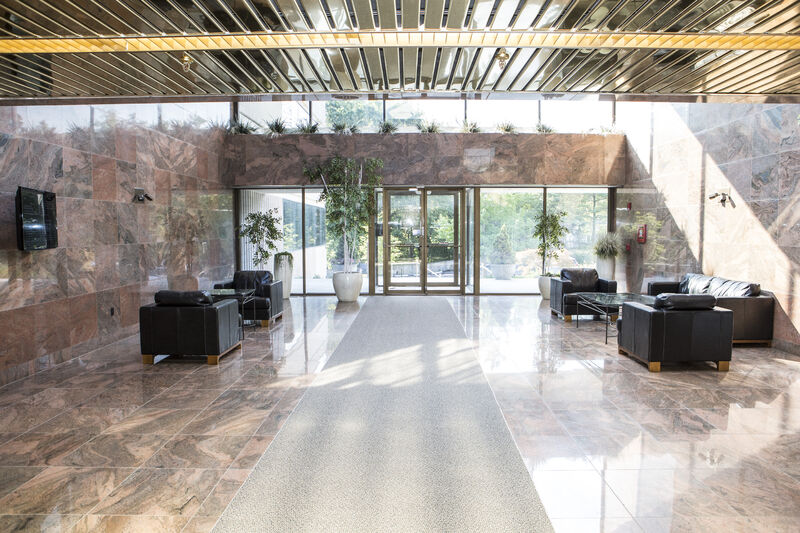
The lobby photograph makes the setting concrete. Sunlight falls across polished stone. Chairs wait near the glass entrance. No spreadsheet is required to understand what the building offers. For a person whose career is often described through securities and corporate structures, an office photograph provides an unusually direct scene.
Hicks’s stated wish to build things that mattered leaves a question rather than a finished assessment. Southridge’s longevity, Daystar’s charitable work, the failed Petals investment and the securities judgments each contribute evidence of a different kind. His biography lives among those particulars. The dates, the money and the obligations make the story harder to compress, and more useful to read.