In October 2007, Stanford L. Kurland called David Spector with a proposition: come back to Southern California. There was a company to build. Spector had moved to London to work for Morgan Stanley, arriving just as the mortgage market began to unravel. His old colleague was preparing to start again in the business that had made them both. The timing was sufficient to make a sensible person inspect the telephone.
Kurland had spent 27 years at Countrywide Financial, climbing from the accounting side of the business to president and chief operating officer. He left in September 2006. By January 2008, he was founding PennyMac, backed by BlackRock and Highfields Capital Management. Spector joined as chief investment officer. Their new enterprise would begin by buying and working through troubled mortgages.
It was an awkward place to put a fresh beginning. Countrywide would become a byword for the lending excesses of the housing boom. A new mortgage company staffed by people who had helped run the old one invited an obvious question: what, exactly, had changed? Kurland’s second act would have to survive that question as well as the ordinary hazards of starting a business.
An accountant gets inside the machine
Kurland’s professional life began in public accounting in 1975, at the firm now known as Grant Thornton. He held a bachelor’s degree in business administration and accounting from California State University, Northridge. One early assignment brought him to Countrywide Credit Industries and its operating subsidiary. In 1979, he joined the company he had been examining.
The move has a pleasing occupational logic. An accountant arrives to understand how a business works; eventually, someone hands him part of it to run. Over the following decades, Kurland served as chief financial officer, president, chief operating officer and director. Those titles placed him close to the machinery of mortgage banking: funding loans, managing operations and organizing an expanding institution.
Countrywide’s public face was co-founder Angelo Mozilo. Kurland was less conspicuous. People outside the company could follow the personality at the microphone while missing the executive concerned with the organization behind it. That division of attention suited the image colleagues later described: a reserved operator who did not require a public performance to exercise authority.
Eric Flamholtz, who advised Countrywide for roughly a decade, remembered Kurland’s attention to strategic planning, executive development and the management of corporate culture. Kurland helped install formal planning processes and commissioned an internal leadership development program. These were the unphotogenic responsibilities of making a growing company function. Nobody rings an exchange bell because the management training calendar is finally coherent.
Flamholtz also remembered that quiet did not mean yielding. Kurland could be verbally forceful without being theatrical. The combination matters: modest public visibility, substantial internal influence. His work sat inside the business, where procedures, appointments and decisions accumulated. A colleague might remember the tone of a conversation; the company would live with its consequences.
“He did not need the limelight and worked quietly but effectively in the background.”
Eric Flamholtz, colleague and adviser
September 2006 was an exit, not an eraser
Kurland’s departure from Countrywide came before the company’s collapse and its acquisition by Bank of America in 2008. The sequence became central to accounts of his career. It also became a temptation: place an exit date before a disaster, and the calendar appears to offer a verdict. Calendars are rather less qualified than they look.
As PennyMac attracted attention in 2009, consumer advocates challenged the idea that former Countrywide executives should profit from repairing distressed mortgages. The criticism concerned responsibility as much as returns. Kurland had held senior positions during the years when lending grew more aggressive. Leaving in 2006 did not remove those years from his biography.
Kurland’s answer was that Countrywide’s riskiest lending came after his departure. He acknowledged having supported higher-risk loan products, while maintaining that borrowers should have been able to repay them. His account included disagreements over standards. Critics disputed the comfort that this chronology offered. The argument followed him into the new venture.
There were competing explanations for the departure itself. Mozilo described a disagreement about the terms on which Kurland wanted to become chief executive. Other accounts emphasized strategic differences. It is possible to establish the departure without turning either explanation into an all-purpose account of what happened to Countrywide afterward.
The tension belongs in any portrait of Kurland. A person can possess formidable operating skills and still face difficult questions about how those skills were used. His subsequent success measures what he built at PennyMac. It cannot settle every argument about the company he had previously helped run. Keeping both parts in view makes the second act more interesting, and more honest.
Buy the loan. Change the calculation.
PennyMac’s initial proposition involved a different part of the mortgage’s life. Instead of concentrating on creating a loan, the company would acquire distressed loans from institutions seeking to reduce their exposure. Then came the laborious work of assessing borrowers, contacting them and determining what could be done with each account.
Its investors included BlackRock Mortgage Ventures and Highfields. The money mattered, but capital alone did not explain the proposition. The company needed people who understood mortgage assets and people who could operate a servicing business. Kurland’s team brought experience in both. Familiarity with the industry was an advantage for the business and a reason for public suspicion.
The economics were straightforward enough to describe, though much harder to execute. A loan purchased below its face value could allow room to adjust a borrower’s terms. If the account returned to regular payments, the investor could own a more valuable asset and the borrower could remain in the home. That possibility was central to PennyMac’s defense of its model.
Possibility was not a promise that every borrower would keep every house. The company’s early approach required examining individual loans and considering different outcomes. Contact with the borrower mattered because a mortgage balance alone could not supply all the information needed for a workable resolution. The financial instrument came with a person attached.
- AcquireBuy distressed mortgages from sellers reducing exposure.
- AssessReview the loan and communicate with the borrower.
- Work throughSeek a sustainable payment arrangement where feasible.
There was a practical answer to the criticism: a troubled loan still needed someone to deal with it. There was also an unresolved ethical question about who benefited from the repair. PennyMac occupied both conversations. Its business could offer a route through a damaged market without making the circumstances of that market any less troubling.
Two stock tickers, several kinds of work
The original opportunity did not remain the entire company. PennyMac Mortgage Investment Trust went public in 2009. PennyMac Financial Services followed in May 2013. The similar names can make the distinction feel like an examination question. The investment trust owned mortgage-related investments; the financial services company supplied the operating platform, including lending, servicing and investment management.
That distinction helps explain Kurland’s achievement. He was building more than a fund to exploit a moment of dislocation. The operating business acquired loans from other lenders, made loans through its own channels and serviced mortgages over time. Different activities supplied different kinds of work and revenue. The borrower saw a payment or an application; behind it sat a network of capital and operations.
By the end of 2013, PennyMac Financial reported $182 million in pretax income, 54 percent above the previous year. It ranked among the top ten mortgage originators and the top twenty servicers by volume. An additional servicing facility opened in Fort Worth, Texas. The founding idea was acquiring addresses, employees and recurring responsibilities.
Kurland and Spector’s shareholder letter also described the space opening as large banks reduced their mortgage presence. PennyMac sought business from smaller originators, including community banks, and expanded its direct lending capabilities. The strategy depended on being able to handle the work that accompanied the assets. A servicing portfolio is a continuing obligation, not merely a number to announce.
Scale eventually gave the second venture a national footprint. In its January 2021 announcement about its founder, PennyMac reported more than 6,000 employees. For the twelve months ended September 30, 2020, loan production totaled $170 billion in unpaid principal balance. At that September date, its servicing portfolio stood at $402 billion. The dates matter: these describe a particular stage of the business he founded.
A little room for a golf swing
A photograph preserved by the Stanford L. Kurland Memorial Golf Classic catches him on a course, club raised, cart beside him, the landscape washed in warm light. There is no lectern, earnings slide or executive title in the frame. The ball is still on the grass. For once, the next calculation has a rather small target.
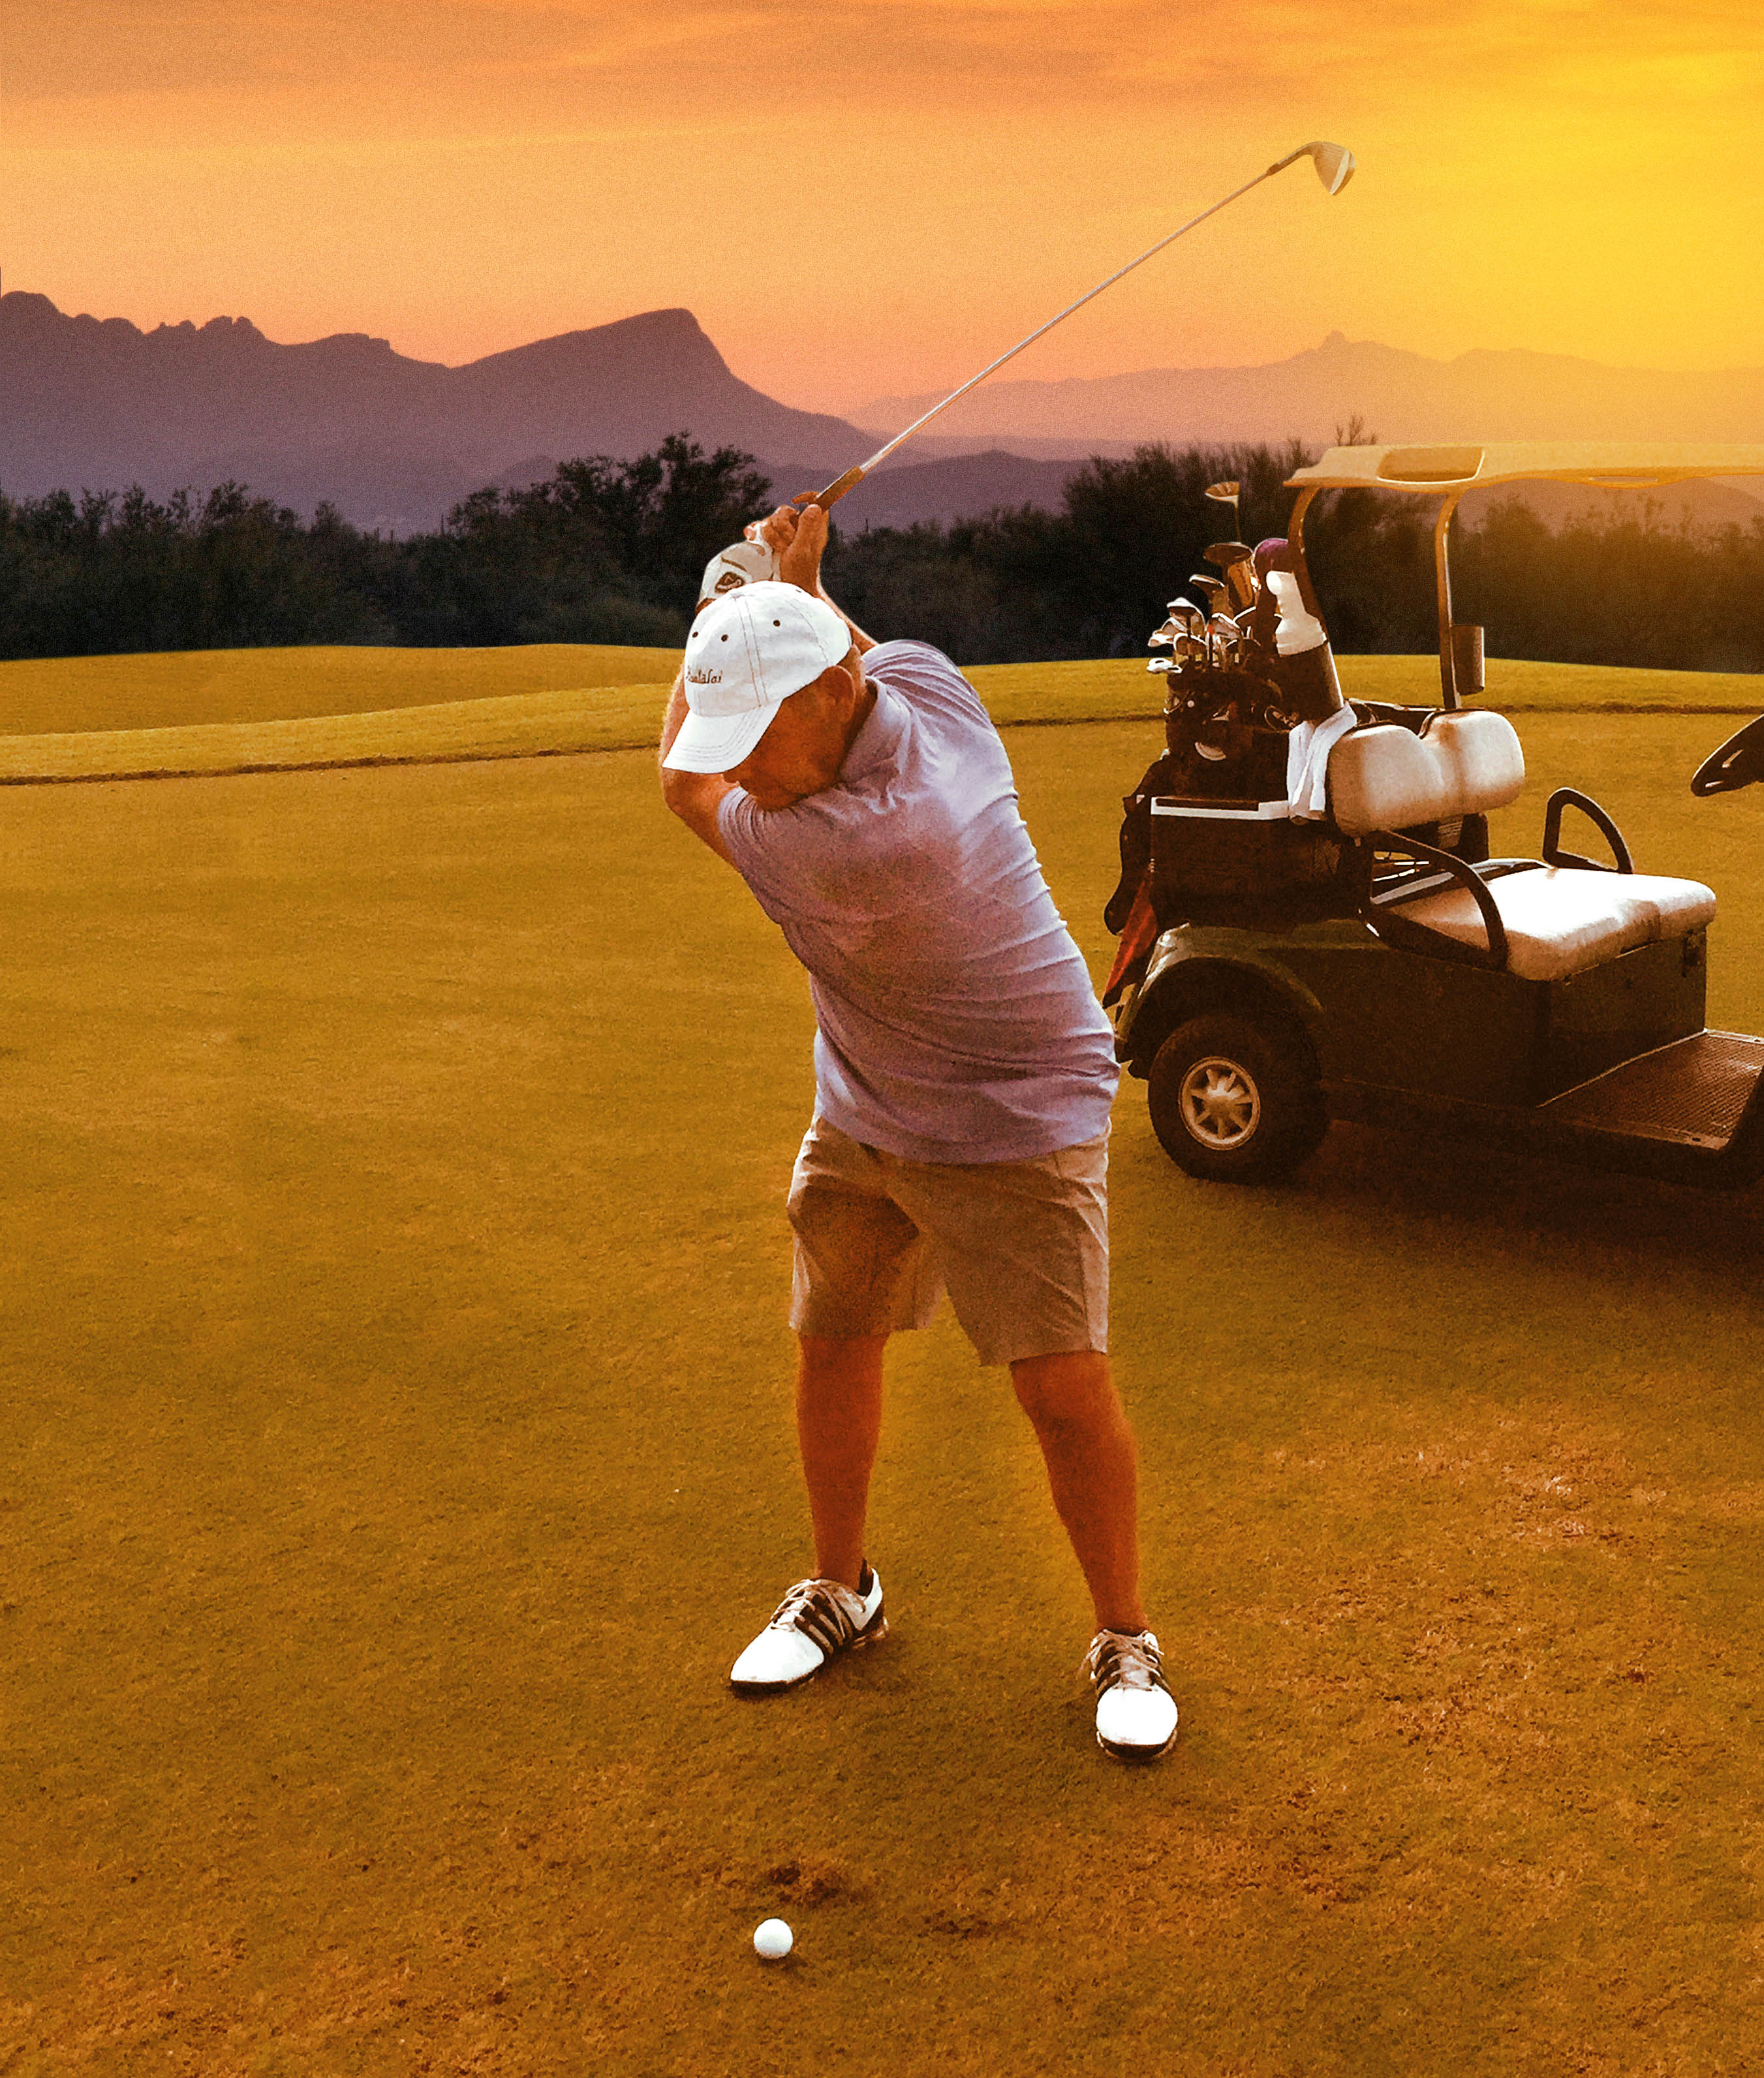
The image offers a small correction to the formal career record. An executive biography records promotions with admirable discipline and leaves most afternoons out. This one gives us an afternoon. It does not reveal a handicap, a favorite course or a theory of recreation. It shows someone enjoying a pursuit with its own exacting demands.
Spector’s remembrance supplied another personal detail: Kurland cherished his family and friends. His wife, Sheila, was named in the company’s tribute. Spector spoke of a working relationship extending over 31 years. That duration gives the praise some context. They had known one another across different firms, different responsibilities and a new enterprise’s uncertain beginning.
Make room at the top
In December 2016, PennyMac announced that Spector would take over as chief executive effective January 1, 2017. Kurland became executive chairman. He explained that the changes would give the next generation of leaders wider roles and more responsibility, while making clear that he intended to stay involved in strategic and operating direction.
The arrangement reflected a familiar problem for a founder: how to transfer authority while remaining useful. Kurland’s answer was a change in position followed by a further withdrawal from daily responsibilities at the beginning of 2020. He remained non-executive chairman. The business would continue with a chief executive whose career he had helped develop.
Kurland died in January 2021. His career had stretched from an accounting assignment to senior leadership at Countrywide, then to founding a national mortgage enterprise in the middle of a financial crisis. The public record contains achievement, criticism and affection. None needs to borrow the others’ vocabulary.
The second act began with a call to someone he knew. It ended with that colleague running the institution they had built. Between those moments were loans to assess, systems to organize and difficult questions that did not disappear. Kurland’s place in mortgage history rests in that work, with all the arithmetic and human consequences it carried.
Follow the second act
Company records, a colleague’s recollections and the conversation that looks back on the beginning.