Sammy Greenwall had encountered the future of commercial real estate, and it appeared to involve moving things around in PowerPoint. At Toll Brothers, the young analyst helped prepare presentations for apartment and condominium joint ventures. The deals were substantial. The formatting was inexhaustible. Years later, when he began building Henry, he returned to the memory of a capable person spending much of the working day arranging a slide.
There is something wonderfully disproportionate about that origin. A property can command millions of dollars; its introduction to the world can still depend on somebody getting a table to behave. Greenwall understood the irritation from inside the job. He also understood why the presentation mattered. A broker needs to make a credible case, and the material carrying that case has to survive scrutiny.
Henry, the company he co-founded with Adam Pratt in 2024, began by taking on those materials. Its subsequent expansion into underwriting, research and buyer lists follows the same line of inquiry: how much preparation stands between a person who knows a deal and a person who might agree to it?
A forward with several other interests
Before he was selling software to brokers, Greenwall was an Oakland student with a crowded extracurricular calendar. At Head-Royce, he captained the basketball team as a senior. His school record also included tennis, cross country, debate, tutoring and work on the online section of the student newspaper. The list suggests someone who had found rather more uses for an afternoon than an afternoon could comfortably accommodate.
Swarthmore’s 2014-15 roster listed him as a six-foot-five freshman forward, wearing number 33. His athletic biography described a high school junior season averaging 14 points, eight rebounds and three assists. It also recorded that he did not compete during his freshman season. His stated reasons for choosing the college included academic intensity, political activism and the chance to help change the basketball program.
By the following autumn, he was speaking publicly about a different calculation. As a former member of the team, he described how restrictions around practice had interfered with choosing classes. He had gone to Swarthmore to broaden his education; the sporting schedule was narrowing his options. It was a specific disagreement about what college time should be for.
There is no need to turn that episode into a tidy prediction of a startup career. It is interesting on its own terms. Here was a student willing to reconsider an activity he had actively sought out, and to explain why. A full calendar, he had discovered, could still be a badly allocated one.
Oakland upbringing. Head-Royce team captain. Swarthmore forward, No. 33. A student newspaper and a debate team also had claims on his time.
Learning what happens behind a deal
His early professional stops included Blumberg Capital and Tuesday Capital, followed by capital markets work at Toll Brothers. That put him at the intersection of property, financing and the information needed to make a transaction happen. It also furnished the presentation problem he would carry into his next company.
In September 2019, Greenwall co-founded Lev. The business applied technology to commercial real estate financing, and his responsibilities reached well beyond making introductions. He worked across lender relationships, credit, underwriting and the movement of deals through the pipeline. These were jobs where a plausible answer had to become a financeable transaction.
By 2022, his work had earned a national Next Generation Award from Connect CRE. The award profile described Lev as having facilitated more than $1.5 billion in loans at that point. It also credited Greenwall with overseeing the launch of Lev Lending that February, extending the company into a lending platform for single-tenant net lease properties.
The useful part of that chapter is its proximity to the customer. Greenwall had spent years around the people, processes and institutional habits he would later ask to adopt Henry. In his founder biography, he describes helping scale Lev to a Series B and an annual revenue run rate above $10 million as its chief revenue officer.
That experience did not make the next business inevitable. It gave him a more informed place to start. He knew what a brokerage was trying to accomplish, what information changed hands and how much ordinary manual work persisted around transactions with very large numbers attached.
The presentation gets its own company
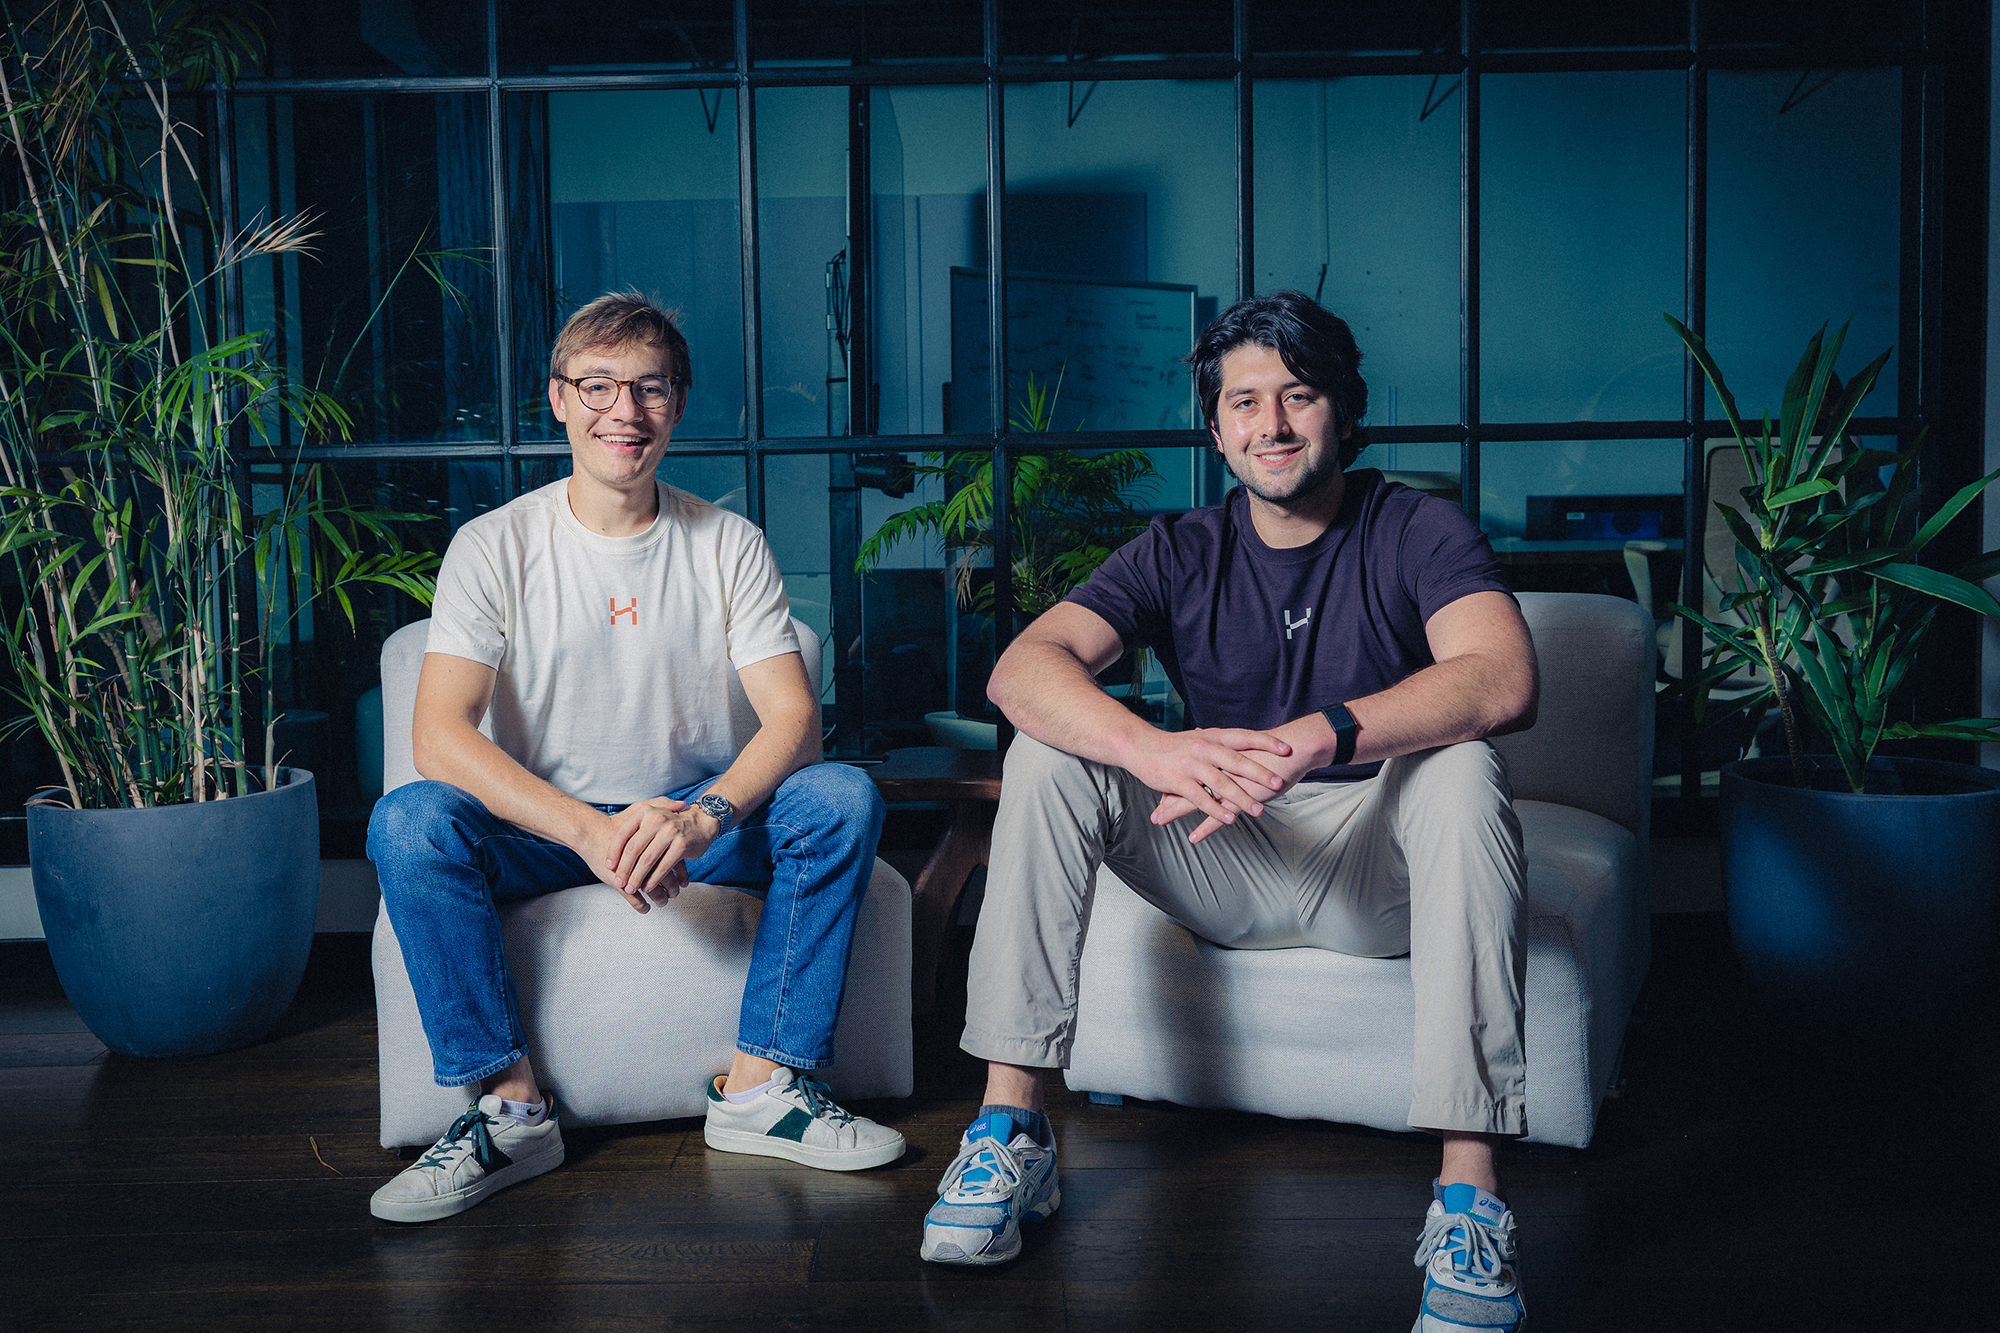
Greenwall did not choose an unfamiliar technical partner. He and Pratt had grown up together. Pratt brought experience building software companies; Greenwall brought the transaction background and the commercial argument. In June 2024, as Henry launched, the pair were preparing to join Y Combinator’s summer program.
The initial proposition was easy to picture. A broker supplies deal information; Henry helps produce the presentation and financial analysis. The target documents included offering memorandums, which introduce an investment opportunity, and brokers’ opinions of value, which set out a valuation case. Both require research, numbers and a presentation that looks as though the firm meant to send it.
Greenwall’s view of the customer was unusually explicit for a business selling automation: “Brokers are here to stay.” He wanted brokers spending more time originating business and maintaining relationships. The software was being designed around their continued importance to the transaction.
The ambition was already broader than slides. Henry’s launch description at Y Combinator discussed combining messy internal information with outside data and eventually accelerating the wider deal process. A deck was a concrete place to enter the workflow. It was also a place where a customer could inspect the result.
“Brokers are here to stay.”
Sammy Greenwall, at Henry’s 2024 launch
In February 2025, Henry announced a $4.3 million seed round co-led by Susa Ventures and 1Sharpe Ventures. The company then had eight full-time employees. Its pitch addressed the analyst’s assortment of recurring tasks: gathering property information, reviewing financials, researching markets and assembling the deliverable.
Greenwall could explain the value without beginning with a model architecture. He had been the person doing the work. A broker uploading an underwriting model wanted material suitable for a client, with the relevant research incorporated. The distance between those two states was Henry’s business opportunity.
- 2018Capital markets at Toll Brothers
- 2019Co-founds Lev
- 2024Launches Henry; YC Summer 2024
- 2025Henry announces $4.3M seed funding
- 2026Henry Deal and a $16.5M Series A announcement
The customer has a perfectly good objection
Any founder selling a specialized AI product now has to answer an awkward question: why pay for this when a general-purpose assistant is already available? Greenwall addresses it directly. In his public writing, he points to the information a firm has accumulated through doing business: previous valuations, verified transactions, ownership research and customer knowledge.
He describes the problem in everyday office objects. A spreadsheet contains one piece of a deal. A folder holds another. A colleague remembers something useful. The presentation is working from a slightly older version. Each component may be serviceable, while the work of keeping them together becomes a job in itself.
His proposed answer is a system that retains what the brokerage learns. That is an aspiration for Henry, with a practical test attached: does the next transaction benefit from the work completed on the last one? A document generator can produce another document. Greenwall wants a firm's accumulated work to influence what comes next.
His advice to potential adopters is correspondingly concrete. Pick a painful workflow, make the improvement measurable and give a small team responsibility for deploying it. He has suggested a 60-day implementation rather than a prolonged sequence of demonstrations. It is advice from someone selling a product, certainly, but it has the virtue of allowing the customer to judge a result.
Firm knowledge
Comps & research
Buyer & lender lists
A schematic of the workflow Henry describes. The broker reviews the work and manages the relationship.
A bigger brief for the deck business
By July 2026, Henry was announcing Henry Deal and a $16.5 million Series A led by FirstMark, with participation from Thomson Reuters Ventures and existing backers. The company had reached more than 150 firms, including Newmark and Berkadia. Henry Deal extended its brief into buyer lists, memos and underwriting.
There was a pleasing reversal among the investors. FirstMark’s Adam Nelson had initially been skeptical about selling into commercial real estate brokerage. He subsequently led the round and joined the board. The founders had persuaded somebody who understood their market well enough to have reservations about it.
The change of mind is more interesting than a frictionless fundraising tale. Greenwall was choosing a customer base with established habits and strong opinions about its own work. Adoption meant demonstrating enough practical value to earn a place inside those habits. The skepticism was part of the commercial problem the company had to solve.
In his later account of choosing FirstMark, Greenwall said another offer valued the deal roughly 20 percent higher. He and Pratt preferred the New York connection and the prospect of working with Nelson over a longer period. It was a choice about the company they wanted to build beyond the financing announcement.
That same period brought a more direct expression of Henry’s ambitions. Greenwall described needing to become a platform after customers had come to know the business for decks. The successful entry product had also become a description the founders needed to outgrow.
The analyst still sits across the table
Greenwall’s explanation of Henry to NAI Global returns to the young analyst struggling to meet the standard expected of a presentation. He remembers working late and being criticized for decks that were not good enough. It is a less glamorous founding image than the flash of inspiration, and considerably easier to recognize.
He now talks about moving further into deal intelligence: helping brokers understand a market, identify an asset’s relevant demand drivers and anticipate a buyer’s questions. He also wants Henry working inside the tools brokers already use. The ambition follows his early frustration through the office, from the document to the decisions behind it.
For Greenwall, the recurring subject is how a skilled person’s day gets spent. There is still a property to understand, a valuation to defend and somebody to persuade. Henry’s wager is that more of the preparation can happen before the broker reaches for the phone. The former analyst has given the slide deck quite a lot to answer for.
Follow the work
Company, conversations and further reading.