In October 2015, Ryan Feit sat in the third row of a Securities and Exchange Commission hearing. The subject was crowdfunding. The reading material ran to 686 pages. For most people, this would qualify as a regrettable way to spend a weekend. Feit compared the final rules to “unwrapping a present.” He had been waiting three and a half years.
The present required some assembly. Congress had passed the JOBS Act in April 2012, creating a route for ordinary Americans to invest in private companies through regulated online offerings. The details still had to be worked out. Feit had helped advocate for the change, co-founded SeedInvest with James Han, and started a company whose intended market was partly waiting on Washington.
There is a familiar startup story about moving quickly. Feit’s is about learning which parts of the world will move with you, which require persuasion, and which have a public comment period. His business needed software, investors and promising companies. It also needed rules that would let those people meet.
The road trip that became a business
Feit came to this problem from inside finance. He studied finance and accounting at the University of Wisconsin-Madison, worked in investment banking at Lehman Brothers, and moved into private equity at Wellspring Capital Management. Before he began arguing for wider access to startup investments, he had worked in the institutions through which capital already travelled.
In 2010, he left private equity for Wharton with the intention of starting a company. Around him, friends were trying to finance theirs. Han, his eventual co-founder, was among the entrepreneurs spending money and time searching for angel investors around the Northeast. Some gave up. Finding someone who might write a cheque had become a separate occupation.
Feit saw an awkward mismatch. Internet platforms could connect strangers to lend money or support a creative project. Yet startup fundraising still depended heavily on personal introductions and geography. The promising business and the interested investor might both exist; arranging their meeting remained an expensive scavenger hunt.
He joined the movement for securities-law reform in 2011. SeedInvest followed in 2012. The opportunity was specific: bring the search, paperwork and investment process online, while building a marketplace that investors could use with some understanding of what they were buying.
A launch with a waiting room
SeedInvest’s platform launched in February 2013. Its early audience was accredited investors. The broader crowdfunding provisions were still being implemented, so the business began with the customers it could legally serve. The great opening of startup finance would arrive through several doors, on different dates.
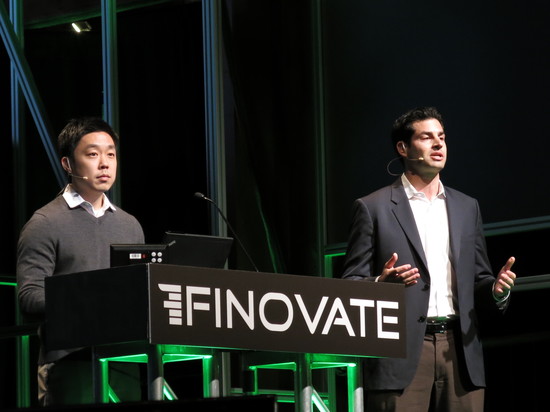
At Finovate that spring, the product demonstration was full of practical machinery: a due diligence dashboard, a permission-based data room, electronic document execution, identity checks and funds transfers. A virtual boardroom offered reporting and signatures. Behind the appealing idea of investing online sat the less photogenic work of making a securities transaction function.
That list says something about Feit’s approach. He was bringing an investor’s habits into a web product. A founder needed a way to raise money, but an investor also needed documents, checks and a continuing relationship after pressing the button. The interface was only one piece of the transaction.
By October 2013, more than 400 startups had applied and more than 600 accredited investors had signed on. SeedInvest was accepting roughly 1.5 percent of applicants. Feit wanted the selected companies to stand out rather than disappear into an enormous directory. Opening access for investors could coexist with saying no to most businesses.
The platform passes its own hat
In April 2014, SeedInvest tried a useful demonstration: raising money for itself through its own platform. It secured $1 million from accredited investors online, alongside $2 million already committed by venture firms. A company selling a different way to finance a business had become a customer of that way.
There was a practical reason to combine professional and individual investment. Feit explained that negotiating a separate valuation with thousands of people would be unwieldy. A lead investor could establish terms; individuals could then join the round on those terms. The crowd brought participation without requiring every participant to conduct a private negotiation.
For a founder, that arrangement addressed a familiar problem: the hours spent fundraising are hours unavailable for the company itself. Feit’s earlier experience watching classmates hunt for angels had become a product question. How much of that search and administration could a platform take off their hands?
His favourite reading was 686 pages long
When the SEC adopted the final crowdfunding rules in October 2015, Feit’s enthusiasm had very particular objects. Funding portals could exercise judgement about which companies to admit. Certain costly financial-statement requirements had been eased. Platforms could receive an equity interest as compensation, subject to conditions. These details would shape whether small offerings were economical.
He also described unfinished business. Liability remained a concern. His response to the rules was celebratory and argumentative at once: pleased with concessions, explicit about problems that survived. Anyone expecting a simple victory lap would have received a rather thorough memo instead.
The distinction between legislation and implementation runs through his career. A law can establish an opportunity while leaving the business economics unresolved. For a small company, compliance costs have to make sense relative to the money being raised. For a platform, its responsibilities have to be understood before it invites the public inside.
Regulation Crowdfunding became effective on May 16, 2016. More than four years had passed since the JOBS Act was signed. SeedInvest had spent that interval building a business and helping argue about the framework that would govern its next chapter.
A wider door, a selective doorman
Feit’s argument for access included a substantial warning about what access meant. In a 2015 essay, he stressed that private companies were risky and difficult to sell, and that investor education mattered. Platforms acting as simple listing services could damage the whole experiment. A new market would have to earn trust through its behaviour.
In conversation with Jason Calacanis in 2016, he discussed SeedInvest’s low acceptance rate and the importance of evidence that customers wanted a company’s product. He also described requiring businesses to commit to quarterly investor updates. The relationship was supposed to continue after the fundraising campaign ended.
That combination gives the story its tension. Feit wanted more people to participate in private markets, while maintaining a filter on the opportunities they saw. Neither a screening process nor a polished website could make early-stage investing predictable. The platform’s job included helping people understand that uncertainty.
“This piece of legislation now allows small and medium-size businesses to turn customers into investors.”Ryan Feit, at Reinventing Our Communities, 2016
His vision extended beyond a transaction between strangers. Customers might become owners and advocates for a business they already knew. The financing could strengthen a company’s relationship with its community. That possibility helped explain why he kept returning to access as a business problem worth solving.
Circle, then a move south
Circle closed its acquisition of SeedInvest in March 2019, after FINRA approval. Circle’s founders, Jeremy Allaire and Sean Neville, described a future connecting private securities with blockchain technology. Their ambitions included tokenized financial assets and new ways for businesses to interact with investors. SeedInvest would continue operating with additional backing.
It was a meeting of related ideas: use the internet to change how value moves, and work through the institutions that regulate that movement. Feit’s experience making startup investment work online had relevance to a company exploring digital financial infrastructure. The acquisition connected his crowdfunding work to a different part of finance.
In June 2021, he moved to Miami to open a SeedInvest office. The company reported more than 235 startups funded and a network exceeding 500,000 investors and entrepreneurs. It also reported accepting just one percent of more than 50,000 startup applications. Growth had preserved the company’s selective approach.
Miami supplied a new local setting for the original question of finding capital. Early SeedInvest investor Melissa Krinzman, managing partner at Krillion Ventures, had become the city’s Venture Capitalist in Residence. Feit wanted the office to source local startups and build partnerships. Online access still benefited from people knowing their neighbours.
The access question keeps travelling
In October 2021, Circle announced that Feit would join Allaire and Dante Disparte as a co-host of The Money Movement. The programme explored digital money, startups and the internet financial system. A founder who had spent years explaining securities rules now had another venue for discussing how financial markets might change.
The corporate story changed again when StartEngine completed its acquisition of SeedInvest assets in 2023. The transaction followed Circle’s decision to concentrate on its core business. SeedInvest’s independent platform was headed for consolidation under StartEngine. The business Feit had helped create was entering another owner’s plans.
His later advisory work kept a familiar focus. In November 2023, he publicly discussed advising ALTI, which sought to give individuals access to private equity funds. A February 2024 announcement also identified him as an adviser to Pari Passu Venture Partners, whose investment network connected accredited investors with venture opportunities.
These are different products for different audiences. The recurring interest is recognisable: make an investment process easier to reach and easier to navigate. Feit’s career began inside established financial institutions, then moved toward building and advising businesses that offered additional routes into private markets.
The third-row seat in 2015 remains a useful place to understand him. He could see a business opportunity in a pile of rules, and feel pleasure at the prospect of reading them. Some founders dream of the day the paperwork disappears. Feit had spent years trying to get the right paperwork written.