Patrick Boyaggi had an unusual qualification for starting a mortgage company: he had declined to get a mortgage from the bank where he worked. Here was someone who understood the machinery, yet found a better deal elsewhere. For a borrower who sees the bank’s first offer as the natural end of the conversation, that is a useful little disturbance.
- Compare purchase and refinance offers from participating lenders.
- Shopping is free; lenders pay Own Up.
- Advice is available, but the customer route varies.
- Experian acquired the business for $175 million in April 2026.
The bank lost its own banker
Boyaggi, Mike Tassone, and Brent Shields started RateGravity in 2016. Boyaggi and Tassone brought banking experience; Shields brought software engineering. The problem they chose was wonderfully ordinary: a borrower could be perfectly acceptable to several lenders and still receive different prices. Knowing how to borrow and knowing how to shop were separate skills.
“I’m the guy that didn’t get a mortgage from his own bank.”Patrick Boyaggi, co-founder
Own Up occupies the space between those skills. It arranges connections to lenders, compares offers, and supplies mortgage expertise. The borrower gets another view of the market before making a commitment. The company’s mission is to prevent overpayment, a promise whose usefulness depends on what offers are available for the particular person doing the shopping.
First, make the offers readable
The service begins with information about the borrower and the loan they need. Own Up’s FAQ says initial shopping uses a soft credit inquiry. Its tools help people explore affordability, compare loan options, and update preapproval letters on demand. The lender issues the preapproval; Own Up does not make the credit decision or fund the mortgage.
Customers include first-time buyers, existing homeowners refinancing, and people financing second homes or investment properties. Refinancing can mean changing the rate and term or taking cash out. Real estate agents are another route into the service: Own Up offers to help their clients navigate financing while the agent manages the property search.
The human component matters, though it needs describing accurately. Own Up’s current explanation says some customers work with a Home Advisor; others connect directly with a participating lender or partner. The experience varies with circumstances and selections. A reader should therefore understand the concierge as an available service route, rather than assume every inquiry produces the same relationship.
Free has a business model
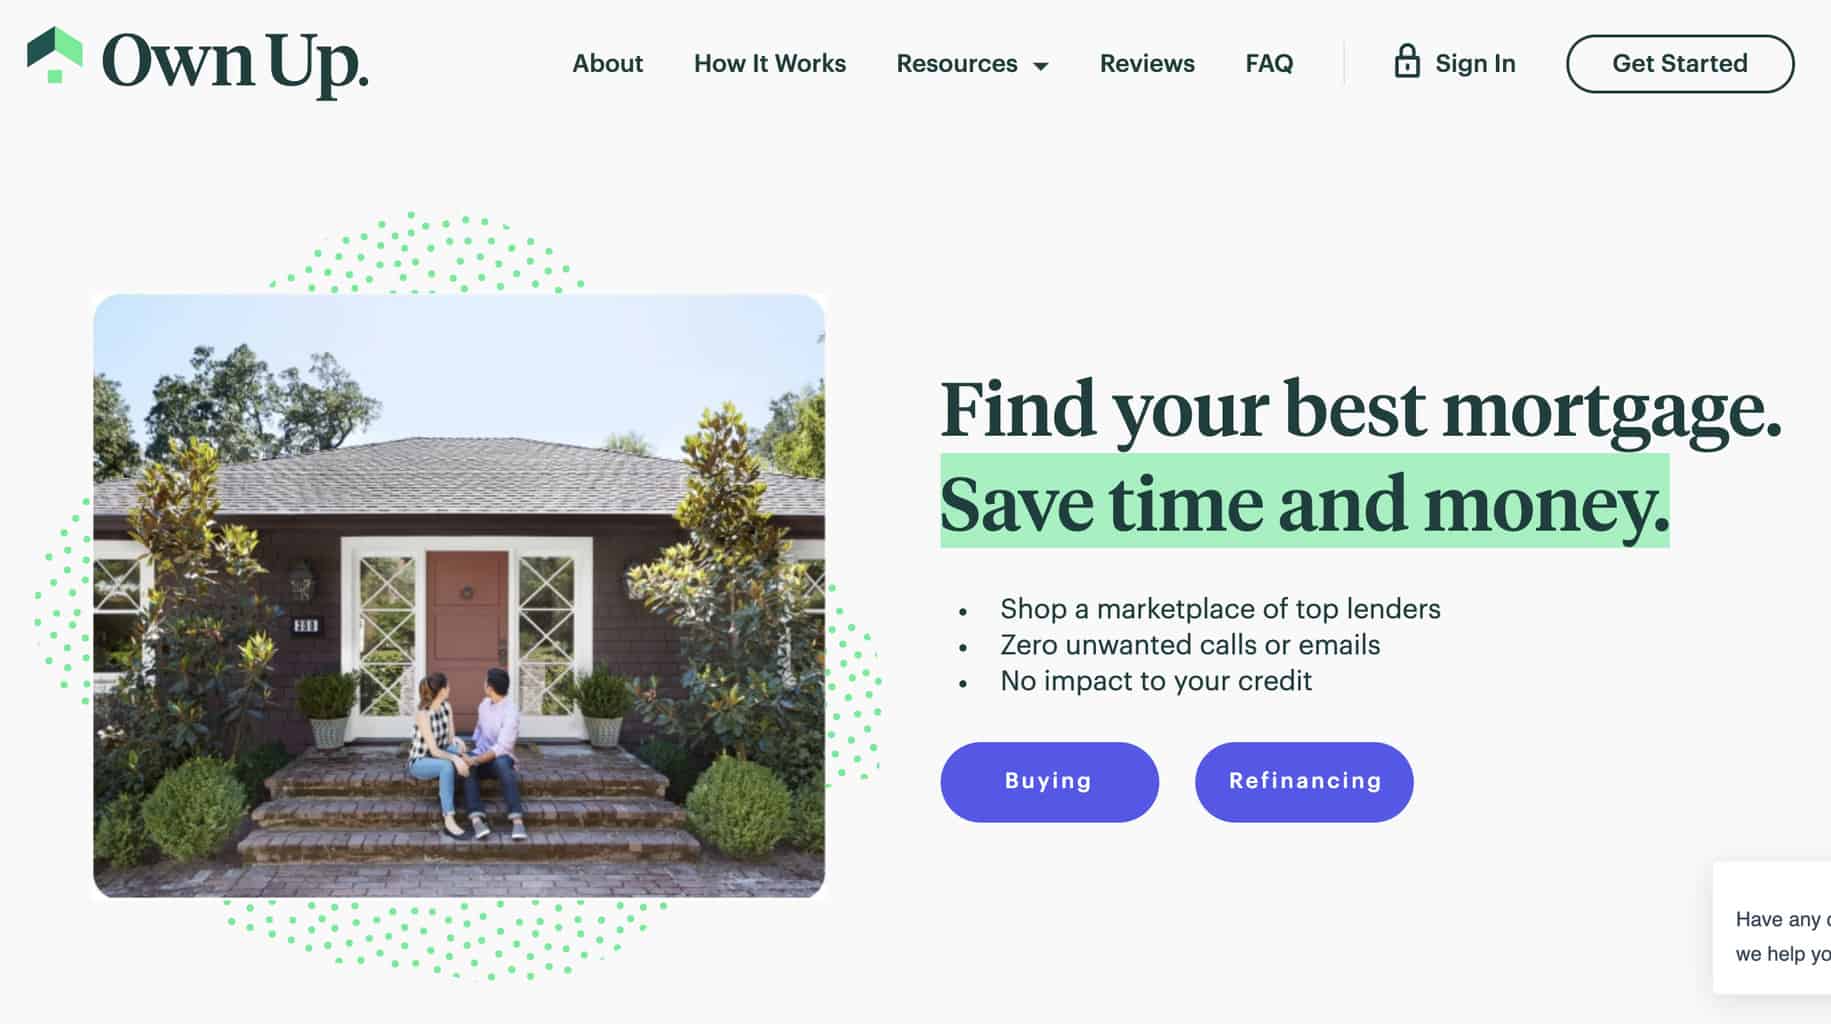
Own Up charges shoppers no service fee. Lenders pay it. The company’s provider disclosure says it may receive compensation when someone applies for and receives a provider’s product. Its website also describes the business as an advertising-supported comparison service and says compensation does not determine mortgage offer order or placement.
That places Own Up among mortgage marketplaces and brokers, competing for attention with comparison services such as LendingTree, local brokers, and direct shopping at banks or credit unions. Its pitch combines comparison technology with mortgage expertise. The important boundary is market coverage: participating lenders are a selection, and Own Up explicitly says its offers do not represent every available company or product.
Lender compensation supports the marketplace.
Free shopping also leaves the actual mortgage bill intact. Appraisal, application, and other lender charges may apply. Own Up’s terms separate a shopping inquiry from a formal loan application. Finding a promising offer is one stage; satisfying the lender’s requirements is another.
The small print beneath $28,217
Own Up advertises average lifetime interest savings of $28,217. The calculation compares $184,269 in benchmark interest with $156,052 for loans in its marketplace. A precise number invites confidence. Here, the explanation underneath it deserves equal attention.
The analysis covers conventional 30-year mortgages secured in 2023, using same-day Optimal Blue market indices and a weighted average loan of $503,711. Own Up says it did not normalize for credit score, state, or property type. Those are meaningful differences between borrowers. The figure describes the company’s comparison, rather than proving what an otherwise identical customer would save by switching.
A better name. A bigger doorway.
One early mismatch was the name. RateGravity described downward pressure on rates. Customers helped the founders recognize that the aspiration was owning a home. In 2019, the company became Own Up. That change offers a practical lesson for other businesses: a technically accurate name can still miss the reason someone cares.
Expansion needed capital and distribution. Own Up announced $8.5 million in October 2019 and $12 million in January 2021. In August 2022, a company-announced $25 million round accompanied a Realtor.com relationship. Financing information could meet buyers while they were looking at listings, closer to the moment a mortgage becomes urgent.
Experian supplied a larger doorway. Its February 2026 acquisition announcement described Own Up’s network of more than 40 lenders and plans to add mortgage shopping to Experian Marketplace. Experian’s financial results subsequently confirmed completion in April for $175 million. The strategic logic is clear: put mortgage comparisons near an existing audience already thinking about credit. Whether that produces better individual offers still depends on the borrower and lender.
Borrow the habit
For the person using it, the useful comparison extends beyond the rate. A lower rate can come with upfront points; a smaller monthly payment can reflect a different loan term. The Loan Estimate brings the rate, projected payments, and closing costs into a standard document. Comparing those details is where a shopping tool and an informed conversation can earn their place.
That also explains the limits of convenience. A marketplace helps when its participating lenders have suitable options and the borrower has time to compare them. An outside credit union or existing banking relationship may still offer a better fit. A buyer with an unusual property or financial profile may need a lender outside the network. Own Up can shorten the search, but the decision still belongs to the person who will make the payments.
The useful habit is to make a mortgage offer compete. Own Up says its comparisons can help customers negotiate with an existing lender, even when they stay put. Its contribution is making alternatives easier to inspect. It cannot make a limited lender network exhaustive, turn an inquiry into approval, or guarantee that a competing quote will win. Boyaggi’s original decision remains the memorable part: someone who knew the bank well still checked somewhere else.