At $119.9 million, a pastel becomes a very public possession. In May 2012, Leon Black bought Edvard Munch’s The Scream, the 1895 version, for a price that briefly set the auction record for a work of art. The buyer was initially anonymous. The number was already famous. For someone whose professional reputation rested on finding value where other people hesitated, it was an arresting receipt.
There is an obvious joke here about the expression on the figure’s face when the bill arrived. But Black’s purchase deserves more than the usual arithmetic of extravagance. His business life and his cultural life repeatedly turn on a question: what is something worth when other people’s estimates are unreliable? In finance, he helped build a firm around that problem. In collecting, he entered rooms where scarcity makes a mockery of the comparable sale.
The same life now poses a harder question about judgment. Black co-founded Apollo Global Management in 1990 and led it for roughly three decades. He left in March 2021 amid scrutiny of his financial relationship with Jeffrey Epstein. The institutions, gifts and acquisitions remain part of his record. So do the payments and the questions that followed him out of the executive suite.
An education in other people’s trouble
Black’s route into finance began with an education that had room for things without a market quotation. He graduated from Dartmouth in 1973, summa cum laude, having studied philosophy and history. Harvard Business School followed, with an MBA in 1975. The sequence is a useful reminder that the eventual private equity founder had first spent years examining ideas and the past.
His parents supplied a family connection to both business and art: his father, Eli Black, headed United Brands, while his mother, Shirley Lubell, was an artist. There is no need to turn that pairing into a tidy explanation of the adult son. It does, however, make the coexistence of balance sheets and pictures in his later life less surprising.
From 1977 to 1990 he worked at Drexel Burnham Lambert, rising to lead mergers and acquisitions and co-head corporate finance. Drexel’s bankruptcy in 1990 ended that chapter. Black and fellow Drexel alumni, including Marc Rowan and Josh Harris, started Apollo that year. A failed institution supplied experienced people for a new one. Wall Street occasionally recycles more efficiently than it admits.
The founding moment matters because it puts financial distress near the beginning of the story. Apollo’s early identity was tied to leveraged buyouts and troubled securities. A company could be an unattractive proposition at one price and an interesting one at another. The work involved finding which claims on its business were worth owning, and under what conditions.
The price comes first
Black’s own explanation of Apollo’s approach emphasized its credit training. In a 2014 interview, he described a culture comfortable examining the whole capital structure. That meant considering debt as well as equity, and investing during downturns when other buyers pulled back. The reasoning was practical: the route into a company could change with its circumstances.
“We just like to buy good companies for low prices.”
Leon Black · 2014
The sentence has the cheerful simplicity of an instruction that is much easier to give than to carry out. A low price can signify opportunity, but it can also be a perfectly accurate warning. The investor has to decide whether the market has become too pessimistic, or whether the business deserves its discount. Buying cheaply is only the beginning of the argument.
A simplified illustration, not an Apollo portfolio. Contract terms and the assets available determine actual recoveries.
By 2011, Apollo had gone public. Black’s legacy became attached to an institution with shareholders, successors and a life beyond its founders. That distinction becomes essential later. A firm can retain an investment method while changing its leadership. A founder’s personal conduct can also create consequences for the organization, even where the organization disputes having participated in the underlying relationship.
The collector buys the bookshelf
The Munch purchase placed Black inside a conspicuous transaction involving an unusually scarce object. Of the four versions of The Scream made between 1893 and 1910, the 1895 pastel was the only one in private hands when MoMA exhibited it in 2012. The other three belonged to Norwegian museums. There was no warehouse of equivalent examples waiting for a patient shopper.
MoMA’s exhibition put the pastel beside prints by Munch from its own collection. That setting changed the encounter. An auction result turns an artwork into a number; a museum gives visitors time to look beyond the number. Black’s ownership and the public’s access briefly occupied the same room, without requiring every visitor to have an opinion about private equity.
In October 2012 came a purchase with a different relationship to the wall: Phaidon Press. The publisher made books about art, design and other cultural subjects. Buying a publishing house put Black on another side of collecting, helping own the machinery through which pictures and ideas reach readers. A painting needs a place to hang. A publisher needs people to keep turning pages.
The transaction was a family acquisition for an undisclosed price. At the time, Black described plans to develop the publishing program, expand geographically and introduce digital products. Those were stated ambitions for the business. They show an interest in circulation as well as possession: the cultural object reproduced, explained and shipped, rather than kept as a single scarce thing.
Books had already become a family project through Jewish Lives. In his note introducing the series, Black traces its origin to a question from one of his sons about Jewish identity and continuity. The foundation’s partnership with Yale University Press dates to 2010. Its chosen form was biography, giving large questions a human scale through individual lives.
That origin has a domestic specificity missing from most accounts of billionaire philanthropy. A child asks a question. The response becomes a publishing project. Black’s stated hope was that the books would deepen understanding of Jewish life. The gesture fits his earlier education in history and philosophy, though it would be presumptuous to claim that a college syllabus had secretly planned the whole enterprise.
Five colors, one college courtyard
Back at Dartmouth, Leon and Debra Black committed $48 million toward a visual arts center announced in 2012. Debra, a Broadway producer, belongs in this part of the account as a participant, rather than an accessory to a donor’s name. The couple’s support connected collecting with spaces in which students could make work of their own.
Leon and Debra Black’s commitment toward Dartmouth’s visual arts center.
The family also commissioned Ellsworth Kelly’s Dartmouth Panels for the center’s opening. Five painted aluminum panels face the arts plaza: yellow, green, blue, red and orange. They offer an agreeable interruption to the habit of treating a campus as a succession of destinations. Here is a reason to look up on the way somewhere else.
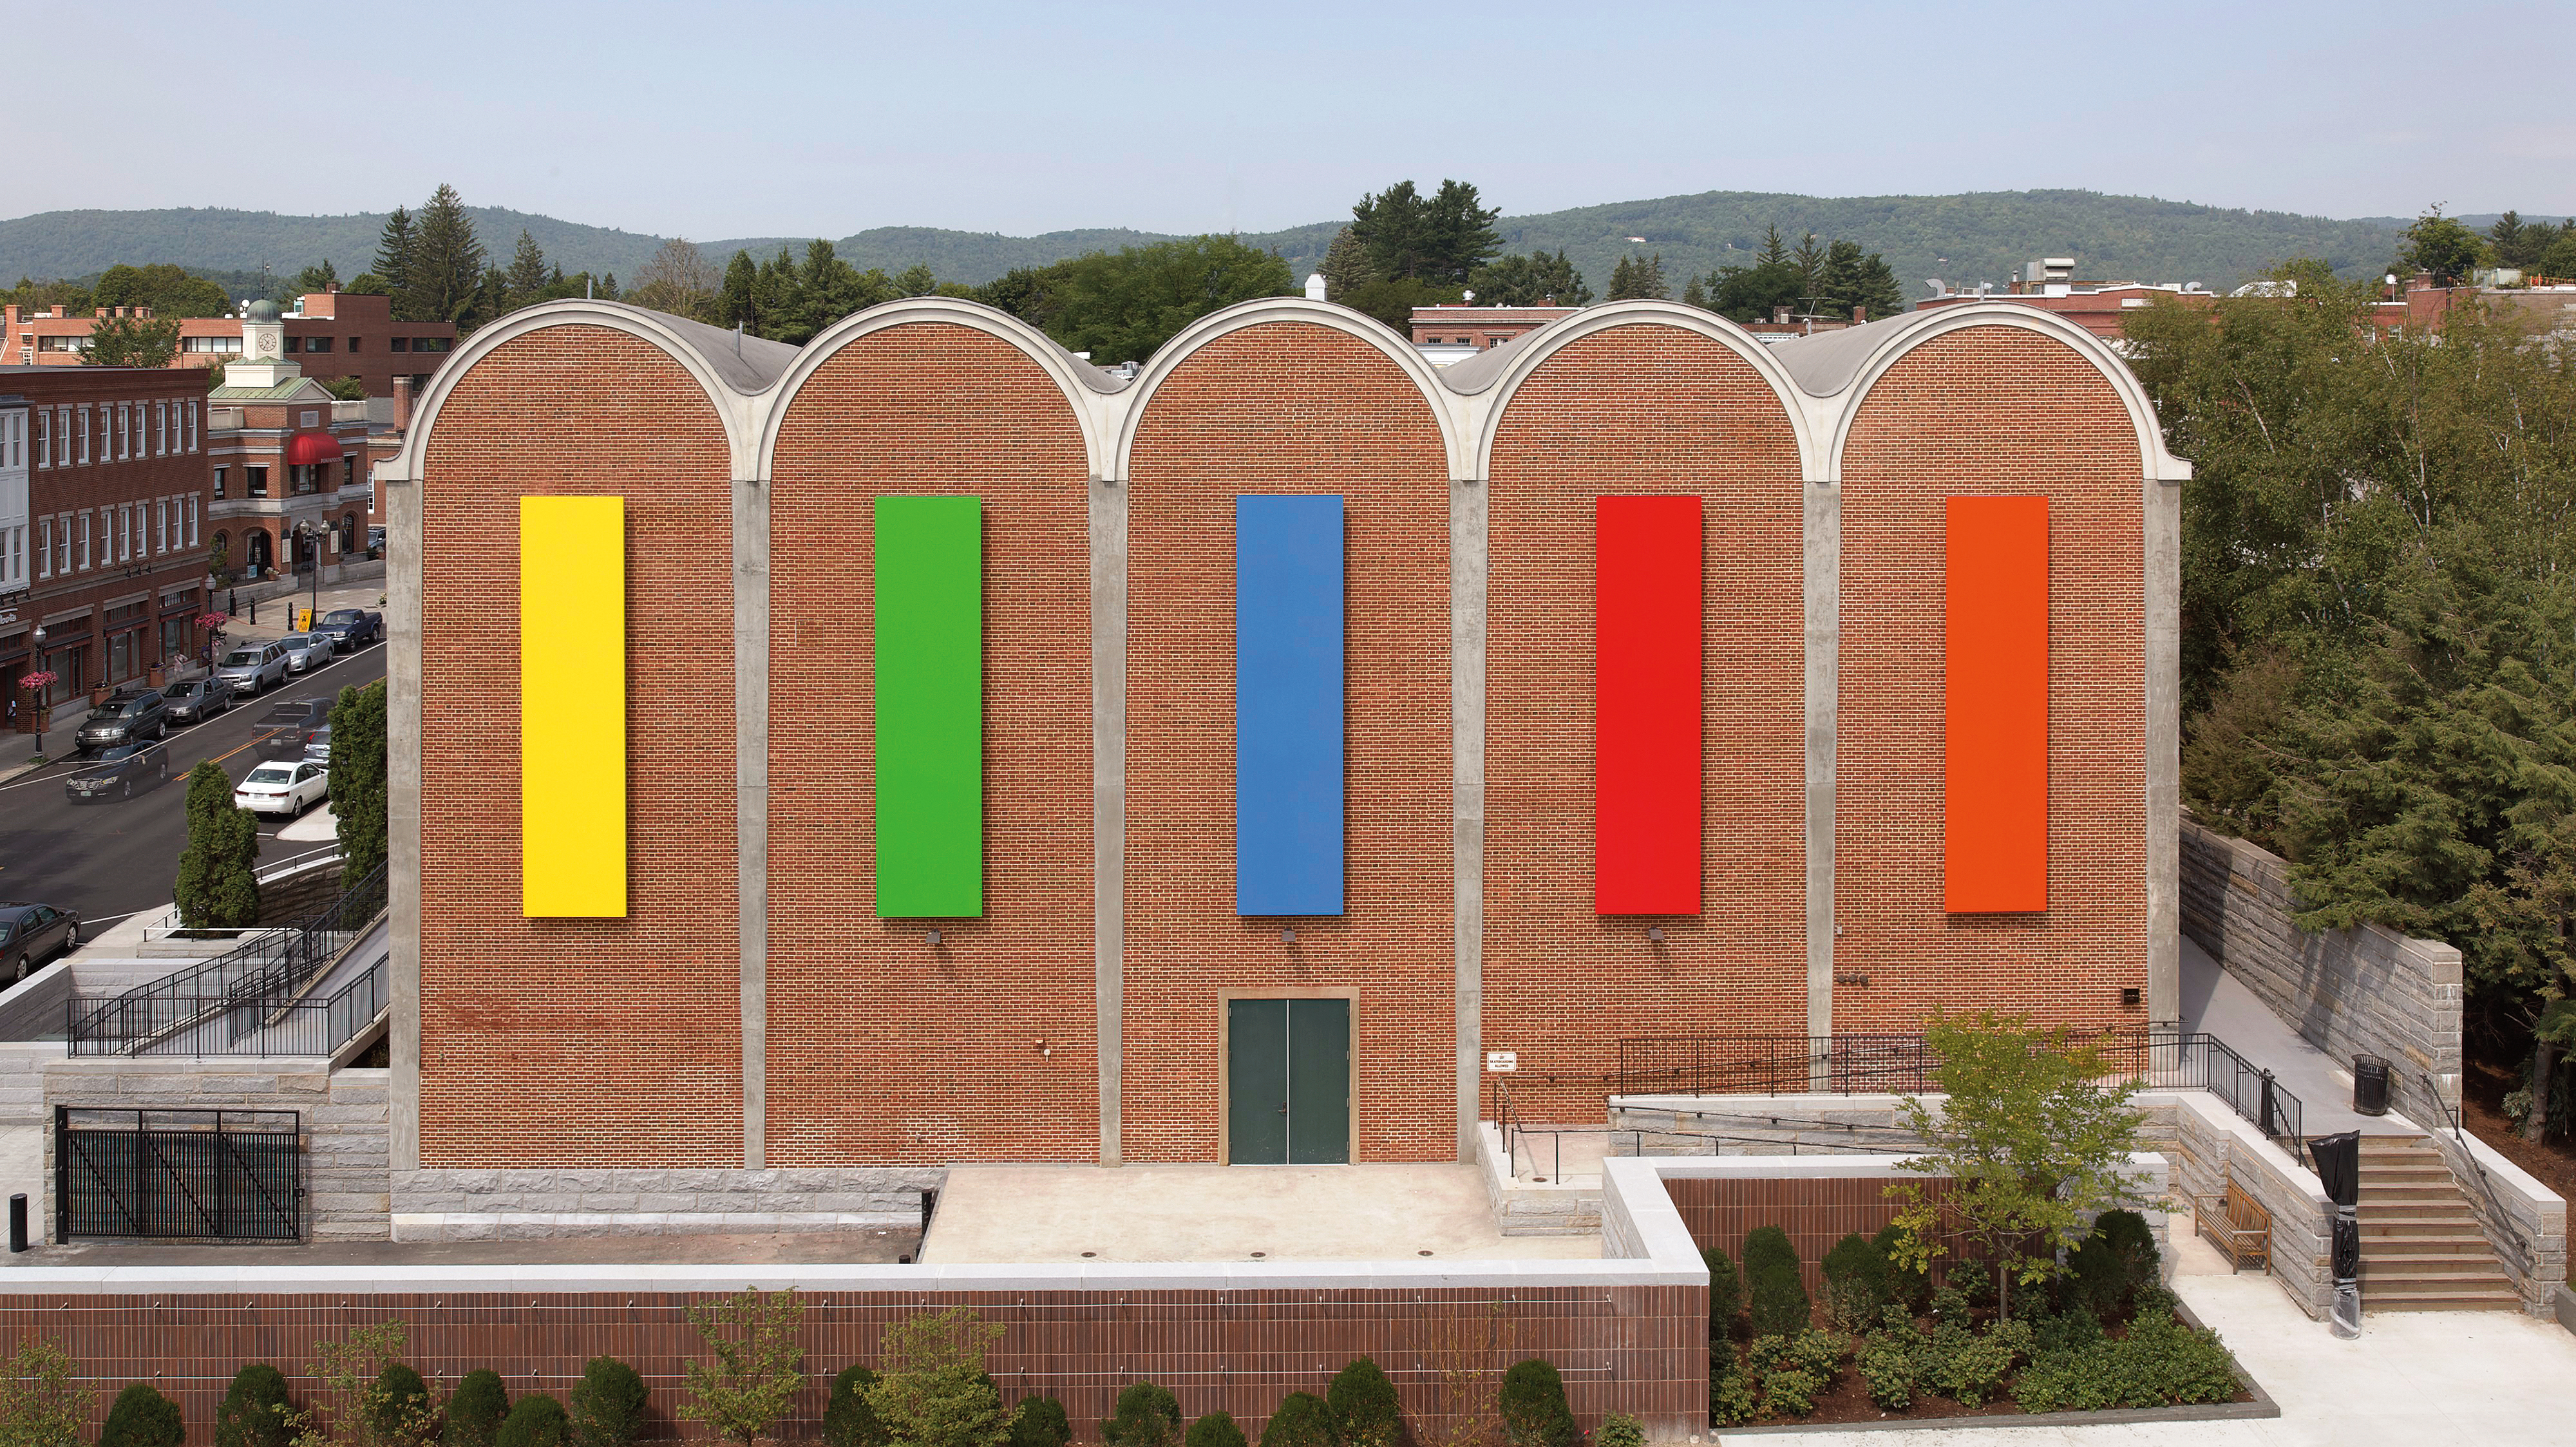
For a collector, commissioning public art makes a different kind of commitment from winning an auction. The work enters other people’s routines. At Dartmouth, it sits within the setting Black hoped would encourage students to “dream big, be courageous, take artistic risks.” Financial risk and artistic risk are distant relatives; the family resemblance should not be allowed to do too much explanatory work.
The relationship that changed the record
Black’s payments to Jeffrey Epstein require their own account. A review conducted by Dechert for Apollo’s board reported in January 2021 that Black had paid Epstein $158 million between 2012 and 2017. These payments came after Epstein’s 2008 conviction. The review characterized the work as tax, estate planning and related services.
Apollo said the review found no evidence that Black participated in Epstein’s criminal activities. It also said Apollo had never retained Epstein and that he had never invested in its managed funds. Those were the findings of a law firm commissioned by the company’s conflicts committee. They were not a court judgment resolving every question about the relationship.
Subsequent scrutiny challenged the completeness of that account. In March 2025, Senator Ron Wyden announced that Senate Finance investigators had identified payments totaling $170 million, $12 million above the earlier figure. In March 2026, he sought further explanations about Black’s financial dealings and tax arrangements. The senator’s claims and questions remain attributable investigative assertions, rather than findings this profile can turn into a verdict.
The leadership consequences had arrived much earlier. In January 2021, Black planned to surrender the CEO job later that year while remaining chairman. By March, he had left both roles. Rowan became CEO. Black also declined to seek another term as MoMA’s chairman amid pressure from artists and activists. Positions that once connected his financial standing to cultural authority had become points of public contention.
The questions outlast the title
In June 2026, Black appeared voluntarily before the House Oversight Committee. Lawmakers said he refused to answer questions about nondisclosure agreements, and issued subpoenas. Black maintained that he had paid Epstein for legitimate services and had been unaware of his criminal activity until 2019. His explanation and the committee’s dissatisfaction belong in the same account.
On September 3, he did not attend a scheduled deposition and sued to block the subpoenas. His lawsuit argued that the demands exceeded the committee’s authority. On September 16, the House adopted a contempt resolution. That action concerned compliance with congressional demands; it was not a criminal conviction. The distinction matters as much as the chronology.
Black’s record leaves the reader with several kinds of valuation. There are investments that helped build Apollo, cultural objects bought and shared, books published, and a campus changed by patronage. There are also decisions about people that brought enduring scrutiny. A talent for pricing assets cannot settle those questions. The auctioneer can close a sale with a hammer. A public life stays open to examination.