The first answer was no. Highland Capital Partners had approached Marcin Kleczynski about investing in Malwarebytes, the security company he had helped build without venture money. There was already a business. There were already customers. An investor knocking on the door did not, by itself, create a reason to let one in.
- The work: Highland invests in consumer and enterprise technology companies and helps their founders build.
- The example: Malwarebytes accepted a $30 million first venture round in 2014, six years after launch.
- The lesson: A useful investor should have a job to do beyond supplying money.
That distinction is a good entrance to Highland. Venture firms can look interchangeable when described through their ambitions. Follow a particular transaction, however, and the machinery becomes visible: an introduction, a constraint, a negotiation, a decision about what the company should become.
Forty hires change the conversation
By July 2014, Kleczynski had a different problem. Malwarebytes was growing quickly and had a queue of prospective hires. He was also considering acquisitions. Highland ultimately supplied $30 million in Series A financing. In CRN’s account, the founder described a backlog of forty hires. Demand had arrived faster than the organization could comfortably expand.
“40 people in the queue to be hired.”
Marcin Kleczynski, Malwarebytes, July 2014
The company’s own announcement gives the scale behind that decision. Its software had been downloaded by more than 300 million people. It had spent years developing free tools and distributing them through forums before formally launching in 2008. Highland was buying into an existing relationship between a product and its users. The money would help expand the technology and the business around it.
There was a practical service attached. Malwarebytes looked to Highland’s network for help with a finance leadership hire. For a founder, that is a more revealing test of an investor than a slogan about partnership: can this person help fill a seat that the business actually needs?
Highland’s investment in Malwarebytes’ first venture round, July 2014.
The $30 million was capital received, rather than a service bill. The founder’s side of an equity bargain involves sharing ownership and accepting negotiated rights. For anyone considering a similar deal, that trade deserves attention alongside the bank balance. More capacity today means sharing some of tomorrow’s upside.
Dresses, defenses, and a warehouse aisle
Highland’s history reaches back to Paul Maeder and Bob Higgins in the late 1980s. Higgins came through foundations and developed an interest in healthcare before moving into venture investing. His Harvard Business School oral history describes a career concerned with how institutions get things done. It is an unexpectedly apt background for someone whose eventual work involved helping small companies become larger organizations.
The firm’s investment history includes Rent the Runway, Malwarebytes, Scopely and Turbonomic. Dress rental, security software, games and application resource management make an unruly dinner party. They also show Highland’s position in the market: a technology investor with experience across consumer demand and enterprise purchasing, rather than a firm confined to one product category.
Selected investments. These examples do not represent portfolio weights.
Its role is to supply investment and company-building help. The portfolio companies make the products. That distinction matters for would-be customers: a business shopping for security software goes to Malwarebytes; a founder looking for an equity partner considers Highland alongside other venture firms. Institutional investors occupy the other side of the arrangement, committing capital to funds that Highland manages.
The model produces different relationships with different obligations. Founders seek money and useful judgment. Fund investors seek investment returns. Highland’s work sits between them. Compensated fund management is documented in its regulatory record; the underlying wager is that ownership in growing businesses will eventually become valuable and liquid.
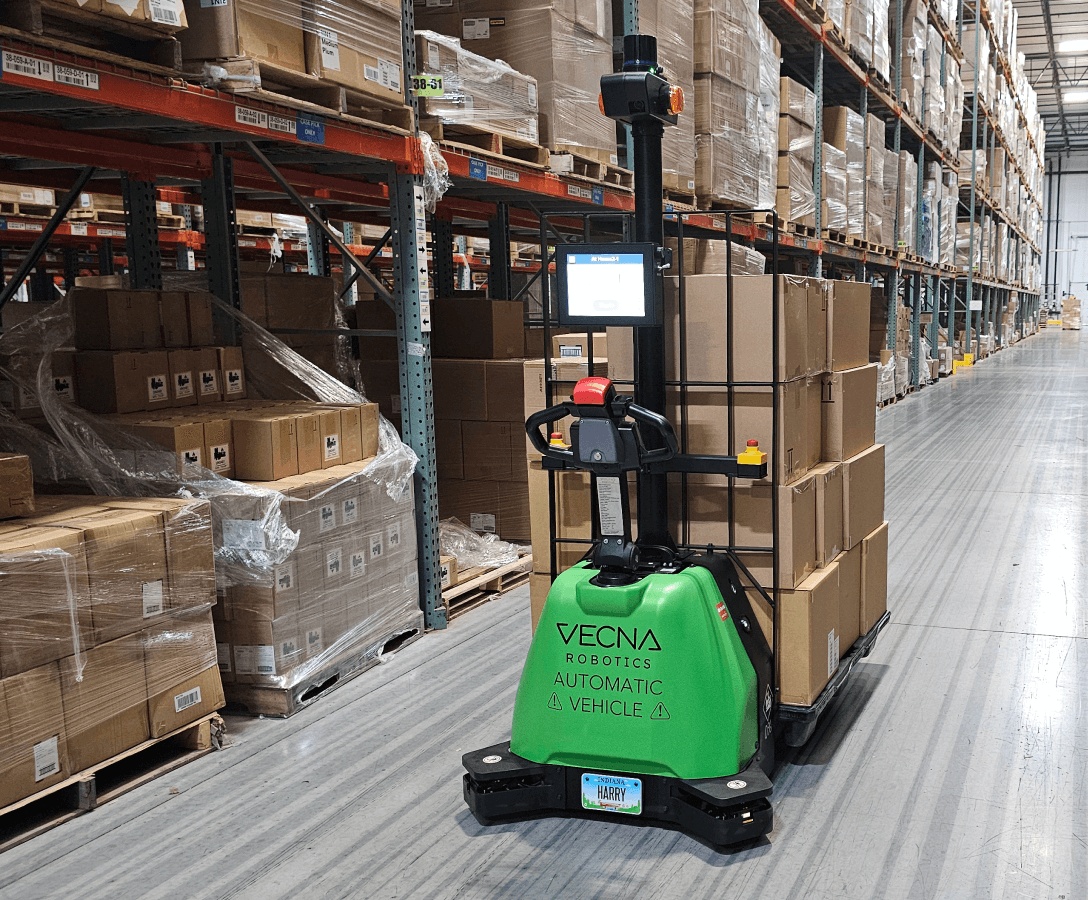
That work continued in September 2026, when Vecna Robotics announced a $31 million round led by Unless, with Highland participating as an existing investor. Vecna said the financing would support deployments, commercial expansion and additional automation capabilities. The figure describes the whole round, across investors. The operating problem is wonderfully tangible: getting cases and pallets through warehouses with less wasted movement.
Against firms such as Accel, General Catalyst or Bessemer Venture Partners, a founder’s choice comes down to the relevant partner, sector experience and terms. Highland’s Malwarebytes example offers a way to assess that choice: ask for evidence of help with the next operating task. A broad portfolio can introduce useful experience from adjacent markets, but breadth alone does not tell a founder who will answer a difficult call. References from other founders, and a clear account of what the investor contributed after financing, are more useful than counting recognizable logos on a website.
A logo is not the whole return
An investment history needs its awkward chapters. Highland backed online education company 2U. In September 2024, 2U emerged from Chapter 11 as a private company; its existing common shares were cancelled without consideration. That event does not establish Highland’s own realized return. It does demonstrate why a familiar portfolio name, or an earlier public listing, cannot settle the question of lasting financial success.
Highland has also faced scrutiny of its own operations. In 2022, it agreed to a $95,000 SEC penalty, censure and a cease-and-desist order over pay-to-play rule violations involving compensated advisory services after a covered associate’s political contribution. It settled without admitting or denying the findings. An investor’s record includes the administration of money as well as its selection of companies.
What a founder can borrow
The useful lesson from Malwarebytes is a sequence: establish demand, identify the constraint, then decide whether outside capital can remove it. Keeping a conversation open leaves room for circumstances to change. Asking a prospective investor to solve a specific hiring problem makes the promised support testable.
This is a poor fit when a founder wants to retain all ownership, or when the company’s ambitions cannot support the growth and eventual liquidity an equity investor needs. Customer-funded expansion remains a real alternative. Highland’s second yes is interesting precisely because the founder had already made the first no. Money became useful when there was something definite for it to do.