Francisco Oliveros had a blunt assessment of the industry in which he had spent much of his working life. Writing after Mexico’s September 2017 earthquake, the chief executive of Seguros SURA México said its performance had been poor. It was an unusually uncomfortable place to begin an insurance argument: with the people selling the promise.
He wanted insurers to examine why customers hesitated to buy from them. His proposals were practical: explain the terms, widen distribution, design coverage around real needs and respond promptly to claims. A contract could be perfectly presentable and still leave a customer confused. The small print had acquired a rather large reputation.
“el desempeño de la industria no ha sido bueno”
Francisco Oliveros · February 2018
Those words carried the weight of an operating career. Oliveros had managed underwriting and distribution, led a Mexican insurer through a turnaround and stayed through a change of ownership. His criticism came from someone who had been responsible for making the business work.
The engineer inside the insurance office
Oliveros studied industrial engineering at Universidad Iberoamericana, with a specialization in production. Before becoming a chief executive, he spent 14 years at AIG México. His roles included Marine Profit Center Manager and Commercial Lines Underwriting Director; his final six years there were spent as Sales & Distribution Director.
That sequence placed him on different sides of the same transaction. Underwriting concerns the risks a company accepts. Distribution concerns how its products reach people. At the top of an insurer, those responsibilities have to meet. A product people want must also be one the company can responsibly provide.
By 2012, he was representing RSA México as its CEO at the G-20Y Summit. His contemporary biography described an operation with 335 full-time-equivalent employees and seven Mexican branches, selling through agents, brokers, partners and banks. These were the working parts of the organization he was leading, years before it carried the SURA name.
A business that had to change its numbers
Oliveros became CEO of RSA México in 2008. The financial position demanded attention. Contemporary reporting on the later acquisition described an operation that had recorded operating losses of 60 million pesos and, by 2015, was reporting profits of 50 million pesos. The change took years.
before the turnaround
reported for 2015
Historical reported figures. Different periods; no annual trend is implied.
His account of the work emphasized commercial strategy and underwriting. Those are consequential choices for an insurer: which business to pursue, how to price it, what risks to accept and how to serve the resulting customers. A turnaround has to become an accumulation of such decisions before it can become a number.
In 2016, Moody’s affirmed RSA México’s rating with a stable outlook as the operation entered its SURA chapter. The assessment pointed to technical performance, risk administration and low volatility in results. For Oliveros, the transaction arrived after eight years spent addressing the company’s commercial and underwriting problems.
The customer outside the usual doorway
A distribution agreement announced in March 2011 gives a concrete picture of the expansion effort. Banca Mifel and RSA México signed a ten-year alliance under which the bank would distribute RSA insurance exclusively. Their stated expectations were about 500,000 policies and more than 2.1 billion pesos in premiums. These were targets, rather than a tally of completed sales.
The proposed range included protection for cars, homes, mortgages, payment cards and fraud. Oliveros spoke about meeting financial needs and providing security and confidence. A bank relationship offered a route into insurance through an institution the customer already used. The doorway mattered as well as the product behind it.
By 2015, he was arguing for more attention to underserved people and smaller businesses. RSA’s mass-market division accounted for more than a quarter of its Mexican operation. The company reported that its customer portfolio had grown 512 percent between 2008 and 2014.
His argument linked growth to the design of the offer. People with limited incomes needed products fitted to specific circumstances, so that they were not paying for features they did not need. There was a commercial case for meeting those needs. A household’s modest possessions could still represent a substantial part of everything it owned.
Branches, partners and a phone in the agent’s hand
The organization was also investing in its ability to deliver. At its 2013 year-end gathering, RSA México reported new branches and spending on technology and specialists in infrastructure and construction. The investment was close to four million dollars. Oliveros hosted the gathering alongside the group’s global and Latin American chief executives.
That year, at TecnoAgente, he presented technological platforms and tools available to RSA agents. The discussion concerned smartphones, tablets, applications and internet use. These devices had a workaday purpose: helping agents handle processes more efficiently and provide a more timely service. Technology was being discussed in terms of the person trying to get something done.
The distribution question kept evolving. By March 2017, Seguros SURA was discussing simple, economical products with fewer requirements, delivered through channels close to their intended customers. Its activity also included on-demand coverage for services associated with shared transport and accommodation. The insurance could follow the duration of the service rather than require a broader commitment.
That makes an interesting distinction in his career. Some expansion involved a decade-long bank partnership. Some involved a much shorter unit of time: one service, one period of use. Both required the insurer to adapt to how people were already conducting their lives.
What a missing delivery really costs
Oliveros’s experience in marine insurance later found a public outlet in discussions of freight. In July 2016, he warned companies against treating cargo insurance as an easy expense to trim. He estimated that roughly 92 percent of goods transported in Mexico lacked merchandise coverage at the time.
He emphasized smaller enterprises, for which a lost shipment could create costs they could not recover. The loss extended beyond the contents of a truck. An order might go unfilled, a customer might go elsewhere, and a business’s reputation could suffer. The cargo owner, in his view, needed to take responsibility for arranging protection.
In a separate discussion of theft, he argued that cargo insurance deserved specific attention within a company’s risk management, rather than being treated as an accessory to another policy. Prevention belonged in the conversation too. Insurance advice could include examining how goods moved through yards, warehouses and distribution centers. The argument was about keeping a business functioning before and after something went wrong.
How does the promise feel to the buyer?
Oliveros also wrote about the gap between formal assessments of insurers and what customers actually experienced. In March 2017, he questioned whether evaluations sufficiently captured operational details: how promptly an adjuster arrived, whether damage assessments caused disagreements and whether contract language created confusion.
Those questions moved attention toward service at the point of need. A customer could have been sold a policy efficiently and still encounter trouble when asking the company to perform. Oliveros called for greater transparency and cooperation between the industry and government. His interest was in making the transaction clearer from the customer’s side.
Another column that spring placed financial education at home, early in childhood. He advocated teaching children the value of money and the work involved in earning it. Waiting for a formal school program, he suggested, would leave an immediate task undone. The subject extended his public concerns beyond the moment someone purchased a policy.
Money, contracts and expectations were recurring subjects. They also allowed him to write as more than a spokesperson announcing a product. He was engaging with how people understood financial decisions, and with the responsibilities of companies hoping to participate in those decisions.
A holiday, with room for poetry
His personal life entered a different kind of public conversation in 2017. Oliveros and Érika Zaba, the singer from OV7, had met through a mutual friend and begun their relationship in 2015. They married on July 1, 2017, in San Miguel de Allende, with around 400 guests.
The honeymoon photographs showed a less formal setting for someone ordinarily identified by his executive title. In Budapest, the couple took a bicycle tour in strong sunshine. Their public posts included affectionate messages and a joke about nearly missing a flight when Zaba became absorbed in her phone. Holiday logistics had supplied their own small suspense.
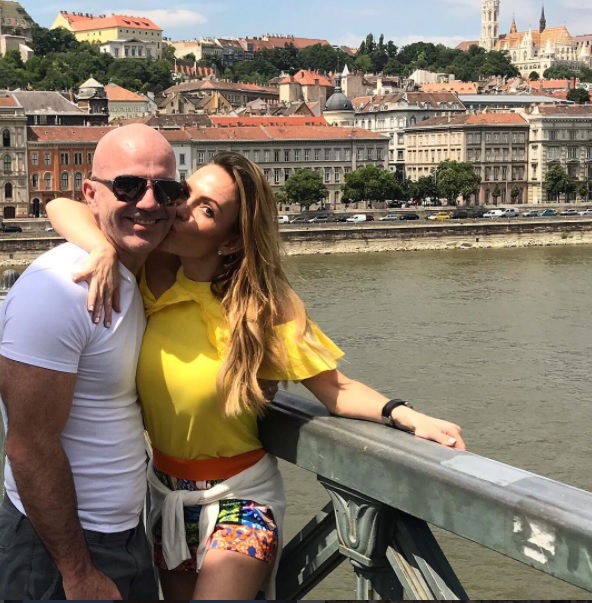
Oliveros described himself as a “poeta cuando sale”, an occasional poet. It is a pleasing detail beside the engineering degree and the insurance career. The travel posts leave room for affection and jokes without requiring either to become a management principle. Even a chief executive is allowed to go on holiday.
The next desk
Oliveros’s tenure leading Seguros SURA México ended on December 31, 2018. The company’s annual report records the date and the appointment of Carlos Alberto Ospina Duque from January 1, 2019. A decade of leadership across the RSA and SURA identities had reached its close.
His subsequent public biography records the founding of a SURA satellite franchise office in June 2019, followed by leadership of Rainmaker Group’s Captives Division from October 2022. He is publicly listed as Acting CEO at Rainmaker, and his professional profile places him in Mexico City.
The sequence carries his career from underwriting and distribution into running companies, then into a different setting for insurance work. Alongside those appointments sits the public argument he made while running the Mexican operation: an insurer should pay attention to how its offer is understood and how its service is experienced. The customer’s belief in the promise deserves a place among the decisions made at the executive desk.
Continue reading
- Professional profile ↗
- Rainmaker Group ↗
- Instagram ↗
- RSA turnaround · 2016 ↗
- Insurance access · 2015 ↗
- Bank distribution agreement · 2011 ↗
- Agent technology · 2013 ↗
- Service and transparency · 2017 ↗
- His earthquake commentary · 2018 ↗
- Cargo and small businesses · 2016 ↗
- Financial education · 2017 ↗
- Career transition · 2018 ↗
- Budapest photo gallery · 2017 ↗
- Captives Division biography ↗