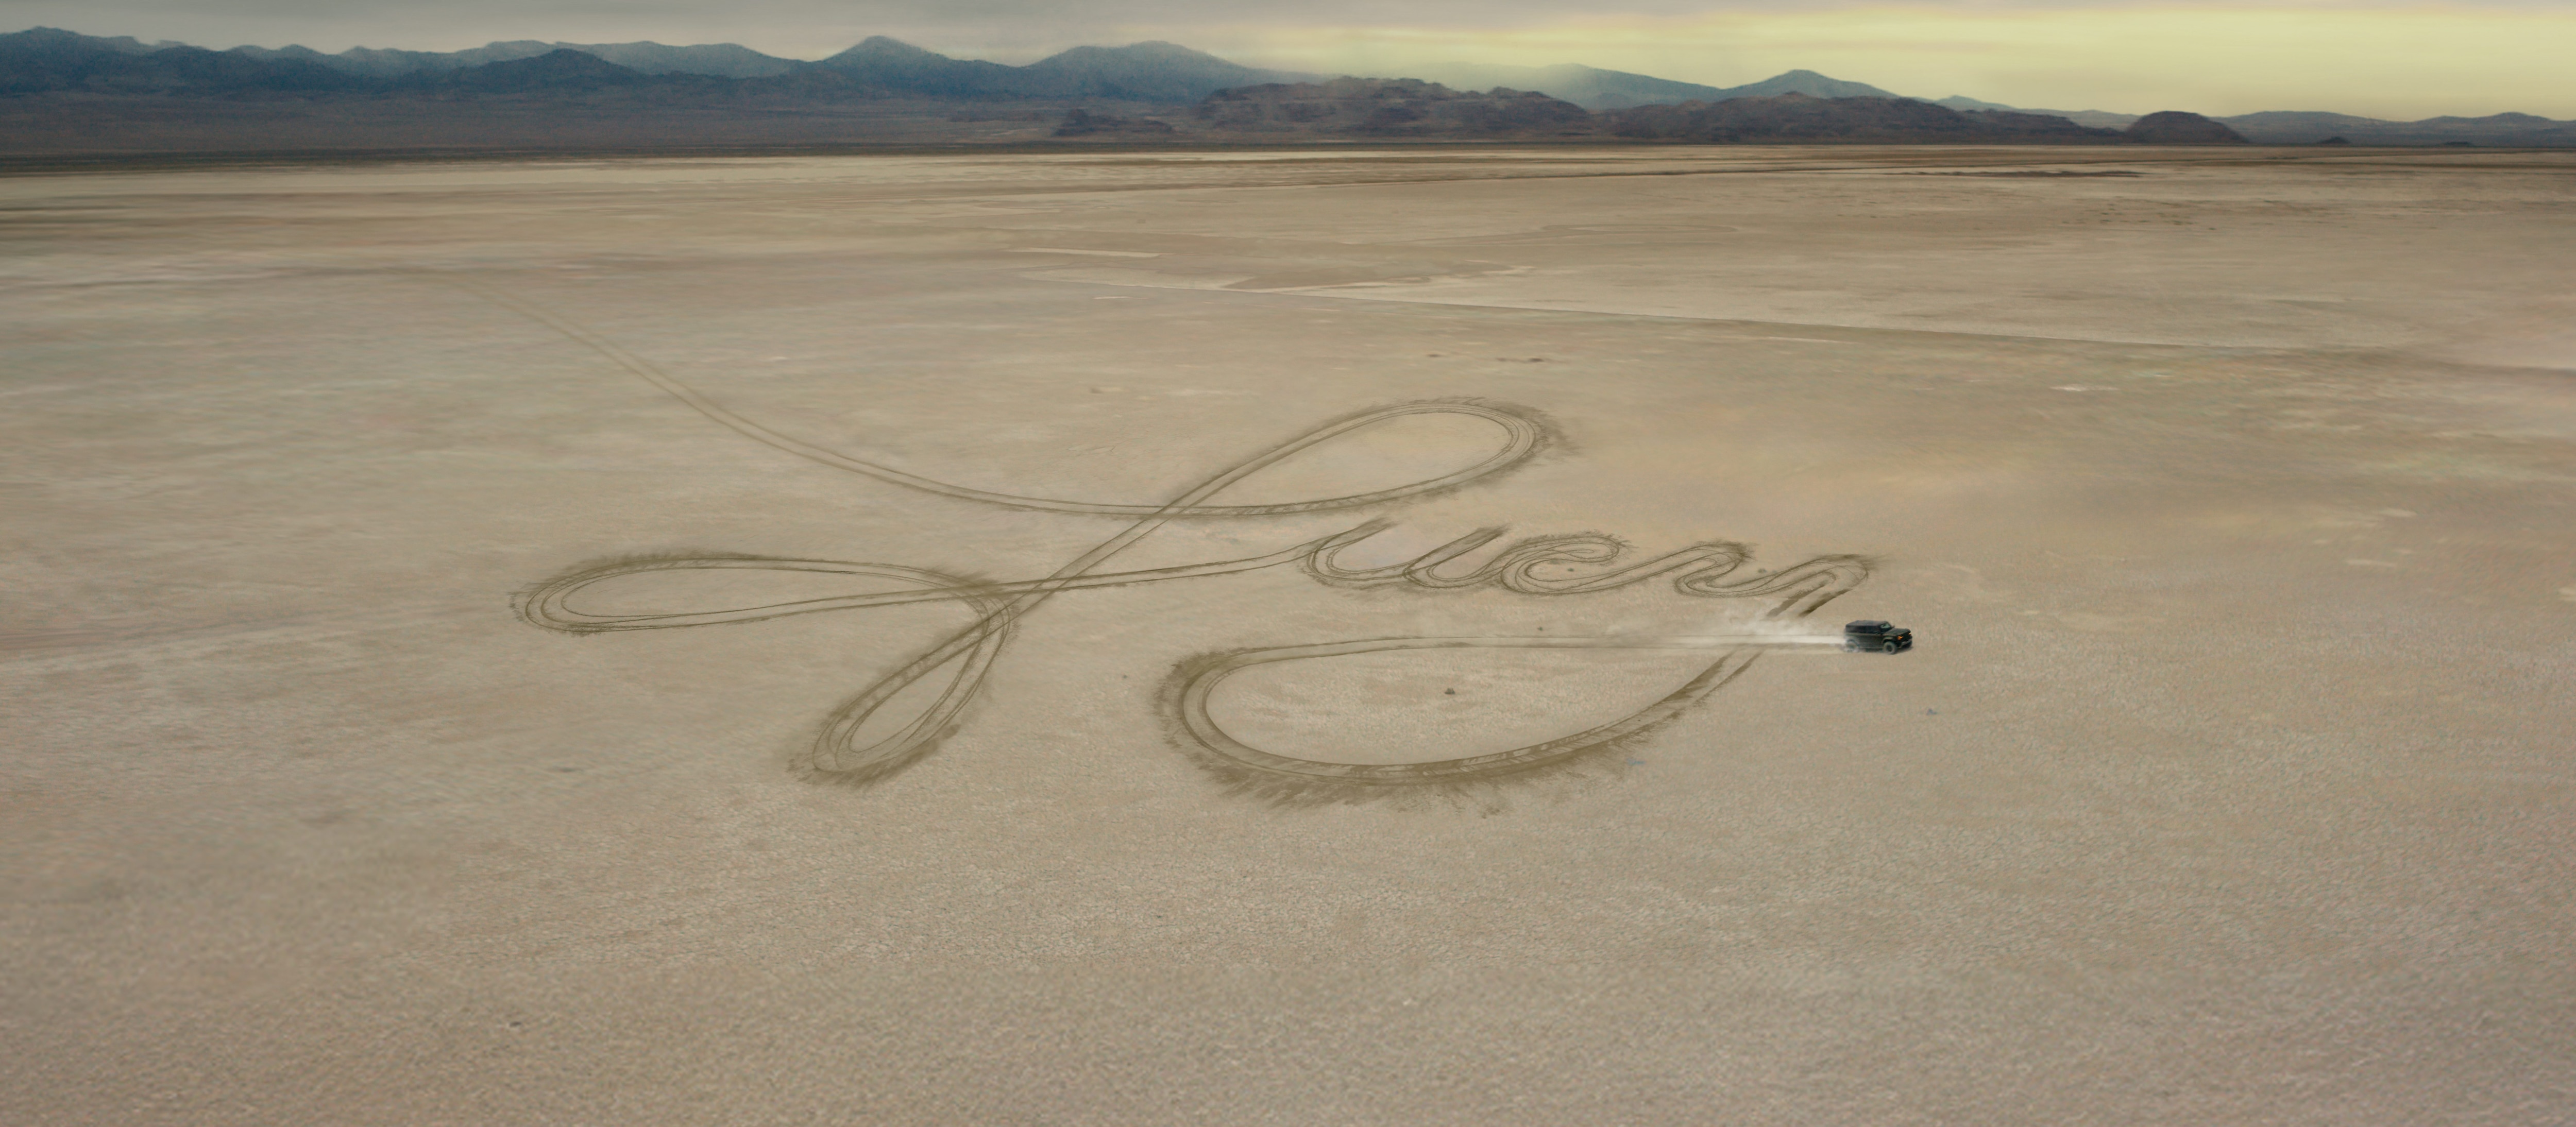
In the Great Salt Lake Desert, a Bronco Raptor became a pen. Its assignment was to write “Lucy” across a salt flat. Elsewhere, a Mustang Dark Horse burned “R Jones” onto an airstrip. Ford Credit’s 2025 advertising production required aerial maps, professional drivers, backup vehicles and three sets of Mustang tires. After 12 hours of filming, editors filled in pieces of the signatures. Making a car sign its name turned out to require quite a lot of paperwork.
- Ford Credit lends to drivers, businesses and the dealers holding the keys.
- Its advantage is its place inside Ford’s sales and ownership system.
- A planned U.S. bank would add deposits to its funding options.
The joke works because a signature is the quiet hinge in a car purchase. Before it, somebody wants a vehicle. After it, somebody owes money. Ford Credit has spent decades organizing that transition. Understanding the company means looking past the machine and noticing the financial arrangements that allow it to move.
The loan before the loan
Ford Motor Company established Ford Credit in 1959. The finance business began with 12 people. Its organizing idea remains straightforward: help customers acquire Ford vehicles and help dealers sell them. Today that includes personal purchases, leases, commercial fleets and the inventory sitting on dealer lots.
That last customer is easy to miss. A dealership needs vehicles before it has buyers for them. Wholesale financing, often called floorplan lending, supplies the money for that interval. Ford Credit also purchases retail financing and lease contracts from dealers. It therefore participates before and after the showroom handshake. The parking lot is, among other things, a collection of financed assets.
Ford Credit supplies financing at both stages.
For a driver, the choices include conventional purchase financing and Red Carpet Lease. Leasing brings mileage, wear and end-of-term obligations; purchasing creates a different path to ownership. The useful product is the contract that fits the driver’s actual use. A pleasing monthly number cannot answer that question by itself.
Other lenders can compete for the same buyer. Banks and credit unions offer alternatives, while GM Financial and Toyota Financial Services run comparable captive-finance businesses around their own brands. Ford Credit’s distinction is its connection to Ford’s dealers, vehicles and manufacturer-sponsored financing programs. It occupies a particular place in the distribution system.
This arrangement gives the manufacturer another way to influence a sale. A special financing program can change the purchase calculation without changing the vehicle. It also makes the lender dependent on demand for the vehicles it supports. Familiarity with a brand is useful; it does not remove the need to judge whether each contract makes economic sense.
A van has a different clock
For a business, the problem changes. A van can earn money while its purchase price is still being repaid. But buying it outright may consume cash needed for payroll, materials or another job. Ford Pro FinSimple, Ford Credit’s commercial financing brand, addresses that mismatch between a useful asset and the timing of cash.
Its Commercial Line of Credit offers extended preapproval for financing or leasing multiple vehicles through one application for up to a year. The charging infrastructure plan extends financing to qualifying equipment, installation and related costs. An electric van needs somewhere to plug in; the infrastructure belongs in the financing conversation.
Consumers have a simpler entry point: online prequalification without affecting their credit score. It gives shoppers an early indication of financing eligibility before the dealership visit. A full application and final approval remain separate steps. The distinction matters because an encouraging screen is easier to misunderstand than a signed contract.
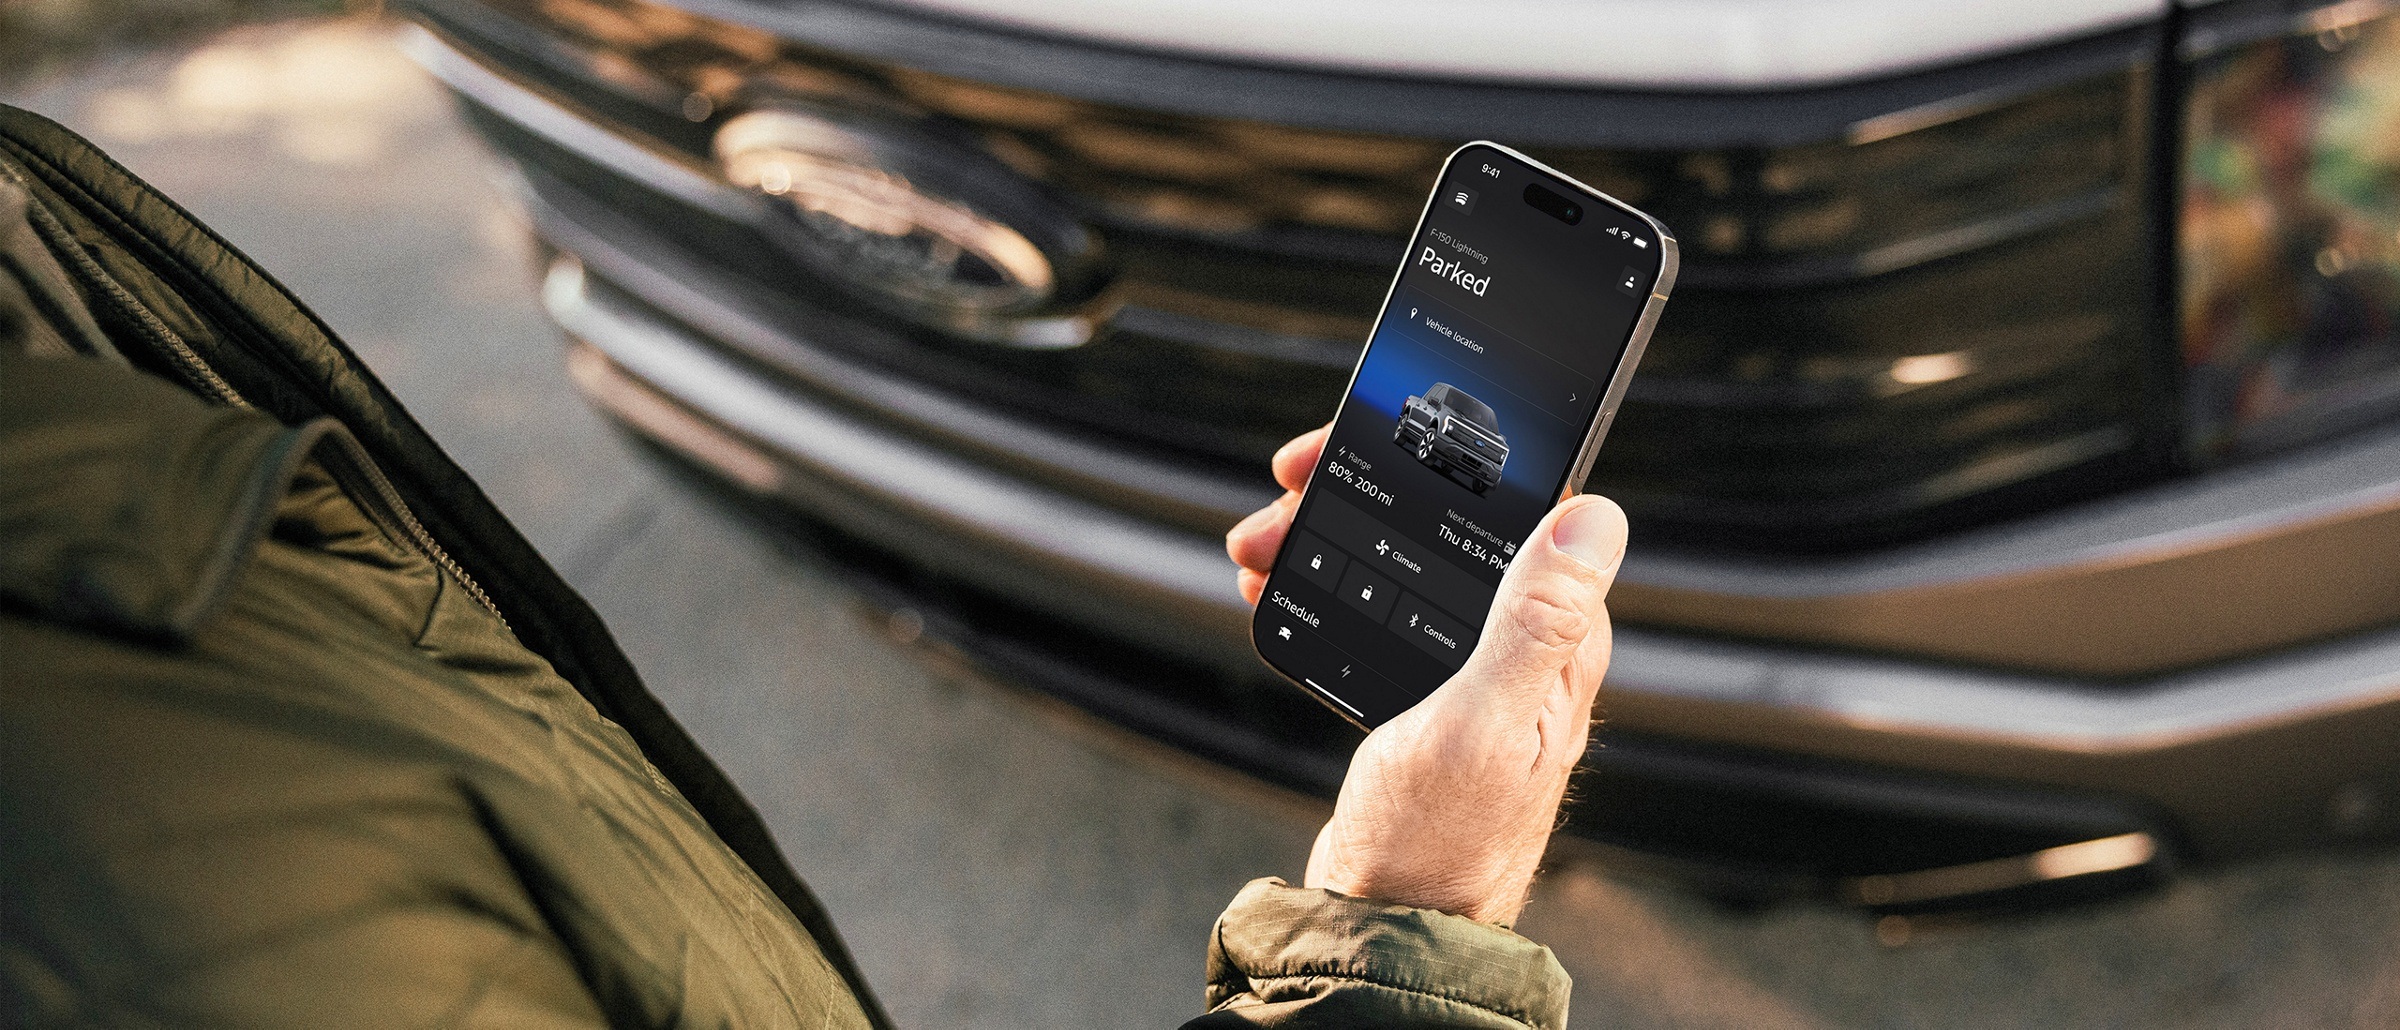
Ford has also bought expertise. Its five-year Stripe agreement, announced in January 2022, covered payments in North America and Europe, including Ford Pro FinSimple. Stripe Connect was intended to route customer payments to the appropriate dealer. For another business studying Ford’s approach, that is a useful distinction: own the customer relationship while bringing in specialist payment infrastructure.
The forecast parked inside a lease
Ford Credit earns financing income and lease revenue, while paying for the money it borrows, running the business and absorbing losses. The vehicle introduces a complication. At the end of a lease, its resale value may differ from the estimate used when the contract began. A forecast made today becomes somebody’s financial problem years later.
In the second quarter of 2008, Ford Credit recorded a $2.1 billion impairment against its North American operating-lease portfolio. Falling used-vehicle auction values had damaged the assumptions beneath those assets. That is a concrete example of the model going wrong: the expected value of the returning vehicle could not be relied upon.
A lease contains a prediction about a vehicle nobody has returned yet.
The lesson travels beyond cars. Financing can make a product easier to buy, but it also creates exposure to funding costs, customer defaults and collateral prices. Ford Credit’s expertise includes managing those exposures. For a business copying the idea, easier checkout is only the visible part of the job.
Ford Credit’s reported EBT, rounded. Profit after funding costs; before income taxes.
The next signature belongs to a saver
In January 2026, regulators conditionally approved Ford Credit Bank, a planned Utah industrial bank. Cathy O’Callaghan leads Ford Credit; Frank Stepan leads the bank project. The proposed institution would accept deposits and purchase auto-finance contracts from independent Ford dealers. Ford says deposits should help lower funding costs over time.
The entry requirement is substantial: at least $1.5 billion in initial paid-in capital and a minimum 15% tier 1 leverage ratio. That capital requirement is distinct from the expense of building the bank. O’Callaghan said setup would take about a year before deposit-taking began. Approval was a milestone, with operations still to be established.
The everyday relationship also matters. Ford Credit ranked first among mass-market lenders in J.D. Power’s 2025 U.S. Automotive Financing Satisfaction Study. Servicing continues after the sales pitch has ended. Ford Credit’s practical lesson is to examine what prevents customers and distributors from buying the core product, then build around that obstacle. The signature opens the relationship. Years of payments test it.