A D+ is an unusual grade to advertise. Bling Capital puts it on a financial model. The seed investor asks founders to sketch their hiring, spending, revenue and cash balance in something they can assemble in 30 to 60 minutes. The point is to expose the assumptions early enough to argue about them. In a business fond of polished presentations, a deliberately rough spreadsheet is a revealing place to begin.
- The job: fund young technology companies and help them find product-market fit.
- The distinction: product operators alongside capital, through the Bling Product Council.
- The useful takeaway: make the customer, the improvement and the spending plan concrete.
Founded by Ben Ling in 2018, Bling operates where a company’s questions are still bigger than its evidence. Who wants this? Who pays? What should the next engineer build? A check gives a founder more attempts at an answer. Bling’s proposition is that experienced builders can make those attempts more productive.
The operator behind the investor
Ling’s résumé helps explain the emphasis. At Google, he founded its commerce group. At Facebook, he was the first director of platform, working on the developer ecosystem and Facebook Connect. At YouTube, he handled partnerships spanning content, devices and APIs. These were jobs involving products, distribution and the people who had to use them.
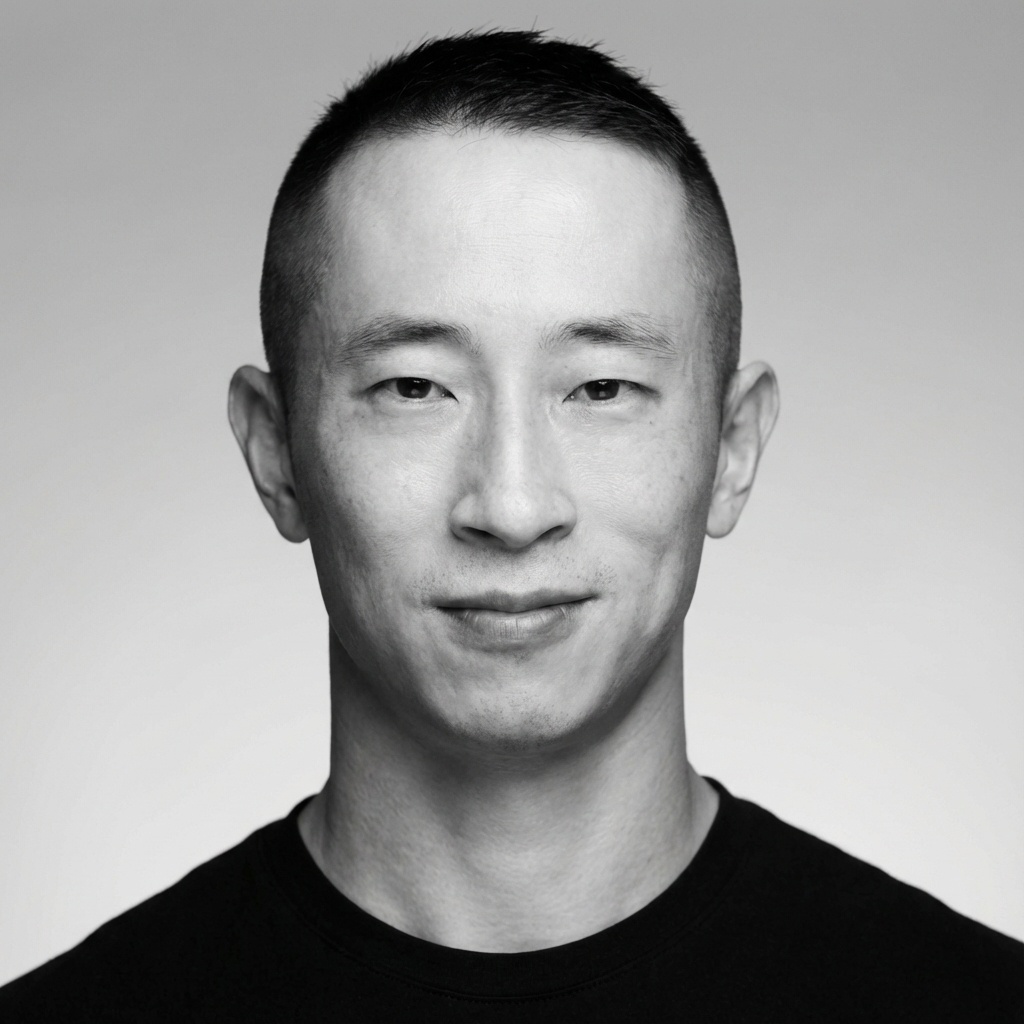
He later became a general partner at Khosla Ventures. His biography separates those investments, including GitLab and Webflow, from angel bets such as Lyft and Square. That distinction matters when reading a venture firm’s wall of company names: an investor’s accumulated experience can predate the fund asking for your pitch.
Kyle Lui brings another route into the same conversation. Before becoming a general partner at Bling, he co-founded ChoicePass, sold it to Salesforce and worked in product management there. He also invested at DCM. In a 2022 LA Venture interview, Lui singled out Bling’s consistent processes for evaluating investments and working with founders. The attraction was an operating method.
A contact list with a job to do
The Product Council is the firm’s most visible expression of that method. Its directory spans product, engineering, growth, design, finance and other disciplines. Portfolio founders can draw on people who have built companies and products themselves. The firm markets a network of more than 100 product leaders.
The important question is what a founder brings to those people. “Help us grow” is difficult to answer. “Customers reach this onboarding step and stop” gives an experienced operator something to examine. The practical value of the council depends on turning access into a specific working conversation.
“Avoid adjectives.”Bling Capital’s customer-problem diligence guide
That two-word instruction appears in Bling’s public homework. Founders must describe the buyer, the urgent problem, the current workflow, the future workflow and the improvement. It is an admirably uncomfortable exercise. A product can sound persuasive when described as seamless. Listing the steps a customer actually takes gives everyone less room to hide.
An editorial sketch of the firm’s customer-problem exercise.
Before the product, a cohort of one
The fellowship moves the relationship earlier. Bling offers up to $500,000 in startup capital, individualized coaching, engineering resources and access to its founder community. Applicants can be pre-launch; the stated funding criterion is no previous funding or less than $500,000 raised. First-time founders are a focus, with repeat founders welcome.
The program calls the participant a “cohort of 1.” That phrase captures the intended difference from a batch accelerator. A founder gets a plan built around their starting point. For someone still testing an idea, the sequence of decisions may matter more than a timetable shared with dozens of other companies.
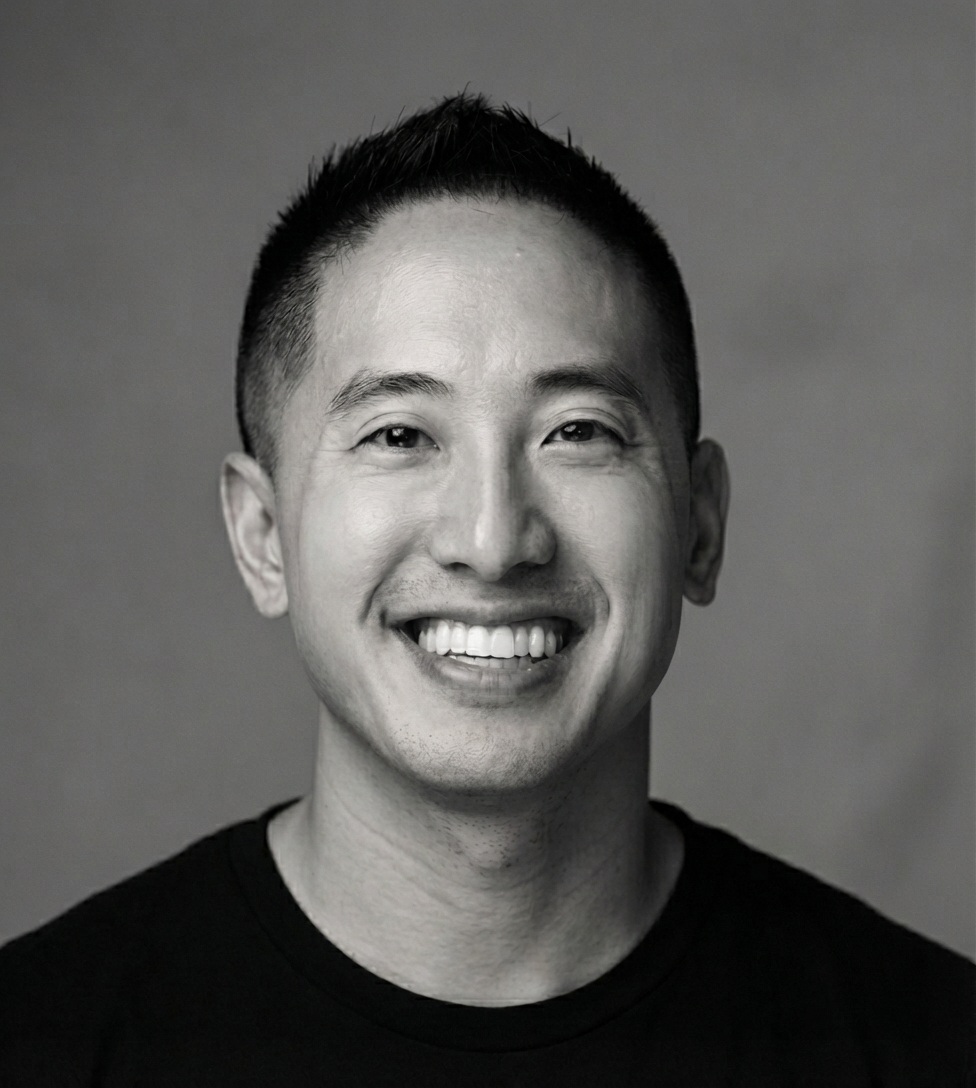
A founder on the other side of the table. Kyle Lui built ChoicePass before investing at DCM and Bling. Photo: Bling Capital.
The money has two jobs
In November 2024, Bling announced $270 million across its fourth fund family, combining seed and opportunity capital. The distinction is useful. One pool helps start relationships with young companies; the other supports follow-on investments. It gives the firm a way to keep backing portfolio businesses after their first round.
Seed capitalKeep backing progress
Follow-on capital
Combined commitments to the fund family, rather than revenue or a valuation of Bling itself.
Its investing interests cover software, consumer businesses, fintech, marketplaces, healthcare and AI, while the current sector page also includes defense and deeptech. This is a generalist technology investor with a product-centered working style. Founders can compare it with other seed firms, or with an accelerator if a structured cohort is what they want.
The economics deserve attention. Venture capital buys an ownership interest and expects investment returns. Founders should evaluate dilution, governance and future financing needs alongside the promised support. A useful advisor cannot make unfavorable ownership terms disappear. The comparison belongs in the same conversation as the size of the check.
The homework you can borrow
Start with the buyer. Bling’s segmentation guide separates the paying customer from the user, then asks how groups differ in pricing, margins and distribution. That prevents a familiar early error: treating everyone who might like a product as an equally reachable customer.
Then connect the plan to cash. The D+ model asks how much capital will buy which milestones over what period. Bling’s hiring exercise adds roles, compensation, equity and timing. Together, these make a useful test: does the proposed team actually produce the product and customer progress the raise promises?
There is a boundary to this approach. Bling’s market-sizing work seeks a credible path to venture-scale outcomes. A small, profitable company can serve customers well while offering too little expansion for that investment logic. An operator network also needs a founder willing to test advice against actual behavior. Access alone proves little.
You can borrow the exercises without becoming a portfolio company. Write the customer’s present routine. Show what changes. Count plausible buyers. Attach spending to the next piece of evidence. The spreadsheet may earn a D+. The decisions it forces deserve a much closer look.