Before the bitcoin trusts and the AI funds, Barry Silbert wanted a glass display case. He was selling baseball cards, and appearances mattered. He recalled borrowing $30 from his parents to make his operation look professional. Even a young trader understood that a milk crate could only take a business so far.
The detail survives because it fits the career that followed. Silbert became interested in assets whose owners needed a better way to find buyers. He built SecondMarket around difficult transactions, moved into bitcoin before it had much institutional furniture, and founded Digital Currency Group. Now he is running Yuma, a company built around the decentralized AI network Bittensor.
His record also includes Genesis, the crypto lender whose collapse brought losses, recriminations and litigation. Any account of his appetite for opening markets has to include what happens when people already inside one cannot get their money out.
Founding years. A career map, not a comparison of investment returns.
A spreadsheet earns its keep
Silbert graduated from Emory’s Goizueta Business School in 1998 and went into investment banking at Houlihan Lokey. His work included restructurings involving Enron and WorldCom. The job offered an education in the gap between owning something and being able to turn it into cash.
Creditors could emerge from a restructuring holding securities they did not want. Someone had to locate a buyer. Silbert saw a business in that awkward interval and founded the enterprise that became SecondMarket in 2004.
It eventually became known for trading shares in private technology companies. Those shares presented a more cheerful version of the liquidity problem. An employee could work at a desirable company and still have wealth that was difficult to spend. A promising future was poor currency at the checkout.
SecondMarket’s early arrangements were modest: five people, five telephones and an Excel spreadsheet, as Silbert later described them. The machinery grew around the transactions. By the time Nasdaq Private Market acquired SecondMarket Solutions in October 2015, the business supplied software for private securities sales and equity management.
Nasdaq said SecondMarket’s software had facilitated more than $2.5 billion in transactions since 2013. That number measured something quite practical: owners and buyers had found a way to complete deals. The acquisition gave the work a home inside an established market operator.
“Do not fear the established.”
Barry Silbert, speaking at Stanford, 2011
A different asset, a familiar obstacle
Silbert began investing in bitcoin in 2012. With it came another access problem. An investor could be interested in the asset while having little desire to learn its custody arrangements. Financial enthusiasm does not automatically confer an appetite for managing cryptographic keys.
Grayscale, which he founded in 2013, addressed that gap through investment vehicles. The Bitcoin Investment Trust began operations that September. Shares in a trust gave investors a different route to bitcoin exposure, with a financial institution standing between them and the underlying asset.
Silbert also backed companies building the surrounding services. In August 2014, his Bitcoin Opportunity Corp. invested $250,000 in India’s Unocoin. By then, the vehicle had invested in more than thirty digital currency companies worldwide, including Coinbase, Circle and Xapo. His interests already extended beyond holding a coin and waiting.
Digital Currency Group, launched in 2015, gathered that approach into a business that invested in companies and operated subsidiaries. The distinction matters. A portfolio stake gives an investor exposure; an operating company gives the group a job to do every morning.
Over time, the group’s businesses included asset management, mining, exchanges and crypto journalism. The connections made Silbert a participant in several parts of the same industry. They also meant that his reputation would be tied to institutions people used, rather than simply to the correctness of an early investment.
In August 2025, he returned as Grayscale’s board chairman. The earlier bitcoin chapter was still active while his attention moved toward AI.
The market that stopped
Genesis makes the continuity in Silbert’s career uncomfortable. He had learned finance by working on failed companies. In January 2023, lending entities within his own group filed for bankruptcy protection, after the withdrawal freeze and crypto credit failures of 2022.
The collapse followed trouble at major borrowers, including Three Arrows Capital, and the wider disruption surrounding FTX. The consequences reached people who had placed digital assets with Genesis directly or through products such as Gemini Earn.
In October 2023, New York’s attorney general sued Genesis, DCG, Silbert and other parties, alleging fraud. An amended complaint in February 2024 expanded the alleged investor losses to more than $3 billion. Silbert and DCG denied the allegations and sought dismissal. Those accusations require attribution; they are not a substitute for a judgment.
A separate SEC action produced a settlement in January 2025. DCG agreed to pay $38 million over misleading statements about Genesis’s financial condition, without admitting or denying the findings. That settlement concerned DCG and former Genesis CEO Michael Moro; it was not a personal SEC penalty against Silbert.
The disputes continued into 2026. On February 24, a federal judge in Connecticut granted some dismissal requests and denied others in Genesis-related securities litigation, allowing claims against Silbert and DCG to proceed. A decision that allegations can proceed is a procedural step, rather than a final finding of liability.
These events belong inside the business story. Creating access brings responsibilities about disclosure, risk and the claims made to participants. For Silbert, the next venture arrives with those questions attached.
Intelligence gets a market
On November 20, 2024, DCG launched Yuma, with Silbert as CEO while he continued to lead the parent company. DCG had first invested in Bittensor in 2021. Yuma gave that interest a dedicated operating business.
Bittensor organizes specialized computational services into markets called subnets. Participants contribute work, validators assess contributions, and token incentives reward participation. The subjects vary: prediction, data, security and other machine intelligence tasks can have their own competitions and evaluation rules.
Yuma takes its name from the network’s Yuma Consensus mechanism. It supports teams building subnets, operates a validator and participates in mining. In this setting, mining includes producing useful computational outputs for particular subnets. The word has followed Silbert into AI with a different job description.
His role is to build around a network he believes should be more accessible. That involves money and engineering, but also translation: helping a startup understand the network, or helping an institution understand what it might be buying.
In October 2025, he brought Greg Schvey in as chief operating officer and Jeff Schvey as chief technology officer. The brothers had co-founded TradeBlock and Axoni; DCG had invested in both ventures. Their move brought an existing set of working relationships into the new company.
Two days after announcing their appointments, Yuma launched an asset management business anchored by $10 million from DCG. Its initial strategies offered diversified exposure to subnet tokens. The resemblance to the Grayscale chapter is easy to see: build an investment route into a market whose technical demands can discourage outsiders.
Connecticut Innovations, the state’s strategic venture capital arm, announced an investment in Yuma Asset Management’s funds that month. Silbert’s argument about participation was acquiring institutional participants.
- 01 / ContributeParticipants produce computational work.
- 02 / EvaluateValidators assess contributions under subnet rules.
- 03 / RewardToken incentives encourage participation.
A simplified view. Each subnet defines its task and evaluation approach.
A place at the table
The same ambition had a smaller, more tangible expression at the University of Connecticut. In June 2025, Yuma and UConn launched BittBridge, a program giving a student team the chance to develop and operate a Bittensor subnet with technical support.
Silbert put the purpose plainly: “The transformative power of AI shouldn’t be limited to a few tech giants or well-funded companies with massive compute access.”
That is an aspiration, and the program supplies a way to test a piece of it. Students have to learn how the systems work. A partnership can provide mentoring and resources; the participants still have to build something. The work begins where the announcement ends.
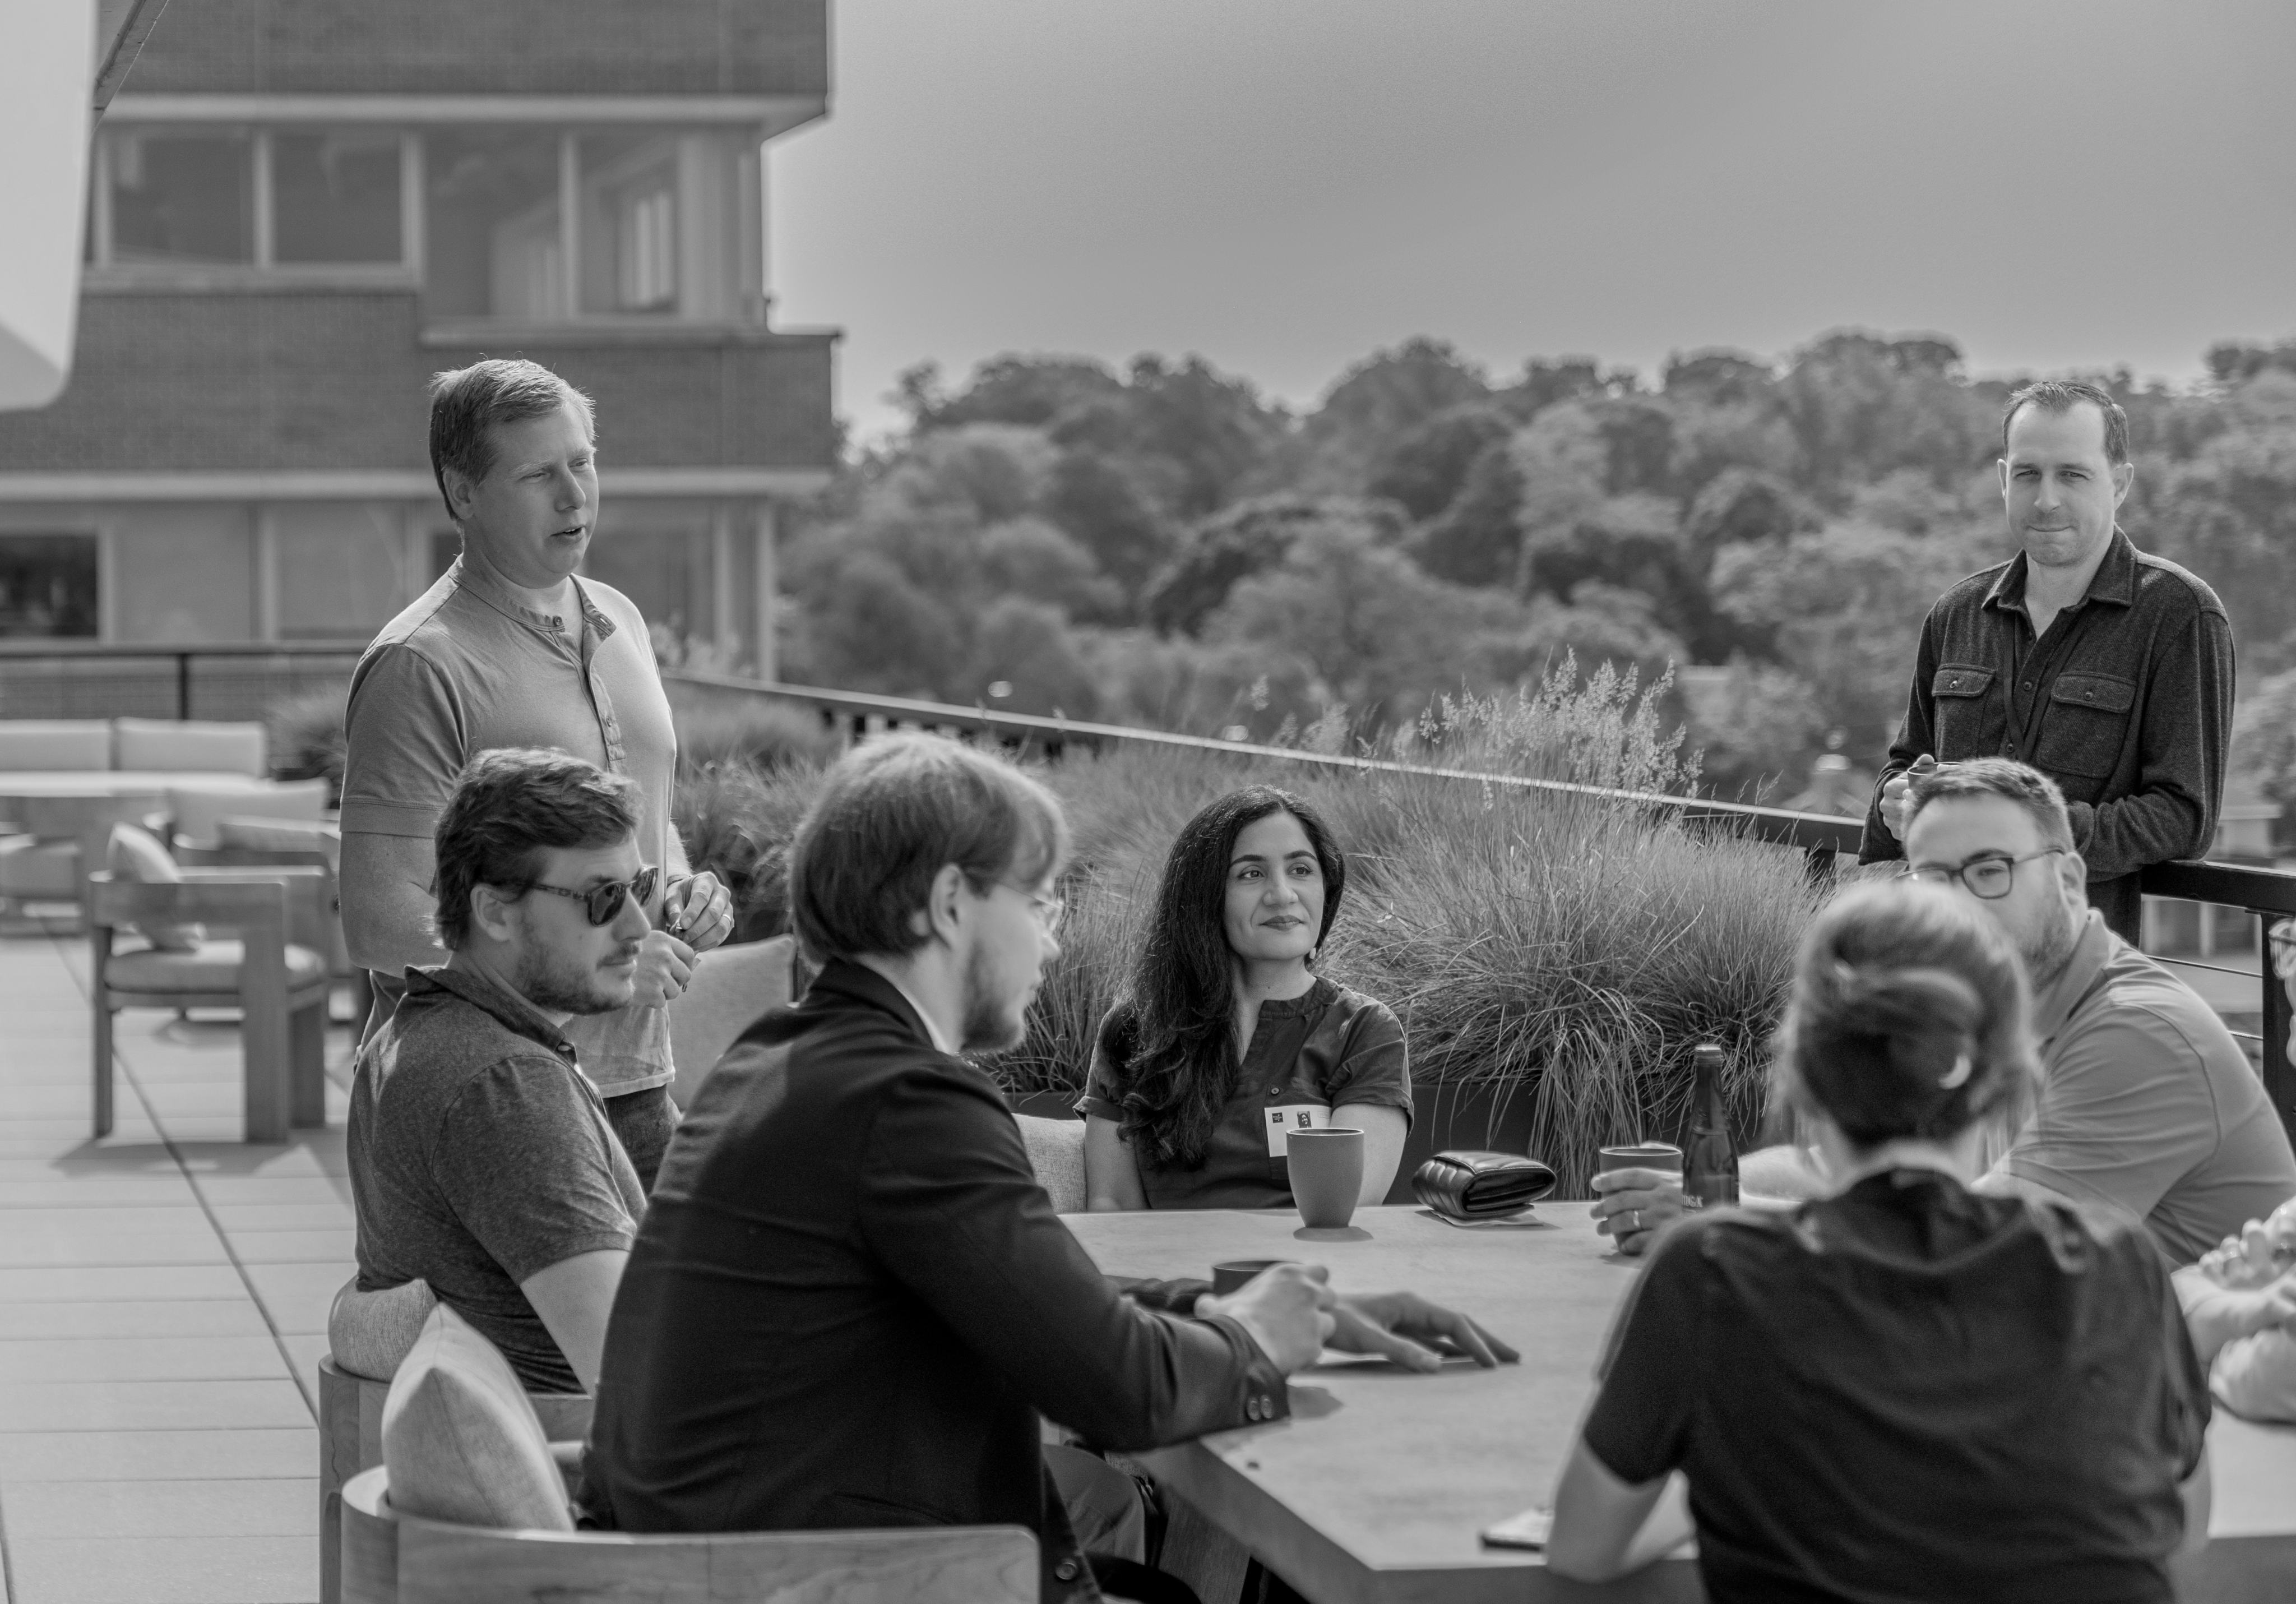
A photograph of the group at Yuma headquarters gives this chapter an ordinary scale. People sit around an outdoor table; Silbert stands to one side. A discussion about the ownership of intelligence eventually needs people who can ask questions across a table.
The scene also makes a useful connection to his beginnings. Market participation has always required more than interest. A young card dealer needed a display case. A student building on an unfamiliar network needs knowledge, support and somewhere to start.
The door is open. The work begins.
By September 2026, Yuma was reporting more than $200 million in TAO and subnet tokens staked to its validator. It said it had accelerated twenty subnets since launch, and had introduced a third investment vehicle, the Yuma Total Market Fund, in June.
Those figures describe the infrastructure gathering around Silbert’s bet. Staked assets are distinct from company revenue, and participation in a network does not settle the question of its commercial usefulness. The services still have to attract customers and do work those customers value.
That is where the latest chapter becomes interesting. Silbert has experience finding an asset before a conventional market has assembled around it. He also has experience of what happens when financial institutions fail the people relying on them.
Yuma brings both histories to a new field. Its practical test will be in functioning services, useful outputs and the trust earned by the institutions around them. Opening a door is a recognizable Silbert move. What people find on the other side will decide the story.
Yuma’s reported figures, September 14, 2026. Staked assets are not company revenue.