A bag of Haldiram’s snacks and an artificial intelligence chip make an unlikely pair. One belongs in a kitchen cupboard; the other helps power machines that generate language. Alpha Wave Global has invested in both businesses behind them. The interesting question is what an investment firm sees when it looks past such obvious differences.
Its answer appears to be durability: companies with an advantage that can survive expansion. In March 2025, Alpha Wave and IHC joined Haldiram’s equity round to support growth in the United States and Middle East. A year later, Alpha Wave appeared among the investors in Anthropic’s $30 billion Series G. The products differ. Both deals involve financing businesses with ambitions well beyond their existing markets.
- Equity buys a share of a company’s future growth.
- Private credit lends against a business, with repayment and security at the center.
- An insurance business in development would add long-term policyholder commitments.
The hedge fund that changed its name
Rick Gerson, Navroz Udwadia and Ryan Khoury founded the firm in 2012 as Falcon Edge Capital. Gerson had spent 15 years at Blue Ridge Capital. Udwadia came from Eton Park’s emerging markets team; Khoury had worked there on special situations and distressed credit. These were careers spent examining companies through different kinds of financial claims.
The name changed to Alpha Wave Global in November 2021. In a subsequent interview, Udwadia explained that the business had become predominantly a private-market investor, with some public-market investing. The new identity reflected an existing shift. Buying shares on an exchange was no longer the whole story.
In January 2022, Chimera Capital announced the second close of their jointly managed Alpha Wave Ventures II at $10 billion. Its remit covered fintech, AI, life sciences, consumer internet and business-to-business companies, primarily at the growth stage. That money was capital for a fund to invest. It was not revenue earned by Alpha Wave, or a price tag for the management company.
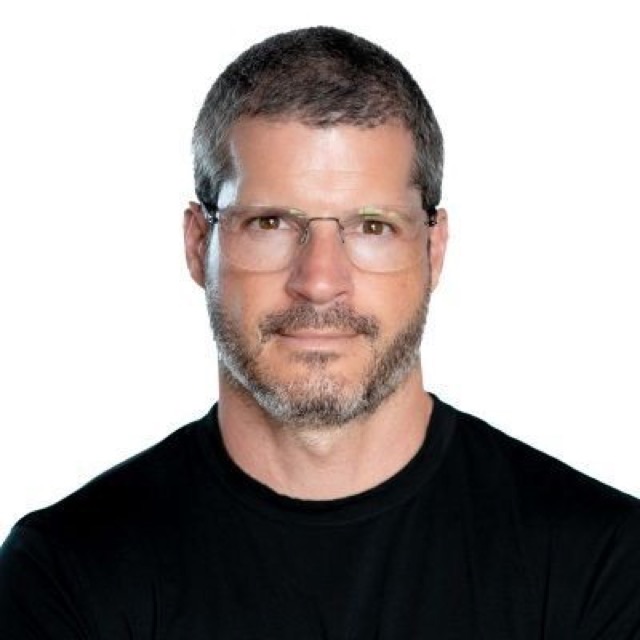 Rick Gerson
 Navroz Udwadia
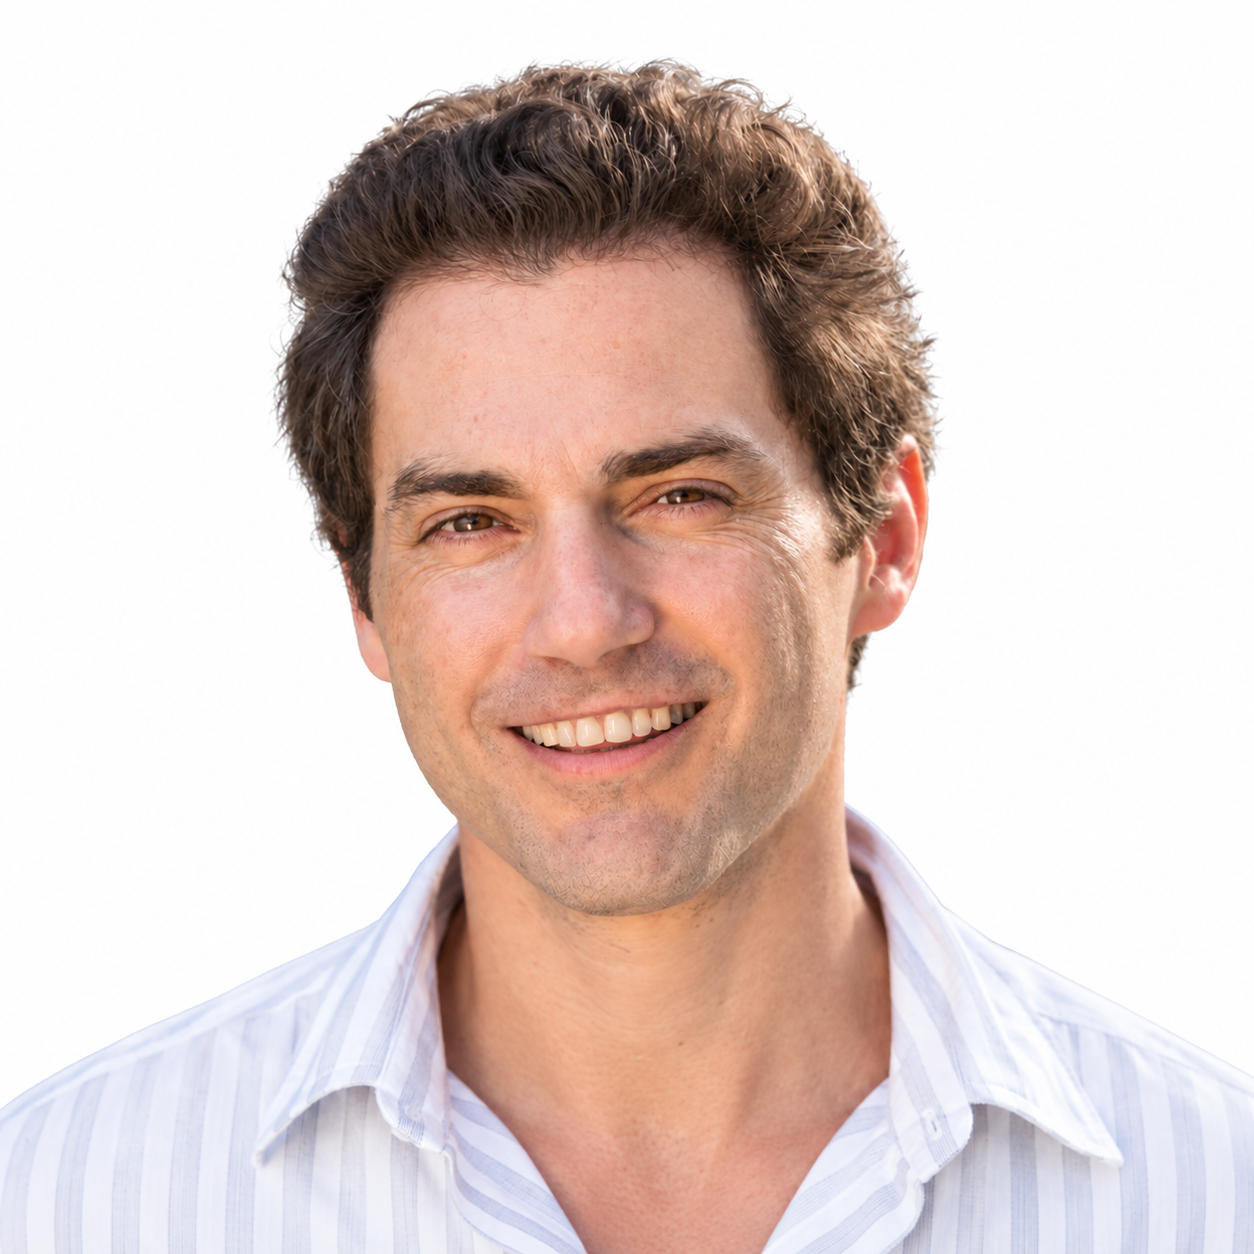 Ryan Khoury
Then the market clock sped up
The timing creates a revealing wrinkle. A huge pool of capital arrived just as the technology boom was losing its footing. By June 2022, Udwadia was describing a private-market correction that still had further to run. Public technology valuations had fallen first; private valuations, he said, typically followed four to six months later.
Alpha Wave had slowed deployment “early and hard,” he told The Economic Times. Rising inflation, higher crude prices, supply-chain disruption and a stronger dollar had complicated the investment environment. He emphasized patience and avoiding investments that required an imminent stock-market listing to produce a return.
“We don’t invest as pre-IPO arbitrages.”Navroz Udwadia · June 2022
There is something useful here for anyone allocating a much smaller budget. Money already raised does not have to become money immediately spent. The practical lesson is to separate the availability of capital from the quality of the next opportunity. A closed IPO window hurts much more when your original calculation depends on it opening.
Three ways to use a balance sheet
Today, Alpha Wave’s website presents three verticals: private equity, private credit, and insurance and retirement solutions. Public markets also appear in its March 2026 ownership announcement. The distinction matters: the current website’s organizing scheme is not a complete history of everything the firm has managed.
The credit operation solves a different problem from venture investing. A company might need financing to complete an acquisition, manage an ownership transition or expand faster than its bank is comfortable supporting. Alpha Wave describes local teams in the United States, Europe and Australia that can assess and structure those loans.
In November 2022, it launched an open-ended credit fund with Chimera and $2 billion of initial commitments. The stated objective was current income through private, senior secured, floating-rate loans. “Senior secured” describes priority and collateral; it does not remove the possibility of losses. A lender still needs a borrower capable of paying.
The management business earns fees for investing other people’s capital. Its regulatory disclosures list asset-based, fixed and performance-based compensation. The underlying clients include pooled investment vehicles and sovereign institutions. Founders and corporate borrowers receive the capital; investors in those vehicles pay for its management. These are distinct sides of the business.
Follow the money into the machinery
The AI exposure extends beyond software. In March 2026, Airtel announced a $1 billion investment round for its data-center subsidiary Nxtra. Alpha Wave’s proposed contribution was $435 million, alongside Carlyle, Anchorage Capital and Airtel. The transaction was subject to approvals. Data centers make a concrete companion to stakes in model developers: computation needs somewhere to live.
Life sciences supplies another dimension. In July 2026, Alpha Wave co-led AdvanCell’s $315 million Series D, supporting a clinical-stage radiopharmaceutical company. The financing was intended to advance development, isotope supply and manufacturing. It illustrates the firm’s willingness to fund infrastructure around a scientific product as well as the product itself. Clinical progress and commercial success remain separate hurdles.
The insurer is the next experiment
In March 2026, Judan Financial, an IHC subsidiary, announced an investment for a 50.1% stake in Alpha Wave. The existing founders would continue leading it. The announcement placed assets under management at approximately $29 billion and identified support for a new US life insurance and retirement business as a purpose of the investment.
Joe Norton, formerly chief operating officer of EquiTrust, was named to lead that insurance business. The plan calls for AI throughout underwriting, distribution and customer experience. Those are proposed capabilities, rather than evidence of a mature insurance franchise. The firm’s website still describes an insurance company being launched.
Alpha Wave sits between growth investors such as Coatue and the broader lending-and-insurance model associated with large alternative managers. Its combination is distinctive; each component has competitors. The test is whether expertise travels between them. Evaluating an AI company, underwriting corporate debt and meeting policyholder obligations demand different judgments.
For founders, the useful question is which kind of capital fits the business. For fund investors, it is whether they can tolerate the holding period and risks. A company with uncertain cash flows may struggle with debt; an investor needing quick withdrawals may struggle with private equity. The clocks matter before the cheque is written.