The boring detail was the business. When a lawyer accepts an advance fee, the money may still belong to the client. It must land in a trust account, not the firm's operating account. Processing charges cannot nibble at it. Chargebacks cannot casually raid it. A generic checkout screen sees $5,000. A legal payment system has to see who owns the $5,000, where it is allowed to sit, and which rules follow it there.
Amy Porter heard that problem while working with bar associations in 2005. Her answer became AffiniPay and, in 2007, LawPay. The product was not a grand reinvention of legal work. It was a payment flow careful enough for lawyers and simple enough that their clients could use a card. That restraint mattered. Professional firms are paid to reduce risk; they do not enjoy becoming test pilots for somebody else's disruption.
By 2024, AffiniPay said its platforms processed more than $20 billion. The company had also stopped being merely a processor. It owned legal practice-management software, immigration forms, personal-injury workflows, accounting payments, client financing, a business card and a growing set of AI tools. In August 2025, it admitted the obvious by changing the parent brand to 8am. AffiniPay had outgrown the name that described its original trick.
The wedge was compliance, not convenience
LawPay separates payments headed for trust accounts from money headed for operating accounts. Fees are drawn from the proper place. Firms can send payment links, schedule charges, accept cards or eChecks and reconcile transactions without inventing a spreadsheet ritual. The company wraps that machinery in PCI controls, encryption and tokenization, but its market advantage is more specific: it knows the professional rulebook.
This is why the obvious comparison with Stripe, Square or PayPal misses the point. Those products are built for broad merchant usefulness. LawPay is built for the uncomfortable exception. Its endorsements became part of the product: all 50 state bars, the American Bar Association and dozens of local and specialty bars made the unfamiliar processor feel institutionally safe. CPACharge followed a similar path through the AICPA and state CPA societies.
“Learn what lawyers actually need to be more efficient and successful.”Amy Porter, founder
Porter found the accounting opportunity by watching customers improvise. Accountants were, in her memorable description, “duct-taping” LawPay into CPA work. AffiniPay did not insist that one horizontal product could serve everybody. It launched CPACharge in 2016, keeping the payment engine while changing the language, workflows and distribution for accountants. That is vertical software in its least theatrical and most useful form: observe the workaround, then give it a proper name and a supported button.
The distribution choice was as important as the code. A bar association already had the attention of nearly every lawyer in its jurisdiction, along with something an ad campaign could not buy quickly: professional credibility. AffiniPay supplied a member benefit and the association supplied a trusted introduction. Direct API integrations, which began in 2014, made the product feel less like a new destination. A firm could keep its familiar practice software and insert LawPay at the moment money changed hands.
What changed the company's mind about staying in payments was evidence from its own customers. CPACharge came from accountants repurposing LawPay. ClientPay, acquired in 2021, showed demand from larger firms. The MyCase deal answered an even larger question: if billing and collection are inseparable in practice, why own only collection? AffiniPay followed repeated behavior rather than a tidy founding thesis. Each expansion shortened the distance between work performed, invoice sent and cash received.
How the wedge widened
Then the checkout button bought the office
The largest strategic move came in 2022, when AffiniPay acquired MyCase from funds advised by Apax. MyCase is where a law firm opens matters, stores documents, messages clients, tracks time and sends bills. Its family included CasePeer for personal-injury practices and DocketWise for immigration work. The deal moved AffiniPay from the last step of the client journey - getting paid - into the system where most of the journey happens.
The logic is powerful. Practice software produces the bill. Payments close it. Once both sit in one stack, AffiniPay can automate reconciliation, see where cash gets stuck and offer financial products at the moment of need. Pay Later, powered by Affirm, lets eligible clients finance legal fees while the firm gets paid upfront. It passed $250 million in loan volume in 2024. MyCase Smart Spend adds a LawPay Visa Business Card to the other side of the ledger, helping firms manage expenses inside their practice software.
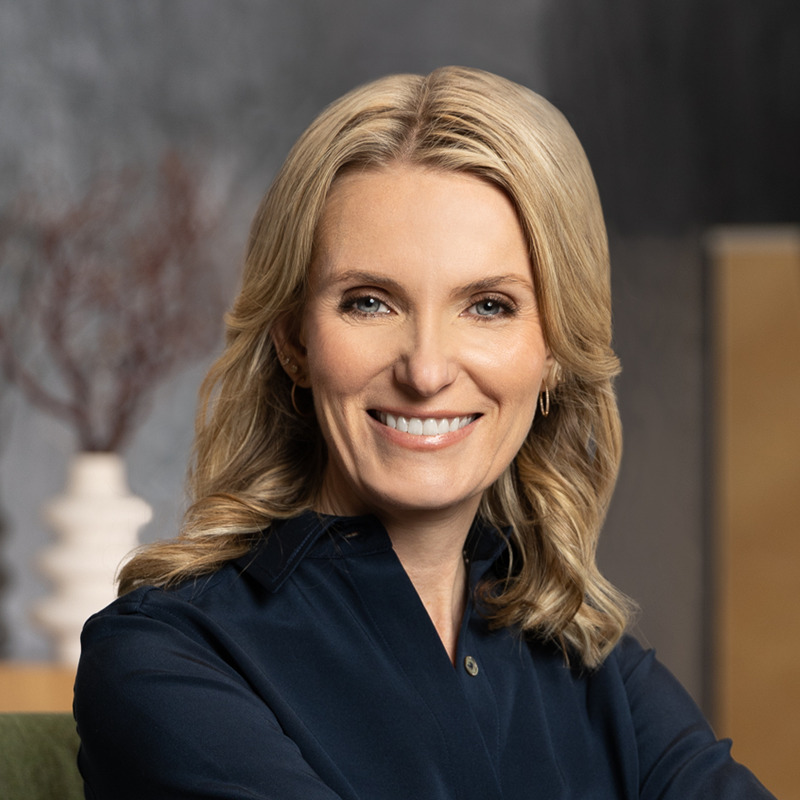
Dru Armstrong, a lawyer and former consumer-tech executive, became chief executive in 2021. Under her, acquisition and product development accelerated. Genstar Capital made a significant investment alongside TA Associates in 2024; the amount was not disclosed, although deal reporting put enterprise value close to $3 billion including debt. AffiniPay said annual recurring revenue grew 30 percent that year. The combined company had already reported more than $200 million in annual run-rate revenue when the MyCase deal was announced.
What it costs - and where the bet gets expensive
LawPay's public entry price is $19 per firm each month. Processing is the larger bill: 2.99 percent plus 30 cents for Visa, Mastercard and Discover; 3.90 percent plus 30 cents for American Express; 1 percent for eCheck; and 5.95 percent for Pay Later. Card-network pass-through charges may apply. MyCase and the rest of the suite use their own subscriptions and tiers.
That price structure reveals the business model. Subscription revenue pays for access to the workflow. Transaction revenue scales with the customer's success at collecting money. Lending and cards create additional economics. The software is not simply a lead generator for payments, nor are payments merely a feature. Each makes the other harder to remove.
For customers, the practical payoff is less glamorous than the platform diagram and easier to measure. A client can pay from a phone instead of finding a checkbook. A receptionist can see whether an invoice cleared without calling the bookkeeper. A trust payment arrives in the trust account while the processor's fee lands elsewhere. An immigration team can pull client data into forms; a personal-injury firm can connect a settlement to its matter. The minutes saved are small, repetitive and attached to cash. That combination tends to survive budget reviews.
Where AffiniPay earns its keep
The first thing to fail is often not the core payment rail. It is the seam between products: an integration changes, a matter does not reconcile, a support case sits too long, or a firm pays for overlapping systems. Clio, AffiniPay's clearest legal rival, now promotes its own embedded payments and criticizes LawPay's separate fees and workflow handoffs. Generic processors compete on price and familiarity. PracticePanther, Smokeball, Filevine, CosmoLex and others compete on the daily software experience.
AffiniPay therefore works best when the regulated workflow is valuable enough to justify the premium. A solo lawyer handling retainers, a personal-injury shop coordinating settlements or an accounting firm collecting during tax season can see the fit. A graphic designer who just wants to send three invoices a month may not. Nor will the playbook travel cleanly to a market without trusted associations, complicated money rules or a fragmented software stack. Specialization is the moat and the boundary.
Why the name finally changed
The 8am rebrand was an act of bookkeeping. “AffiniPay” sounded like a payment company assembled around affinity partnerships. By 2025, customers could run matters, create invoices, accept money, finance fees, summarize documents and manage spend across seven product lines. The parent name no longer balanced with the assets.
The change did not merge the products or rewrite customer contracts. Accounts, pricing, support and core functionality stayed in place while LawPay became 8am LawPay, MyCase became 8am MyCase and the other brands followed. The promise is a connected professional-business platform. The risk is that a neat brand architecture gets mistaken for a neat technical architecture. Customers will judge the rebrand by whether data, money and tasks actually travel more easily between the products.
The part worth copying
- Find the rule a horizontal product treats as an edge case.
- Learn it well enough that the profession's gatekeepers will endorse you.
- Integrate with the incumbent workflow before asking customers to replace it.
- Watch for “duct tape” behavior - it is unpaid product research.
- Expand from the transaction into the system of record only after earning trust.
AffiniPay's story is easy to flatten into private-equity consolidation: Great Hill in 2016, TA in 2020, MyCase in 2022, Genstar in 2024. The more useful reading is operational. The company found a moment where compliance, cash flow and client experience collided. It made that moment boring. Then it followed the money backward through the firm.
That journey now includes AI. AffiniPay IQ began with document summaries and text editing, with plans for search, drafting, task creation and data extraction. The cautious version of this future is plausible: AI removes clerical minutes inside a trusted workflow. The incautious version collides with confidentiality, accuracy and professional responsibility. Once again, the company will win or lose on its handling of the fussy detail.