Avi Lele wanted to give the children in his family something they might still value after the wrapping paper had disappeared. Stock seemed promising. Buying it as a present proved considerably less festive. The account setup, personal information and cost of whole shares turned a generous thought into an administrative project. Stockpile began with that problem: how could owning a piece of a company feel as familiar as receiving a gift card?
- Stockpile paired fractional shares with physical and digital stock gift cards.
- Its family accounts let children request trades for an adult to approve.
- A historical $4.95 monthly membership made small-account economics worth examining.
- Financial services wound down in 2026; eligible kids’ accounts moved to Stash.
That last point changes how the company should be read today. This is the history of an investing service, rather than an invitation to open a new Stockpile account. The interesting question is what it discovered about getting people started - and what getting started could not settle.
A present with paperwork
Founded in 2010 by Lele and Sanjeev Kulkarni, Stockpile approached the stock market through the gift shop. Lele had been a patent attorney; Kulkarni was a Princeton professor who, by the time of the retail launch, was dean of its graduate school. Their proposed shortcut was a small card carrying an unusually large idea: the recipient could become an owner of a familiar business.
In 2015, physical cards came in $25, $50 and $100 denominations. A buyer did not need to purchase a whole expensive share. Fractional ownership allowed a fixed dollar gift to become a smaller slice. Recipients could also choose a different stock from the one on the card. Auntie’s taste in companies need not become a binding family tradition.
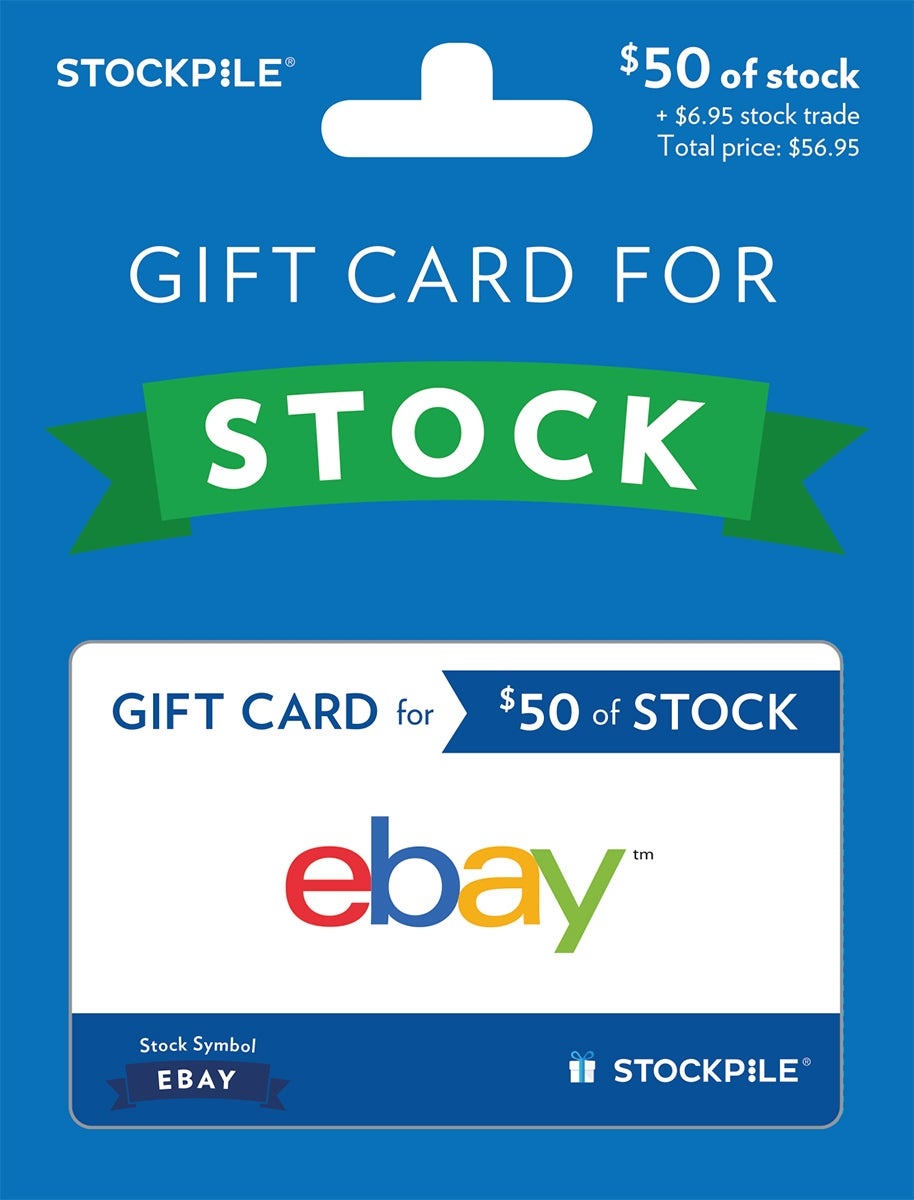
The distinction mattered. A gift card was not already a share. The recipient still had to redeem it, supply identifying information and complete the investment process. Stockpile had made the invitation friendlier. It had not abolished the responsibilities of a brokerage account.
The rack was part of the product
The company’s 2015 funding announcement described cards available in selected supermarkets and retail chains. Blackhawk Network supplied a distribution relationship; contemporary reporting identified stores including Kmart and Safeway. Stockpile was placing an unfamiliar purchase in a setting where shoppers already knew what to do.
This was a useful piece of product thinking. The obstacle was partly financial, but it was also a matter of context. A brokerage website asks someone to identify as an investor. A gift-card rack asks someone to identify as a person with a birthday coming up. The second role is considerably less intimidating.
Investors backed the experiment. Stockpile announced a $15 million Series A in October 2015, with Mayfield, Sequoia and Ashton Kutcher among its investors. A $30 million Series B followed in September 2017, led by Eight Roads Ventures. At that point, the company put total funding above $45 million and reported that two-thirds of customers were under 35.
The app also supported stocks, exchange-traded funds, automatic investment plans and short lessons. A customer could arrive because of a present and stay to make regular investments. That transition, from occasion to habit, was where the longer business relationship would have to develop.
The child requests. The adult approves.
Under Victor Wang, who became CEO in 2019, the family became more explicit in Stockpile’s identity. Its custodial design gave children a role in choosing investments while an adult retained approval. A child could propose a transaction; the parent had to authorize it. The account belonged to the child, with the adult acting as custodian.
Consider the conversation that design could produce. A child recognizes a brand and wants to own it. A parent can ask why, what the business does and what might happen if its price falls. This is a possible use of the workflow, rather than evidence that every family used it well. Still, the pause before approval gave the product an educational purpose beyond displaying a balance.
“We’re at the kid’s table!”
Victor Wang, quoted by Stockpile on LinkedIn, April 2024
The positioning also explains why a comparison based only on trade commissions misses something. Stockpile was selling participation and supervision alongside access. An adult simply seeking a brokerage had alternatives such as Robinhood. A parent seeking an investing conversation was being offered a more particular experience.
Small accounts, fixed bills
The early service advertised stock trades at 99 cents. By 2022, contemporary reporting documented a move to membership pricing. In 2024, a $4.95 monthly tier included one adult brokerage account and up to five custodial accounts, while stock trading was commission-free. The business was charging for an ongoing family relationship.
A monthly fee, however, has an awkward relationship with a small balance. Twelve payments of $4.95 total $59.40. Against a hypothetical $100 balance, that is 59.4% of the starting amount; against $1,000, 5.94%; against $5,000, about 1.19%. These are simple comparisons, not investment-return calculations. They exclude changes in value, deposits and other charges, and the membership could cover several accounts.
$59.40 a year, three different proportions
The calculation makes the trade-off visible. A household using several accounts and the learning experience might judge the subscription differently from someone who received one modest gift and rarely returned. The easier it becomes to start with very little, the more closely a fixed bill deserves attention.
There were product limits, too. A 2024 review described stock trades executing at end-of-day prices rather than in real time, and no mutual-fund trading. That suited a different rhythm from active trading. An accessible first step was not an all-purpose investing desk.
A bigger family toolbox
Stockpile kept widening the occasions it could serve. In December 2020 it introduced Stockpile-by-Text: personalized animated gift cards that buyers could send through messaging services by copying a link. The old gift-card idea had moved from the checkout rack into a conversation on a phone.
In October 2023, Green Dot and Stockpile announced a partnership intended to add debit cards for minors with parental spending controls. An October 2024 announcement then unveiled a family-banking offering and a tuition-discount rewards program through SAGE Scholars, with app rollout expected to begin in January 2025. Family Plus was advertised at $7.95 a month or $69.95 a year. The tuition rewards were conditional discounts at participating colleges, rather than cash to spend at any university.
A February 2024 announcement added another direction: Stockpile acquired the talent, technology and intellectual property of Investables, an alternative-investing platform focused on high-end collectibles. The acquisition brought expertise and infrastructure into the business, extending the company’s ambitions beyond stocks. Between spending tools, education and alternative assets, the original gift-card broker was becoming a broader family-finance proposition.
The accounts outlive the app
On March 19, 2026, Stockpile announced the end of its financial-services journey. Its farewell message named Public, Stash and Apex as destinations for account transitions on April 17. The brief line “Starting was everything” was a fitting epitaph for a company organized around first investments.
The transition details were more concrete. Stockpile’s FAQ directed adult brokerage accounts to Public and kids’ brokerage accounts to Stash. It specified exceptions for crypto positions, including liquidation of crypto held in children’s portfolios. By July, Stash’s updated FAQ confirmed that eligible custodial accounts had transferred and remained custodial accounts.
Stockpile’s farewell also named Apex. Individual notices govern the destination and handling of each account.
For former customers, the useful next step is the successor platform’s account-access guidance and the notices sent about their own holdings. The software’s disappearance and the account’s destination are separate questions. Stockpile’s current main website presents a gift-card refund request form, a much narrower task than introducing a family to the market.
Copy the invitation. Check the arithmetic.
Stockpile’s most portable idea is to borrow a familiar action when introducing an unfamiliar one. A gift, a recognizable company and a small dollar amount can give someone a reason to begin. Its family workflow suggests a second lesson: an approval step can create space for discussion, provided the adult uses it.
The idea depends on what follows. A familiar brand is a starting point for curiosity, not a complete investment argument. A parent who never discusses the trade leaves much of the educational promise unused. A household with a tiny balance feels a fixed fee more sharply. Stockpile found an inventive way to invite people into ownership. Its history makes the continuing relationship just as interesting as the invitation.