At 22, Simon Lobanov was a bankcard representative in Brooklyn. The job put him near an everyday exchange: a customer paid, a merchant accepted the payment, and a business carried on. Then a friend pointed out another possibility. The same stream of receipts could help a business obtain financing. Lobanov studied the market and entered cash-advance brokerage. A sale, it turned out, could have a second life.
That beginning is a useful way into his career. It has the scale of a conversation rather than a grand unveiling. Someone describes a problem. Someone else sees a business in it. The interesting object is the receipt, a scrap of evidence that money has changed hands and that more money might arrive tomorrow.
Today, Lobanov is president and CEO of B2B Puerto Rico. Payments, financing and investment sit within the company’s activities. His work has moved through different organizations and places, but that early connection remains a helpful thread: the transaction at the counter and the financial life of the business behind it.
A friend notices the money between sales
The early opportunity involved financing that banks were not providing to some businesses. Merchants could receive money from alternative funders, with repayment tied to a portion of credit-card receipts. Lobanov’s entry was as a broker. He stood between the business seeking funds and the organization able to supply them.
By 2014, he described experience with both lending and brokerage, as well as retail operations and wholesale sales channels. He also noted a change in the industry: using bank-account withdrawals for repayment could reach businesses that did not accept cards. The customer base could change when the route of repayment changed.
There is a neat piece of business logic here. The means of collecting money influences whom a financing company can serve. A technical detail can open a door. For someone working with merchants, the detail is part of the business model, down to the last deposit.
Sixteen thousand square feet of practical ambition
In December 2013, Red Payments renewed its office lease at 132 West 36th Street in Midtown Manhattan. Lobanov was its chief executive. The merchant-services firm occupied 16,213 square feet on the third floor, and the renewal extended the arrangement for seven years.
His explanation emphasized recruitment. Central positioning in Midtown, he said, helped the company attract talent for its North American operations. The landlord pointed to nearby transportation, including Penn Station and Port Authority. Growth had acquired a decidedly practical address.
Seven-year lease renewal, December 2013
The seven-year term adds another detail: a commitment to a place. It suggests an organization planning its work over a period longer than the next sales cycle. The public explanation was straightforward, focused on staffing and location. There is no need to improve it with a larger drama. A team needs somewhere to assemble, and a leader has to choose where.
An office lease rarely gets the starring role in an executive’s story. It deserves a small speaking part here. A business that sells services still needs people who can reach their desks, answer questions and get work done. The romance of finance occasionally requires a sensible commute.
Lobanov’s choice also shows the difference between a market and an operation. A market can be described in broad geographic terms. An operation needs a particular floor in a particular building. Someone must negotiate the space, hire the team and decide whether the company will still want to be there years later.
The trouble with a new way to pay
The following year, Lobanov appeared in trade coverage of changing payment technology. One subject was the American transition to EMV chip cards. He pointed to Canada’s lengthy changeover and expected the United States to face a difficult, extended process.
“It’s going to be a painful and longer process”
Simon Lobanov on the U.S. chip-card transition, 2014
Keep the date attached to that comment. It belongs to the industry conversation of 2014, when chip cards and mobile payments were raising questions about how merchants would accept purchases. It offers a glimpse of an executive thinking about adoption rather than simply admiring a new device.
A payment method has to pass an unusually domestic test. Can the person behind the counter use it while serving the next customer? A technology presentation can proceed at its own pace. A queue has considerably less patience.
That is the practical tension running through merchant services. The transaction must be intelligible to the customer, workable for the business and supported by the systems behind it. Lobanov’s historical comments fit that setting. Change brings work along with possibility, and the people doing the work are often several steps away from the announcement.
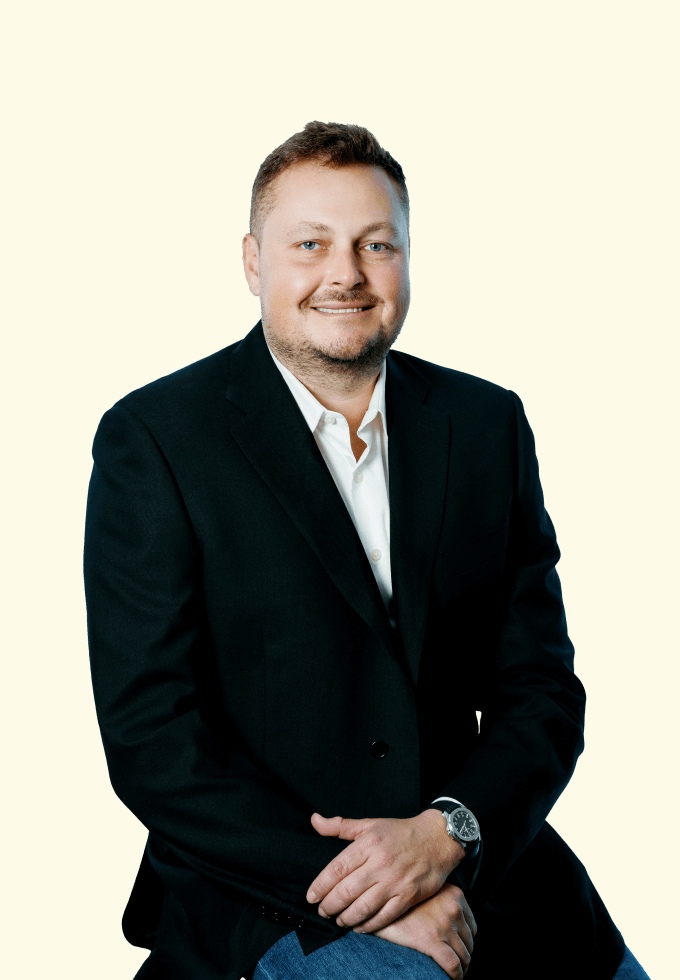
A business takes root in Puerto Rico
Lobanov studied at Binghamton University between 2000 and 2002; his education listing identifies computer science. His later professional record includes sales leadership, CPS Merchant Services and Red Payments. By 2017, he was president and CEO of B2B Funding Puerto Rico. His B2B Puerto Rico role is listed from January 2023.
B2B dates its Puerto Rican origin story to 2017, describing a visit by New York fintech executives that led to the creation of its funding business. The local slogan, “Aquí para los de aquí,” places the emphasis on serving people on the island. Funding came first; merchant payments followed.
The sequence gives the business a recognizable shape. An owner who needs capital also needs to collect revenue. Those needs occur at different times, yet they can belong to the same establishment. Expansion from financing into payments follows the working life of that customer.
Lobanov now leads an organization with named responsibilities for operations, finance, legal matters, technology, underwriting and merchant services. Leadership here includes coordinating several kinds of work. The counter is one point of contact; the organization behind it has many moving parts.
Service areas at B2B Puerto Rico. Each addresses a different business need.
Tomorrow’s receipts, today’s decisions
B2B Funding describes its advance as a purchase of future bank deposits at a discount. It says approval amounts use recent account statements and business information. Repayment involves fixed weekday withdrawals from the business bank account. The mechanics remain close to the flow of merchant revenue.
Its published process offers an online application, same-day review and funding within 48 hours. Those are the company’s advertised timings. The actual transaction depends on approval and an agreement; a quick application does not itself put money in the account.
For a merchant, speed is one part of the decision. Amount, terms and the pattern of repayment also belong in the picture. The business receives funds now and takes on an arrangement that reaches into future receipts. Both sides of that calendar matter.
This is the territory Lobanov entered through his friend’s suggestion in Brooklyn. The instruments and organizations have evolved. The underlying exchange remains easy to describe: money available today is connected to money the business expects to receive later. Making that exchange function is the professional work.
The support ticket belongs in the story
B2B Merchants lists card processing, payment equipment and a merchant-support application. The app’s features include tracking trouble tickets, equipment information and daily batch updates. It also offers a QR program through which merchants can display and update specials.
These features supply a more concrete picture than the word fintech alone. There is a piece of equipment to understand. There is a payment batch to check. There may be a menu or promotion to change before the next customer arrives. A service company earns its place through repeated small encounters.
Field-service recruitment describes on-site installation, configuration and troubleshooting of merchant devices. That work brings the business into the customer’s premises. A diagram of a payments system ought to leave room for the person arriving to solve a problem.
Lobanov’s professional relationships also reach into the less visible work behind transactions. In a public LinkedIn comment, he thanked a payments lawyer for help with agreements and complex situations. He singled out knowledge and precision. Legal advice, like technical support, can matter most when an arrangement must actually work.
The second life of a sale
The appeal of Lobanov’s story is its continuity. A young bankcard representative learned that receipts could be useful beyond recording a purchase. He moved into financing, led a payments business in New York and now leads B2B Puerto Rico. The customer’s sale remains close to the center.
It is possible to describe all of this in the vocabulary of platforms and financial infrastructure. The shop counter offers a better view. On one side, a customer pays for something. On the other, an owner makes plans for stock, equipment, wages or the next stage of the business.
A receipt records a completed moment. For the merchant, the working day continues. Lobanov’s career has developed in that space, where money just received and money still needed become part of the same conversation. The small slip of paper has quite a lot to answer for.
Follow the receipt
Continue with these public profiles, company pages and historical articles.