A mortgage closing is a ceremony built on suspense. There are signatures, initials, a date circled on several calendars and, at the end, a set of keys waiting to become symbolic. Somewhere behind that tidy scene is the less cinematic business of making certain the money is actually there. Sherri V. Small has spent much of her working life in that territory - the disciplined, deadline-shaped stretch where a loan stops being an intention and becomes a funded fact.
Small is a mortgage loan funder with PrimeLending in Maryland. Her public professional record traces her work with the company back to 2009 and describes more than 20 years in mortgage lending overall. The title is short. The responsibility it points to is not. A funder operates near the conclusion of a long relay, after financial records have been gathered, a property assessed, a title searched and an underwriting decision made. Every earlier handoff has to arrive intact.
It is an occupation for people who understand that “almost complete” has a dangerous second word. A closing date has little interest in how nearly ready a file may be. The numbers must reconcile, the documents must satisfy the conditions, and the proceeds must reach the proper place at the proper time. Homebuyers may spend years imagining a front door. The funder works in the final hours before it opens.
The quiet mechanics of arrival
PrimeLending describes its mortgage process in five broad stages: gather the borrower's financial information; confirm the property through appraisal, title work and inspection; send the file through underwriting; close the loan; then let the new owner settle in. Funding lives close to the hinge between stages four and five. It is the point at which reassuring verbs such as approve and schedule must yield to the most concrete verb of all: disburse.
A home loan's route to the front door
The company gives borrowers digital tools for applications, document uploads and status tracking. It can make a process with hundreds of individual data points look agreeably simple on a phone. Yet software does not abolish responsibility. It reorganizes it. Behind each clean progress marker are people checking what arrived, noticing what did not, and keeping one missing item from becoming tomorrow's unpleasant surprise.
Small's place in that system is particularly revealing because funders are rarely the public face of a mortgage company. Loan officers appear on branch pages and speak with borrowers. Funders are more like stage managers: essential to the cue, largely absent from the curtain call. If their work is excellent, the buyer experiences something delightfully uneventful. Competence has the odd reward of making itself disappear.
The keys are the photograph. Funding is the clockwork just outside the frame.The last mile of a mortgage
Small works with PrimeLending's operation in the Baltimore area. The branch is in Timonium, north of the city, serving buyers, refinancers and homeowners financing renovations. Her own public listing places her in Owings Mills. These are communities where a national lender becomes a local chain of calls, calendars and closing tables. The institution may lend across the country; the file in front of an operator still belongs to one household, on one deadline, buying one address.
Federal rules and company procedure give that deadline a formal choreography. PrimeLending tells borrowers to expect their closing disclosure at least three days before closing, with the loan terms, fees and cash required to complete the purchase. By then, abstraction is over. A decimal affects a household budget. A misspelled name can demand attention. A delayed transfer can change the mood in a room where a buyer has already packed the moving truck. Funding is financial work, certainly, but it is also an encounter with other people's logistics.
That closeness to consequence explains why the back office deserves more curiosity than it usually receives. Sales can be celebrated in totals; operations is better understood through avoided failures. The useful questions are plain. Did the right amount arrive? Did it arrive securely? Did it arrive when the transaction required it? Repeated across years, those yeses form a body of work, even if no borrower thinks to ask who made them possible.
II · A second kind of closingWhen college ties become public work
Small's other recorded role begins with a different kind of threshold. She is a founding member and secretary of the Charlize Angel LaTonya Gilliam Scholarship Foundation, established in 2020 by Charlize's mother and six of her mother's sorority sisters. Its purpose is direct: help students who lack sufficient financial means begin or continue education after high school.
The foundation was created in Charlize's memory, and its board is built from relationships that long predate the organization. Small earned a Bachelor of Science in Business Administration from Towson State University. While there, she was initiated into Delta Sigma Theta Sorority through the Mu Mu Chapter. She later became a charter member of the Baltimore Metropolitan Alumnae Chapter. The foundation gathered women from that collegiate and sororal circle and gave their shared commitment an address, a board and a job to do.
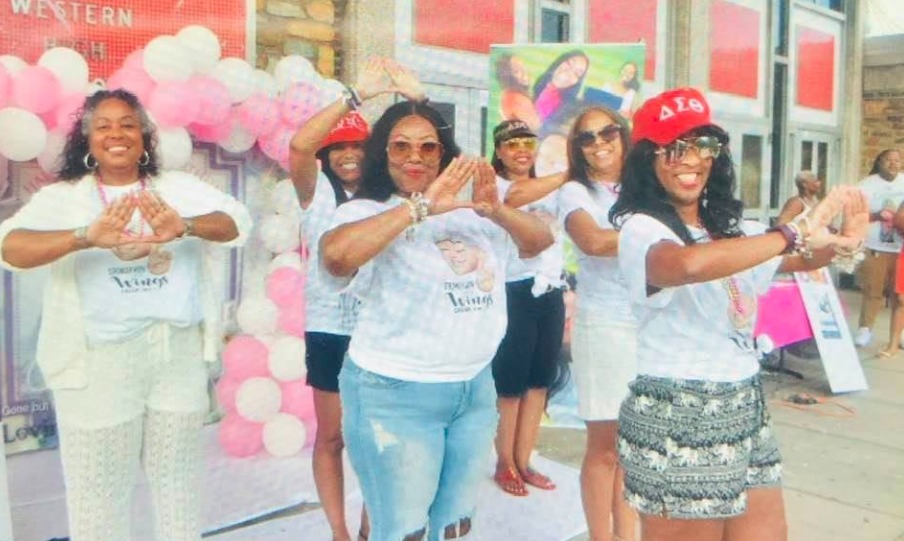
Secretary is another unshowy title with structural importance. The work of a young nonprofit depends on records, meetings, continuity and institutional memory. Inspiration can fill a room; governance is what remembers what the room agreed to do. Small's business education and long operational career do not prove how she performs every foundation task, but they make the pairing intelligible. Her public roles both occupy the distance between a good intention and a completed obligation.
The foundation's origin also says something about the endurance of networks formed in college. Small's Towson connection did not remain a line on a résumé. Through Delta Sigma Theta, it became part of a civic relationship that lasted long enough to answer grief with organization. The founders did not merely assemble around memory; they chose the administrative burden of preserving it. They gave themselves titles, divided responsibilities and stated a testable purpose: support students whose finances might otherwise interrupt further study.
There is a temptation to make the parallel too neat. A mortgage is not a scholarship, and a corporate position is not volunteer governance. Yet both are forms of access administered through details. Money must be accounted for. Eligibility must be established. Decisions must be documented. The beneficiary eventually receives something wonderfully larger than the process: a home, an education, a different set of possibilities.
That is where Small's biography becomes more than a list of affiliations. Her career and service sit on either side of the same sturdy idea. Opportunity is not self-executing. It requires people who will tend the mechanism after the announcement, answer the practical questions and remain present through completion.
III · The virtue of the unremarkable dayA career measured in things going right
Mortgage lending changed considerably across Small's two decades in the field. Paper-heavy processes acquired secure portals. Status calls became digital notifications. Borrowers learned to photograph documents with a phone. PrimeLending's own process now emphasizes online applications and a tracker that lets customers follow a file and send messages. The surface became faster and more visible. The underlying bargain remained the same: the borrower supplies a truthful financial picture, the lender evaluates it, and a team carries an approved transaction safely to closing.
Long tenure matters in work like this because experience accumulates not only as knowledge but as pattern recognition. A veteran operator has seen the ordinary routes and the awkward detours. She knows that urgency does not improve arithmetic and that calm is useful when several people are watching a clock. None of this needs a brass band. Indeed, the ideal funded loan is almost boring. The wire arrives. The papers hold. The keys change hands. Everyone goes home - including, rather importantly, the buyer.
Some people make the promise. Operators make the promise keep its appointment.On precision as public service
The same modest standard suits community work. A scholarship foundation does not need to resemble a grand institution to alter a student's semester. It needs to endure, select responsibly and put support where the mission says it should go. Small and her fellow founders built their organization around a particular life and a practical ambition. Its scale is human. That is not a limitation; it is the point.
Small's public footprint is spare. It contains no personal manifesto and no parade of self-descriptions. What it does show is consistency: business training, decades in lending, sustained sorority ties and a founding role in an education nonprofit. The portrait that emerges is not of a celebrity executive. It is of an operator whose working vocabulary is made of completion.
At the closing table, the visible story is beginning. In the funding office, another story has just been finished. Small has built a career at that junction. Then, away from the loan file, she has helped create another route forward for students. Two thresholds, two kinds of paperwork, one durable preference for making sure that a promise reaches the person it was meant to serve.