A platform fee can look harmless until you put a pound sign beside it. Imagine two people buying the same fund, reading the same research and using the same website. One has £10,000 invested; the other has £100,000. On a percentage tariff, the second person can pay ten times as much for essentially the same access. interactive investor has spent years making that discrepancy its business.
- The proposition: a monthly subscription for investment and pension accounts.
- The engine: acquisitions and shared infrastructure spread the cost of serving customers.
- The catch: flat fees favour some balances and habits much more than others.
The company, usually called ii, is a British investment platform. Customers can buy shares, funds, investment trusts, ETFs and bonds, manage pension savings and build an ISA portfolio. But its most distinctive product may be the way it presents the bill. Pounds per month are easier to picture than fractions of wealth. They also make an unusually pointed argument about what an investment platform actually does.
First, the information was wrong
Sherry Coutu’s starting irritation was wonderfully ordinary: she was trying to buy a house. In an oral history, she recalls finding mortgage information on outdated pieces of paper. She started interactive investor in 1995, initially covering mutual funds before expanding into other financial services.
Hiring lagged demand, and Coutu came close to running out of cash during expansion. The lesson she describes is less glamorous than finding a market: watch the money even when customers keep arriving. Growth can consume the resources that make growth possible.
She floated the company in 2000. Fluctuating share prices later persuaded her to judge businesses by customers and revenue rather than valuation. That distinction fits ii rather neatly. An investment business can spend its days watching prices while its own survival depends on the prosaic work of serving people.
A flat fee needs a very big room
The later company’s answer to that operating problem was scale. J.C. Flowers backed ii’s acquisition plans in 2017. The completed TD Direct Investing purchase brought the combined business to £21 billion in assets under administration and more than 300,000 customer relationships. Alliance Trust Savings followed in 2019, The Share Centre in 2020 and the EQi customer book in 2021.
These deals carried an industrial logic. A brokerage needs technology, security, administration and people who can solve problems when a transfer stalls. A larger customer base can spread those costs. Writing in 2020, chief executive Richard Wilson put it plainly: Scale enables us to keep costs low while continuously investing in technology
.
A subscription is a promise about the bill. Scale is the work behind that promise.
There were decisions about what to leave behind, too. After buying Alliance Trust Savings, ii agreed to sell its advised and partnership businesses to Embark, reinforcing its focus on customers investing directly. In May 2022, ii itself joined abrdn, now Aberdeen, following an announced £1.49 billion deal. That figure bought ownership of a business; it was not cash raised for customers to invest.
The same bill, a different bite
The pricing change that took effect in February 2026 made the bundle explicit. Core costs £5.99 a month for portfolios up to £100,000. Plus costs £14.99; Premium costs £39.99. Each includes access to an ISA, SIPP and trading account. The attraction is especially clear for someone bringing several accounts together.
What does the platform fee eat?
Illustration uses Core through £100,000 and Plus above it. Platform subscription only; excludes dealing, FX, fund costs and optional services. Rates checked 16 October 2026.
But the arithmetic has teeth. Core’s £71.88 annual charge is about 7.19% of a £1,000 balance and 0.072% of £100,000. Go above the Core ceiling and the subscription changes. Add dealing, currency conversion and underlying fund costs and the total bill changes again. A fixed platform fee is not a promise of free investing.
Nor did the new bundle reduce everyone’s subscription. ii’s announcement acknowledged that some customers holding only an ISA or trading account would pay more, while combinations including a pension could cost less. This is useful candour. The relevant comparison is your own set of accounts and transactions, expressed in pounds over a year.
Choose your degree of control
For people who enjoy choosing investments, ii supplies research, journalism, guides and portfolio tools. Its investment-trust offering places it in the established UK brokerage market alongside alternatives such as Hargreaves Lansdown and AJ Bell. Its range also reaches beyond the simple fund menus that some savers prefer. Choice is useful only if you want the work that accompanies it.
The Managed ISA, launched in 2024, offers another route. Customers are matched to portfolios across two styles and five risk levels. Aberdeen advises on allocation and fund selection; the underlying investments carry their own costs. A SIPP serves retirement savers, while Junior ISAs on eligible plans extend the proposition to families. These are different ways of using the platform, with different responsibilities attached.
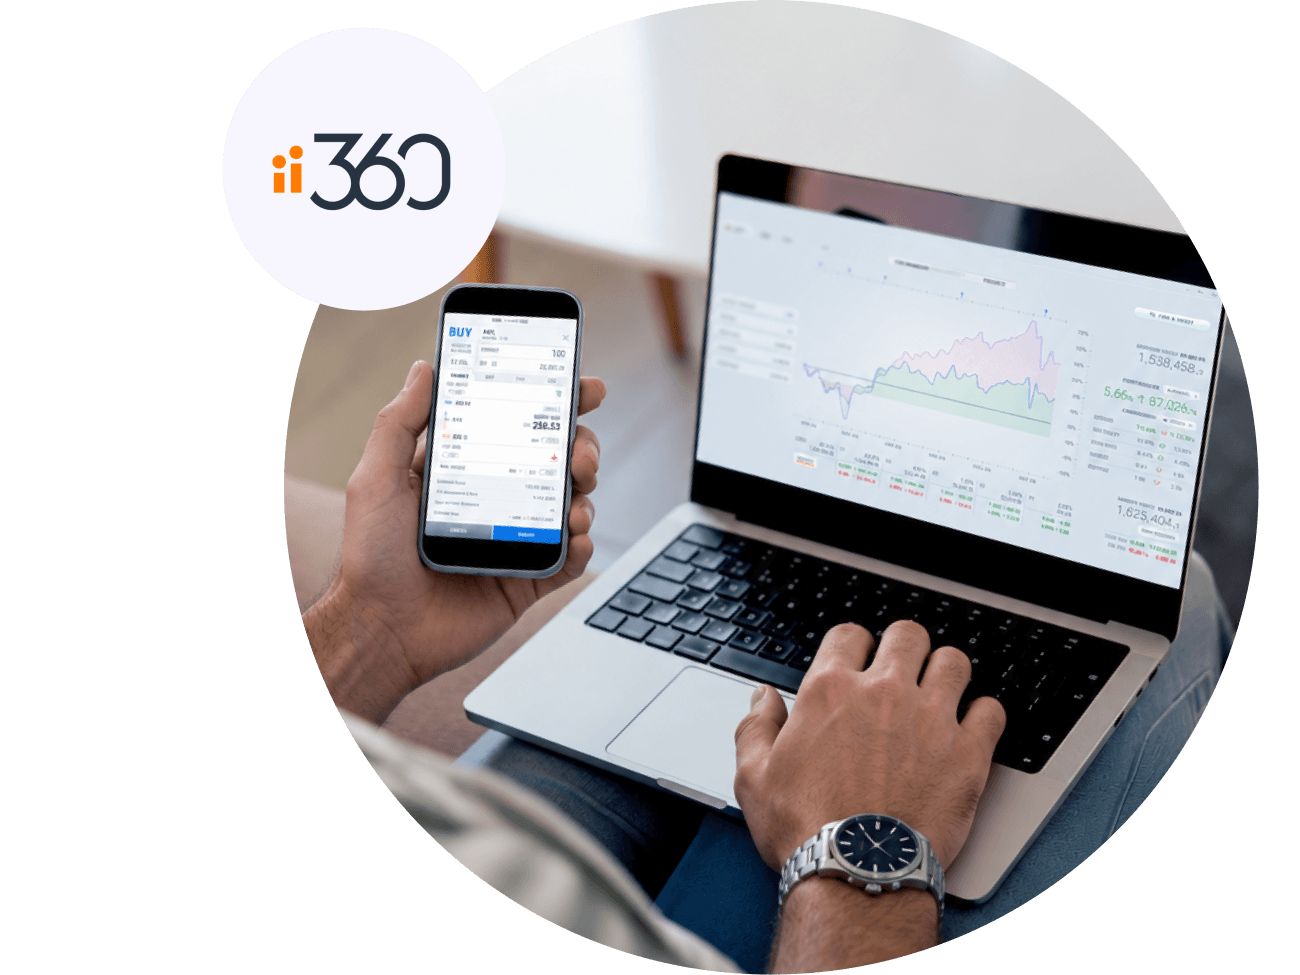
At the other end, ii launched ii360 on 5 October 2026, adding advanced charts, screening and order tools for experienced investors. Interactive Brokers provides execution and clearing; it is a separate company. The next day, ii expanded Premium to include ten monthly trades and business-account benefits at the same subscription price. The product range now stretches from delegating decisions to examining them in considerable detail.
For a customer, the practical choice begins before the dealing screen opens. Do you want to choose every holding, hand over that task, or keep both options available? A long menu can save a committed investor from moving platforms later. It can also give a beginner more decisions than they need. The useful feature is the one that fits the job.
The number worth copying
At June 2026, Aberdeen reported 525,000 ii customers and £107.7 billion in assets under management and administration. The business earns trading and treasury income as well as subscriptions. Its economics are broader than the flat-fee slogan suggests.
The portable lesson is simple enough: price the service you actually use. Count the accounts, trades and currency conversions. Check what a pension transfer would surrender. Then put the annual cost beside your balance. ii has made that calculation central to its identity. Whether it wins your comparison depends on the numbers you bring.