A house is supposed to be the thing that stays put. The price of insuring it has acquired a more adventurous temperament. Dylan DiMarchi’s company, Eventual, starts with the awkward distance between those two facts: people commit to property for years, while the cost of covering it can change at the next annual renewal. The building has a fixed address. The budget gets to travel.
DiMarchi came to this problem by a route that includes Hawaii, Yale, Blackstone and competitive sailing. He studied mechanical engineering and economics, worked in real estate investing and co-founded Eventual with Youssef Doss in 2023. Today he leads a business whose central proposition is a forecast backed by a contractual price guarantee. It is a compact idea with several demanding jobs hidden inside it.
His career is interesting partly because its subjects overlap without becoming interchangeable. Boats, buildings and insurance prices all reward attention to changing conditions. But each requires its own tools. A sailboat controller cannot price a guarantee. An investment model cannot steer a boat. The thread is the effort to make a useful decision before the next change arrives.
A controller for a moving world
At Yale, DiMarchi’s senior thesis involved designing, prototyping and deploying an electromechanical flight controller for a hydrofoil sailboat. The verbs deserve their space. Designing gives a project its proposed answer. Prototyping gives it something to argue with. Deployment takes the argument outdoors.
There is an appealing editorial parallel here with his later work. A controller and a forecast both have to encounter conditions beyond their designer’s desk. Their purposes differ, but neither becomes useful through a handsome diagram alone. That comparison describes the work; it does not require inventing an origin speech for the founder.
His sailing life had begun well before college. Honolulu was his hometown, and he attended Punahou School. At Yale he served as coed captain in spring and fall 2019. His earlier record included an El Toro North American title and two Hawaii C420 state titles. His college biography also listed cinematography, drone building, surfing and slacklining.
The mix has a pleasing amount of actual equipment in it. Cameras, drones and boats make for a different student portrait from a résumé composed entirely of internships. DiMarchi also founded Aerial Images Hawaii before Yale. His early interests already put observation and making things close together, though the later business would give those interests a rather different application.
- HonoluluSailing · Punahou School
- YaleEngineering · Economics · Captaincy
- BlackstoneReal estate investing
- EventualCo-founder · CEO · Since 2023
The house stays. The price moves.
Before Eventual, DiMarchi worked as a real estate investment professional at Blackstone. His December 2025 podcast biography describes $3.5 billion of commercial real estate investment during his tenure. The figure refers to his professional work there, rather than money belonging to him.
Property investing brings an expense forecast into contact with an asset that cannot simply be picked up and moved. Insurance is one of the costs that has to fit into that forecast. A change at renewal can alter the picture even when the owner’s plans have stayed the same.
Eventual’s commercial real estate explanation makes the timing issue explicit. Owners can arrange long-term mortgages or interest-rate caps, yet property insurance still presents a recurring repricing problem. The company’s homeowner explanation asks a related question: if a household can plan around a long-term fixed mortgage, why should this other expense remain so hard to anticipate?
That is a useful question because it narrows the assignment. A company attempting to help with a specific expense needs to identify what its customer is trying to accomplish. Here, the customer wants a way to plan across several renewal dates. The product has to meet that need in terms an owner can understand, while the business behind it has to deal with the uncertainty the owner would rather avoid.
Putting money behind a forecast
Premium Lock works alongside eligible existing property insurance. Eventual predicts future premiums and sets a threshold. When the actual premium exceeds the agreed threshold, the guarantee provides for reimbursement of the difference, subject to its terms. The company describes the homeowner product as a three-year price guarantee.
The distinction between forecasting and guaranteeing matters. A forecast offers a number to consider. A guarantee adds a commitment about what happens if the relevant number is exceeded. That changes the job for the business offering it: the prediction now informs an obligation.
For DiMarchi, it also creates a product that can be explained without asking the homeowner to become an insurance analyst. An owner can keep eligible underlying coverage and consider a separate agreement addressing the price. Premium Lock does not replace the property insurance policy itself. The customer still has a carrier, coverage and renewal decisions.
In July 2025, Eventual announced $7.5 million in total funding across two rounds led by AlleyCorp and Upfront. Other named participants included Clocktower, Harvest, Kindergarten and RXR Arden Digital Ventures. The announcement described a team spanning research, options trading, software and property experience.
“Here’s to control, where it counts.”
Dylan DiMarchi · July 2025
The closing line of DiMarchi’s announcement is modest enough to bear inspection. Control is a large word. Here its proposed territory is specific: a portion of an owner’s future insurance expense. The scale of the ambition depends on how often that ordinary problem appears.
The map keeps changing
DiMarchi also writes about the market his company is trying to forecast. In a June 5, 2026 update, he reported that national home insurance premium growth had slowed to about 5% for the twelve months ending February, following roughly 10% growth in the prior comparison period.
His state figures made the average less comforting. Hawaii showed 15% growth. North Carolina, Nevada and Rhode Island each showed 12%, while Georgia showed 11%. Texas and Florida recorded declines of around 1%. These are figures from Eventual’s analysis, describing that period rather than predicting the next one.
The longer view complicated matters further. His analysis identified Nebraska, Utah, Iowa, Colorado and Idaho as the states with the largest cumulative increases since the start of 2022. The places moving fastest in the recent period were not necessarily the places with the largest accumulated change.
For a founder selling predictability, that distinction is central to the assignment. A homeowner has one property and a particular renewal date. A national average can describe the market while leaving the practical question unanswered. Forecasting has to get closer to the address and the calendar.
Getting into the renewal conversation
The next part of DiMarchi’s story concerns distribution. A forecast and a guarantee need a route to the person who might use them. Eventual has been building that route through the tools insurance agents already use.
On December 18, 2025, the company announced a Canopy Connect integration. Verified, pre-filled insurance data could be used to quote Premium Lock, reducing manual entry. Eventual described the partnership as opening access through a network of more than 20,000 agents. That is a distribution opportunity, rather than a count of customers who purchased.
In August 2026, DiMarchi announced an integration with Ivans Bookroll. It connects an agency’s homeowner book of business to Eventual, synchronizes policy data and generates quotes for eligible clients in bulk. The quotes arrive in the agent’s portal to review and send.
These announcements give the founder story a practical turn. Getting a product into an existing workflow involves permissions, data, screens and someone’s crowded working day. The value of an easier quote is partly the time it gives back to the person explaining the offer. A promising idea can spend quite a while waiting for someone to type an address.
There is also a reason to pay attention to the renewal conversation itself. That is when price becomes immediate. An offer about future premiums has a natural context there: the client is already asking what coverage will cost, and the agent is already helping them make a decision.
A team with room to grow
DiMarchi’s Insurance Leadership Podcast appearance moves from the product to the organization. He discusses a lean team, hiring people capable of taking ownership and giving them room to develop as the company changes. The recurring concern is capacity to grow beyond the first assignment.
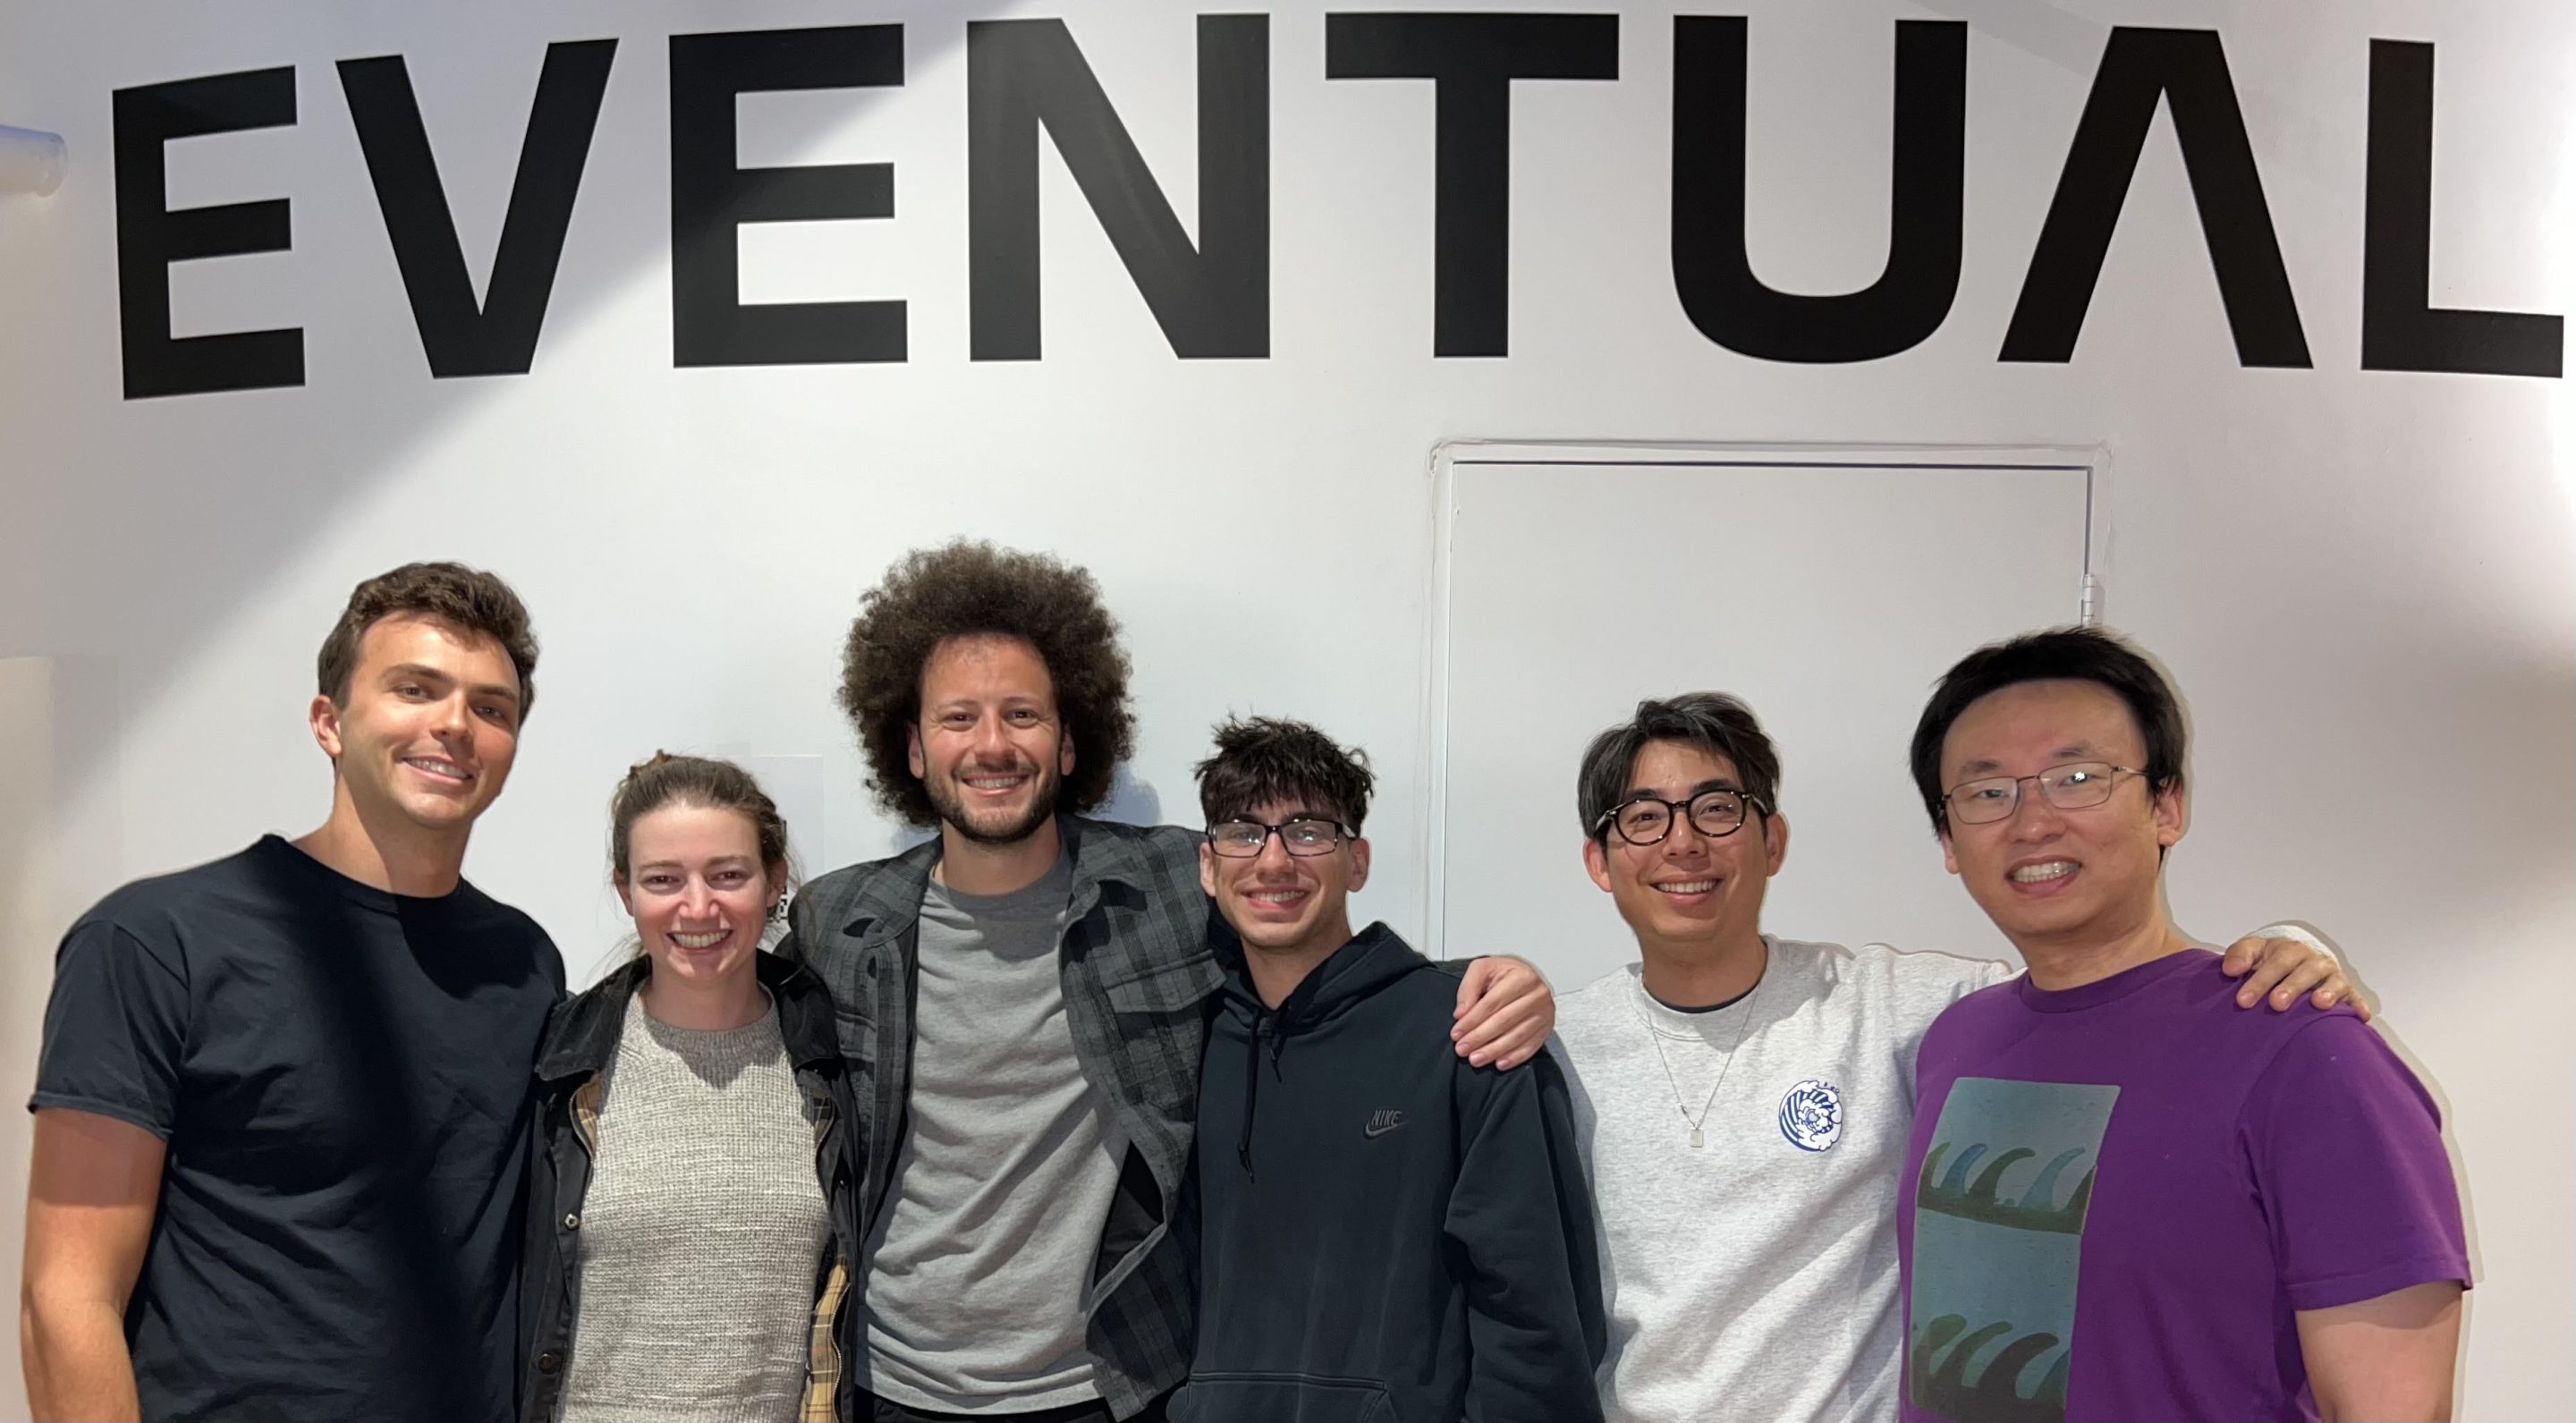
The move from investing at Blackstone to founding a company changes the seat from which he makes decisions. The founder has to choose the people, define the work and build the conditions in which it gets done. The product supplies a reason for the company to exist. It does not supply an organization ready to deliver it.
There is still sailing in the record. At Foiling Week 2024, DiMarchi’s Moth appeared under the name EVENTUAL. Public Moth championship records also place him in the gold fleet at the 2024 worlds. The company name had made it onto a boat, which is a more personal form of branding than another presentation slide.
That detail is a fitting place to leave him. His business concerns prices, contracts and the effort to plan ahead. His racing record concerns an activity where conditions keep changing in plain sight. The parallel is ours; the two pursuits are his. Between the next renewal and the next race, DiMarchi keeps returning to a practical question: what can be anticipated, and what must be handled when it arrives?